Module 5 · Scrap, price and failure
How a cathode gets a price
Level 3 · Specialist 11 min read 4 questions
An exchange price for a standardised plate, a physical premium for getting it where you need it, and a treatment charge for the stage in between. Three prices, not one.
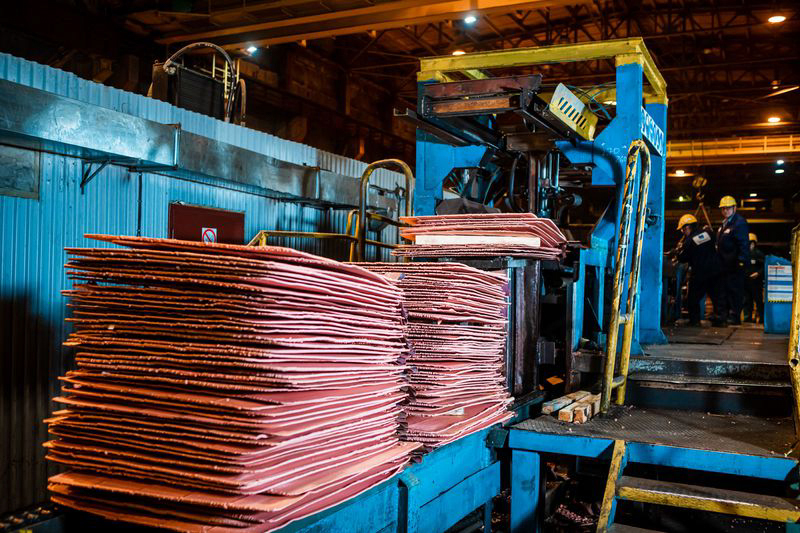
Copper has something oil does not: a single, globally recognised specification for the refined product. LME Grade A cathode is the same thing in Chile, Shanghai and Rotterdam, which is why copper can have a genuine reference price where oil has benchmarks and differentials. But the exchange price is still only one of three numbers that matter.
The exchange price
Three exchanges carry most of the trade: the London Metal Exchange, COMEX in the United States and the Shanghai Futures Exchange. Each lists a copper contract with a defined quality, warehouse network and delivery mechanism. Prices track each other closely, because metal and money can move between them, but they are not identical - the spreads reflect freight, duty, currency, local balance and occasionally policy.
The LME's structure is unusual and worth knowing: it trades on a daily prompt-date basis rather than in monthly contracts, reflecting its origins in financing physical shipments with known arrival dates, and its warehouse network is the delivery backbone. Contango and backwardation mean the same things here as in lesson 7 of the oil course, and drive the same storage arithmetic.
| Series | Basis |
|---|---|
| IMF global price of copper | Grade A cathode, LME/COMEX/NYMEX average, annual averages via FRED |
| US producer cathode | Annual average, cents per pound, COMEX plus premium |
| COMEX high grade | Annual average, cents per pound, first position |
| LME grade A cash | Annual average, cents per pound |
Annual averages; see the material page for the series and their years · USGS Mineral Commodity Summaries 2026, as published on commodityeducation.com/material/copper; and IMF primary commodity prices via FRED
All four are reference annual averages, not live market quotations. They exist to show scale and long-run shape, and the site says so on every chart.
The physical premium
The exchange price is for metal in an exchange warehouse. A fabricator needs metal at its own gate, of a particular shape, on a particular date, from a brand it trusts. The difference is the physical premium, negotiated annually for term supply and traded in the spot market in between.
- It varies by region - a premium into one port is not a premium into another - and the regional spread is a direct read on where metal is tight.
- It varies by brand, because not all registered brands perform identically in a melt shop.
- It can move sharply while the exchange price does not, and when it does, it is usually telling you something the exchange price is not.
The third price: treatment charges
For a miner selling concentrate rather than cathode, the realised price is the exchange price for the payable metal, minus the TC/RC from lesson 7, minus penalties, plus by-product credits. So a miner's revenue can fall while the copper price rises, if treatment charges rise faster - which is exactly what happens when concentrate supply outruns smelting capacity.
Inventories, and what they do and do not show
Exchange warehouse stocks are published daily and are widely watched. They are also a small and unrepresentative slice of world inventory: most metal sits in producer, consumer, trader and bonded warehouse stocks that are not reported daily or at all. Metal moving into an exchange warehouse is often a financing decision rather than a demand signal. Read exchange stocks as one indicator among several, not as the world's copper inventory.
- Grade A standardisation is what gives copper a true reference price; oil has no equivalent.
- Exchange price, physical premium and treatment charge answer three different questions.
- Exchange warehouse stocks are a visible minority of world inventory and respond to financing as well as demand.
- Grade A
- The LME refined copper specification.
- Physical premium
- The negotiated charge above the exchange price for delivered metal of a given brand and shape.
- Prompt date
- The LME's daily-dated delivery structure, in place of monthly contracts.
- How metals are pricedon this site
- Copper price serieson this site
- Oil benchmarks, for contrastanother lesson
- London Metal Exchangeprimary source
Check yourself
1. A copper miner selling concentrate sees the LME price rise but its realised revenue per tonne fall. The most likely cause is:
A concentrate seller receives the exchange price for payable metal minus TC/RC. Rising treatment charges can more than offset a rising metal price.
2. The physical premium measures:
It is the gap between exchange-warehouse metal and metal actually delivered where a fabricator needs it.
3. A rise in LME warehouse stocks is:
Exchange stocks are a visible minority of inventory and respond to financing arbitrage as well as to consumption.
4. Copper can have a genuine single reference price where crude oil cannot because:
Grade A is Grade A anywhere. Crude is a mixture that differs by field, which is why oil needs benchmarks and differentials.