Module 3 · Stump to mill
Chips, sawdust, shavings and bark: how the other half is sold
Level 2 · Working knowledge 11 min read 4 questions
Roughly half of every log leaves the mill as something other than lumber. Each stream has its own buyers, its own unit and its own price, and together they often decide whether the mill is profitable.
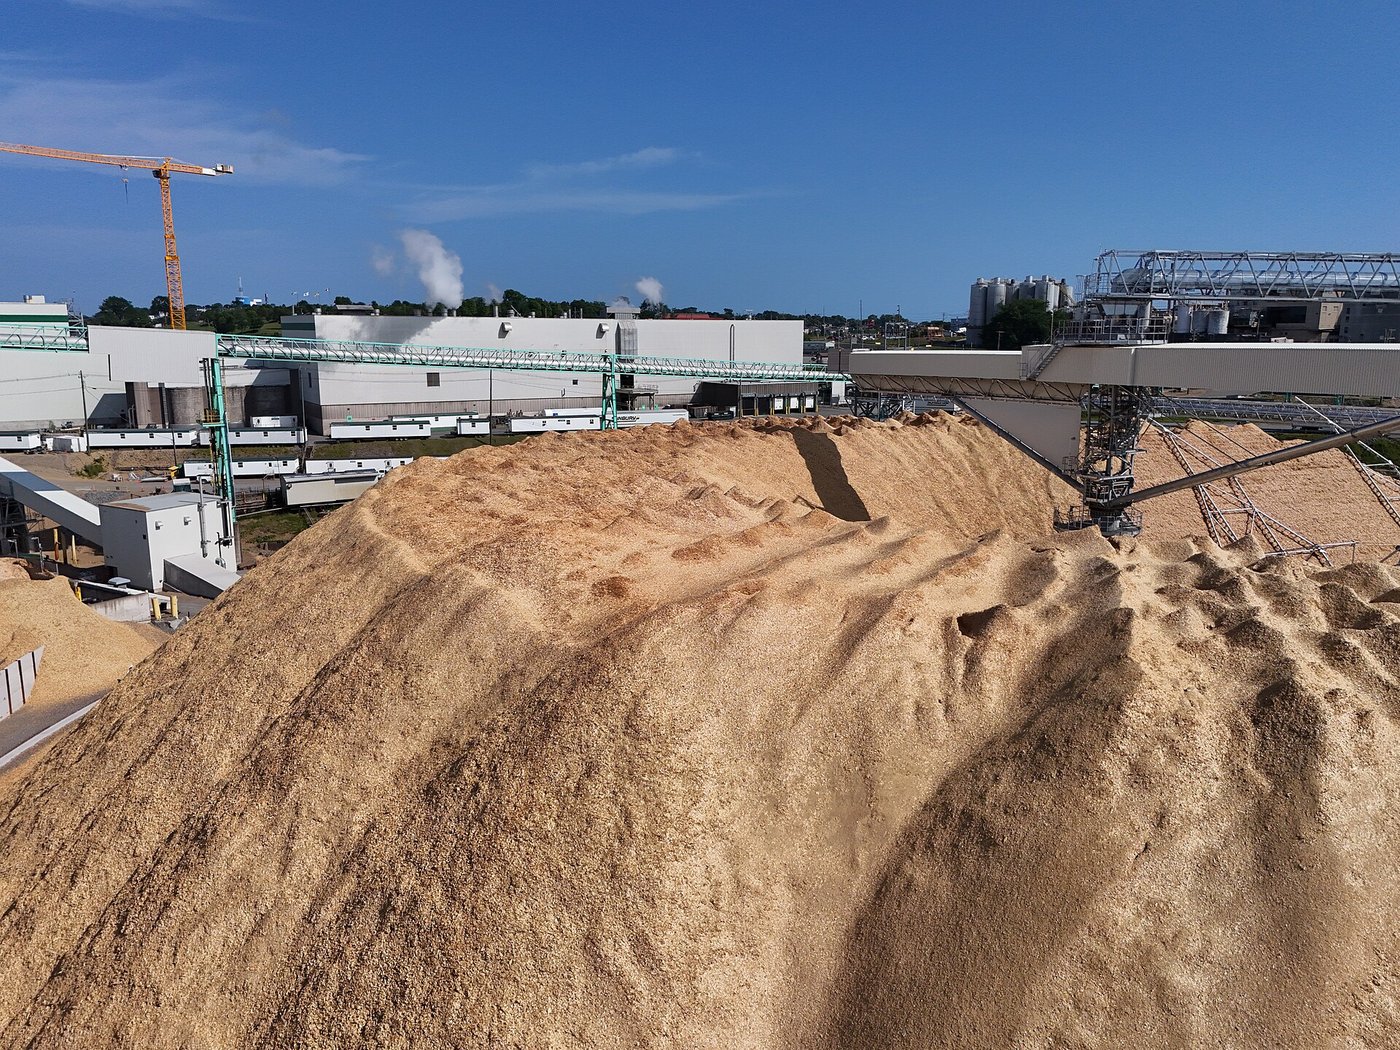
This is the lesson that answers the question people usually phrase as 'what happens to the scrap'. The honest answer is that a modern sawmill has almost no scrap. It has four co-products, each with a separate market, and it sells all of them.
The four streams
| Stream | Where it comes from | Sold as | Buyers |
|---|---|---|---|
| Clean chips | Slabs, edgings and trim, run through a chipper; bark-free and screened to size | Green or dry tons, sometimes by the cunit | Pulp and paper mills; OSB and particleboard plants; biomass power |
| Sawdust | Saws and trimmers | Green or dry tons, by the truckload | Pellet plants; particleboard and MDF plants; animal bedding; composting and soil blends; boiler fuel |
| Planer shavings | The planer mill, and dry, which makes them the most valuable fine residual | Dry tons, or compressed bales | Animal bedding - the premium market, especially equine; pellet plants; panel plants |
| Bark | The debarker | Cubic yards or tons | Landscape mulch; growing media and soil blends; boiler fuel for the mill's own kilns |
Current commercial practice · Residual markets as described in USDA Forest Service Forest Products Laboratory and FAO, Global forest products trade and production, 2024 update
Prices for all four are regional and freight-dominated. Residuals are low value per tonne and bulky, so the economics collapse beyond a fairly short haul - which is why a mill's viability depends on having a pulp mill, panel plant or pellet plant within reach.
Why this is not a side business
Residuals are frequently the difference between a sawmill that runs and one that does not. Three reasons:
- The log is already paid for. The residual arrives at zero marginal raw material cost. Every dollar of residual revenue is close to a dollar of contribution.
- Disposal is not free. A mill without buyers must still move the material, and paying to dispose of half your input is not survivable.
- Energy. Bark and wet residuals fire the boilers that run the kilns. Many mills are energy self-sufficient for heat, and some generate electricity. That is a real cost avoided, not a sustainability talking point.
The pellet trade
The newest large buyer of fine residuals is the wood pellet industry, which compresses dried sawdust and shavings - and increasingly roundwood grown for the purpose - into uniform pellets that can be handled like a bulk commodity and burned in converted coal plants and domestic boilers.
| Measure | 2024 |
|---|---|
| Production | 48 million tonnes |
| Traded internationally | 31 million tonnes |
| Europe, share of production | 47% |
| North America, share of production | 28% |
| Asia-Pacific, share of production | 22% |
| Europe, share of consumption | 70% |
| Asia-Pacific, share of consumption | 28% |
2024 · FAO, Global forest products trade and production, 2024 update
Note the asymmetry between the production and consumption shares: North America produces well above what it consumes and Europe the reverse, which is why roughly two thirds of world pellet output crosses a border.
Pellets are the clearest case in this course of a residual becoming a traded commodity in its own right, with long-term offtake contracts, dedicated port terminals and ocean shipping. They are also the most contested: whether burning them is genuinely low carbon depends on what was harvested, what regrows, over what period, and what the alternative use of that wood would have been. This course states the trade structure and does not attempt to settle that argument.
What else the world does with the non-lumber half
| Product | 2024 production | Change on 2023 |
|---|---|---|
| Industrial roundwood removals | 1.96 billion cubic metres | +2% |
| Wood-based panels | 393 million cubic metres | +5% |
| Wood pulp | 189 million tonnes | +3% |
| Wood pellets | 48 million tonnes | - |
| Recovered paper consumed | 243 million tonnes | +1% |
2024 · FAO, Global forest products trade and production, 2024 update
World roundwood removals run at roughly 4 billion cubic metres a year in total, about half of which is used as fuel directly as fuelwood or converted to charcoal and pellets. The industrial roundwood row above is the other half.
That last note is the one to carry out of this lesson. Half of all the wood cut in the world is burned, most of it as domestic fuelwood in countries where it is the primary cooking fuel. The industrial chain this course describes - sawmills, panels, pulp, pellets - is the other half.
- A modern sawmill has four co-products, not scrap: chips, sawdust, shavings and bark.
- Planer shavings are the premium fine residual because they are dry; residual markets are freight-limited and regional.
- Residual supply follows lumber production, so a sawmill downturn starves pulp, panel and bedding buyers.
- Residual
- A mill co-product that is not lumber: chips, sawdust, shavings or bark.
- Green ton / dry ton
- Weight as delivered / weight excluding moisture. Residuals are usually sold on one or the other and the difference is large.
- Cunit
- 100 cubic feet of solid wood.
- FAO forest products production and tradeprimary source
- Why recycling is not enoughon this site
- By-products, the general problemon this site
Check yourself
1. Planer shavings command a premium over sawdust mainly because they are:
Dryness is what the bedding and pellet markets are paying for; drying green material costs energy.
2. A pulp mill finds its chip supply short even though its own market is strong. The most likely cause is:
Residual supply is a by-product of lumber production. This is the same by-product dependency the copper course describes for tellurium.
3. Roughly what share of world roundwood removals is used as fuel rather than as industrial raw material?
World removals run at roughly 4 billion cubic metres, about half of which is fuelwood or is converted to charcoal and pellets.
4. Why are mill residual markets strongly regional?
Freight economics limit the haul radius, which is why a sawmill's viability depends on having a residual buyer nearby.