Module 3 · Stump to mill
Selling standing timber
Level 2 · Working knowledge 11 min read 4 questions
Four price bases, several kinds of owner, and a contract structure that decides who carries the risk of what is actually inside the trees.
A standing tree is not lumber and its owner is usually not in the timber business. The transaction that turns one into the other is the timber sale, and almost every misunderstanding about what wood is worth comes from confusing the four different prices involved.
The four prices
- Stumpage
- What the landowner receives for standing timber. It is a residual: delivered log value minus the cost of felling, skidding, loading and hauling, minus the logger's margin. Everything that makes logging harder - steep ground, wet ground, poor access, small trees, long haul - comes out of stumpage.
- Delivered log price
- What a mill pays for a log delivered to its yard. This is the number log buyers quote and the number that appears in market reports.
- Mill price
- What the sawmill sells lumber for at its gate, per MBF by species and grade.
- Wholesale and retail
- What a distributor and then a retailer charge, having added sorting, drying, inventory, credit and delivery.
Who owns the trees
| Owner type | Behaviour |
|---|---|
| Family and small private forests | Large in aggregate, fragmented, often selling once in a generation with little experience. The group most exposed to a bad sale |
| Timberland investment managers and forest REITs | Professional owners managing timber as a financial asset; harvest timing is partly a financial decision |
| Integrated forest products companies | Own land to supply their own mills; harvest to feed capacity |
| Public forests | Sold through formal, published sale processes with cruise data supplied; harvest levels set by policy as well as by market |
| Agricultural and other landowners | Trees are incidental to the main land use; harvest is often triggered by an unrelated event |
Structural description · Ownership categories as used in USDA Forest Service Forest Inventory and Analysis reporting
Shares of area and of harvest by ownership type vary widely by region and are published by FIA at state level.
How the sale is actually done
Lump sum or pay-as-cut
The contract form decides who carries the risk of what is actually inside the trees.
- Lump sum. A single price for the marked timber, paid up front. The buyer carries the risk that the stand contains less or worse timber than the cruise suggested, and takes the benefit if it contains more. Simpler for the landowner, and the tax treatment is often straightforward.
- Pay-as-cut, or per-unit. The landowner is paid an agreed rate per unit as logs are scaled at the mill. The landowner carries the volume and grade risk, and needs to be able to verify the scale tickets - which requires either trust or an agent.
Harvest systems, and why they cost what they cost
- Ground-based, mechanised
- Feller-buncher, skidder or forwarder. The cheapest system per tonne and the standard on flat to moderate ground.
- Cable and skyline
- Logs are winched uphill on cables from steep ground. Much more expensive, and it comes straight out of stumpage.
- Cut-to-length
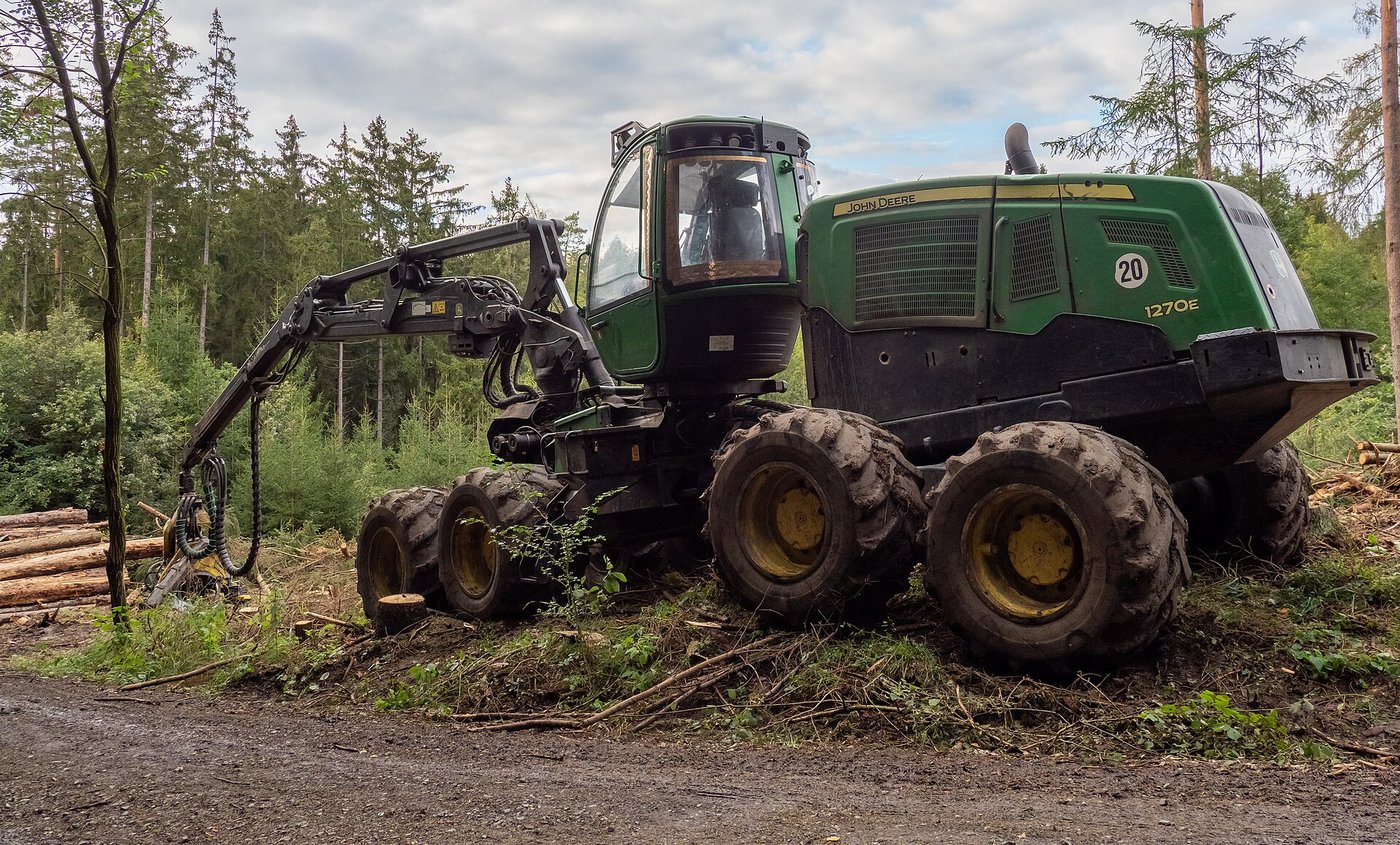
- A harvester fells, delimbs and bucks at the stump and a forwarder carries logs out rather than dragging them. Less site damage, leaves slash on the trail, common in Nordic practice.
- Helicopter
- For inaccessible high-value stands only. The cost is such that only exceptional timber justifies it.
Two structural facts about logging contractors are worth carrying. They are small businesses with very large capital equipment and thin margins, and they are the part of the chain that absorbs the volatility: when mills cut quotas, contractors idle expensive machines. And their availability is a real constraint on supply response - a region that has lost its logging capacity cannot increase harvest quickly even when prices rise, which is the timber version of the service-company constraint in the oil course.
- Stumpage is a residual, so it absorbs every cost of difficulty and can go to zero while lumber prices are fine.
- Lump sum puts volume risk on the buyer; pay-as-cut puts it on the seller.
- Logging contractor capacity is a real constraint on how fast harvest can respond to price.
- Stumpage
- The price paid for standing timber.
- Cruise
- A sample-based estimate of a stand's volume, species and grade.
- Lump sum / pay-as-cut
- A fixed price for marked timber / payment per unit as logs are scaled.
- Bucking
- Cross-cutting a felled stem into logs of chosen lengths.
- USDA Forest Inventory and Analysisprimary source
- Cost curves, the general ideaon this site
Check yourself
1. Stumpage prices are more volatile than lumber prices because stumpage is:
Being a residual, it absorbs the full swing in both delivered prices and operating costs, and can reach zero.
2. Under a lump sum timber sale contract, who carries the risk that the stand contains less volume than the cruise estimated?
The buyer pays a fixed sum for the marked timber and takes both the shortfall risk and the upside.
3. Cable or skyline yarding is used on steep ground and materially reduces:
Higher logging cost comes straight out of the residual, so the same timber is worth less standing on steep ground.
4. A region that has lost logging contractors cannot increase harvest quickly because:
It is a capacity constraint in the middle of the chain - the same pattern as service companies in oil and smelters in copper.