Qu'est-ce que c'est ?
A group of naturally fibrous minerals that are strong, fireproof, cheap — and cause fatal lung disease decades after exposure.
Pourquoi est-ce important ?
It is here because it is still mined and traded, and because it is the standard against which every other fibrous mineral is now assessed.
Where it is in the Earth
Asbestos is not a single mineral but a collective name for a group of naturally occurring silicate minerals that grow in fibrous form — meaning that, rather than forming compact crystals, they develop as long, thin, separable threads that can be pulled apart by hand. Two distinct mineral families produce these fibres. The serpentine family contributes chrysotile, sometimes called white asbestos, which accounts for the great majority of everything ever mined. The amphibole family contributes several rarer varieties, including amosite and crocidolite, each with a characteristic colour and fibre geometry. What unites them is that the fibres are thermally stable, chemically resistant, and have high tensile strength — properties that arise directly from the atomic structure of the silicate chains from which they are built.
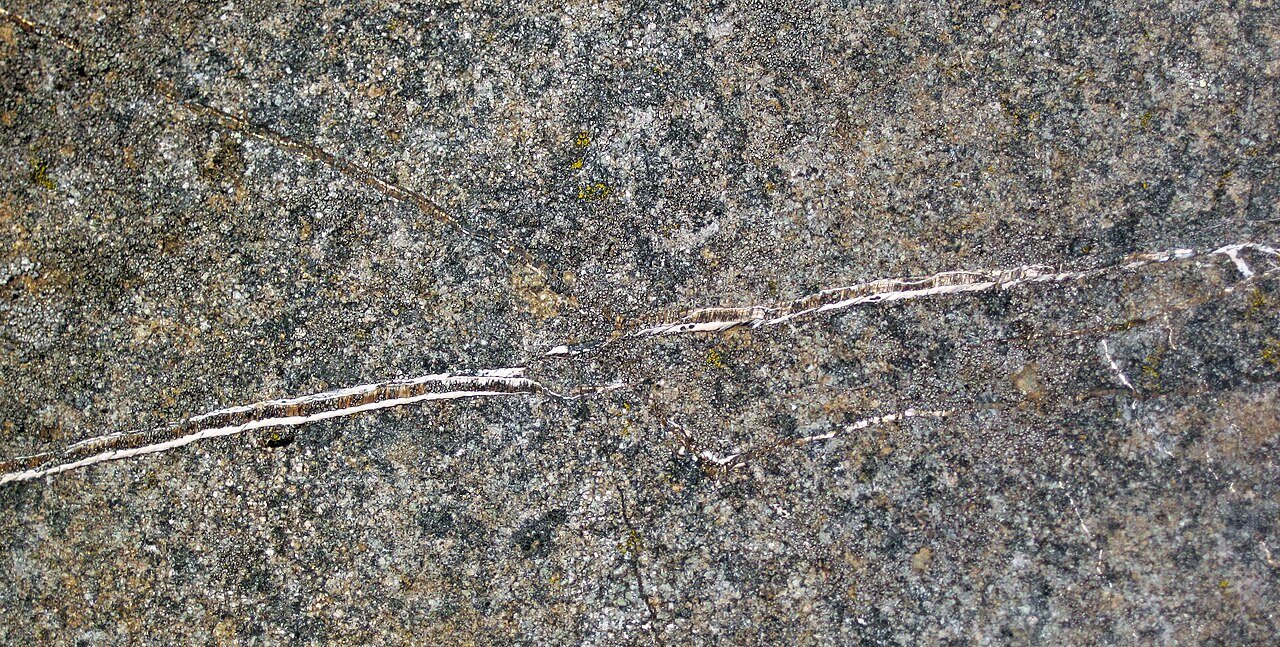
Chrysotile deposits form through a process called serpentinisation, in which hot, mineral-rich water reacts with ultramafic rock — rock that is poor in silica and rich in magnesium and iron, of the kind that makes up much of the deep oceanic crust and the upper mantle. When these rocks are pushed upward along tectonic suture zones, or where ancient ocean floor has been folded into continental mountain belts, the change in temperature and pressure allows circulating groundwater to alter the original minerals into serpentine group minerals. Where this alteration is intense and the fluid pathways are well developed, chrysotile fibres grow in veins that cut through the serpentinite host rock, filling fractures as the rock cools and contracts. The fibre grows perpendicular to the vein walls, a texture geologists call cross-fibre, or parallel to the walls in a form called slip-fibre. The length and continuity of these veins govern how much recoverable fibre a deposit contains.
This geological history explains the geography of reserves. The world's largest known deposits sit in parts of Russia, Kazakhstan, and Brazil where ancient ultramafic terranes have been preserved at or near the surface and subjected to the right degree of hydrothermal alteration. Russia alone holds the dominant share of identified global reserves. Amphibole asbestos deposits are geologically distinct — they form in metamorphic settings rather than through serpentinisation — and they are now rarely mined anywhere, partly because of their greater association with the most aggressive forms of asbestos-related disease.
Getting it out
Almost all asbestos has been extracted by open-pit methods, and this reflects the geometry of the deposits. Chrysotile occurs in networks of veins distributed through large volumes of serpentinite host rock. There is no narrow, high-grade seam to follow underground; instead, ore and waste are intermixed across a broad area, and the economics favour stripping large quantities of material from the surface rather than developing underground access. Pits at major operations have grown over decades into some of the largest excavations in the world by volume, a consequence of the relatively low fibre content of the ore and the scale of production needed to make mining viable.
Grade in asbestos mining is expressed as the weight of recoverable fibre per tonne of ore, and it is low by the standards of most mined commodities. This means that for every tonne of finished fibre produced, a substantially larger mass of crushed rock must be moved and processed. The stripped and milled rock that contains no recoverable fibre, called tailings, accumulates in large volumes around processing facilities. Managing these tailings is a significant part of the physical and regulatory burden of operating an asbestos mine, because the waste rock itself contains residual fibrous material and must be contained to prevent airborne dispersal.
In practice, blasting loosens the ore, which is then loaded and hauled to a crushing and milling circuit on site. The decision about where to draw the boundary between ore and waste — the cut-off grade — depends on the price of fibre and the cost of processing, just as in any other mine, but the public-health dimensions of asbestos mean that regulatory requirements around dust suppression and worker protection add a layer of operating cost and procedural complexity that has no close parallel in most other industrial mineral operations.
What pulls on it
Demand for asbestos has contracted dramatically in the countries that have banned it — more than sixty have done so — but global consumption has not fallen to zero because a different group of countries continues to use it, primarily in fibre-cement building products. Fibre-cement sheet and board, used for roofing and wall cladding in lower-income construction markets, represents the dominant remaining end use for chrysotile globally. The fibres act as reinforcement within the cement matrix in much the same way that steel rebar reinforces concrete, distributing stress and preventing brittle cracking. In markets where this application remains legal and affordable alternatives have not yet achieved the same price point, demand has proved relatively stable.
The countries that still produce and consume asbestos — principally Russia, China, Kazakhstan, Brazil, and several nations in South and Southeast Asia — tend to frame chrysotile specifically as less hazardous than the amphibole varieties that have been most strongly associated with mesothelioma, the cancer of the lining of the lung and abdomen. The scientific and regulatory consensus in most high-income countries does not accept a meaningful safety distinction between fibre types at occupational exposure levels, and this disagreement is itself a structural feature of the market: it explains why consumption has not converged globally toward zero and why the commodity still appears in trade statistics at all.
For demand to change sharply downward, two things would need to happen simultaneously: the remaining producing and consuming countries would need to adopt bans or severe restrictions, and affordable fibre-cement substitutes — typically using polyvinyl alcohol, cellulose, or glass fibres as reinforcement — would need to reach cost parity in those markets. For demand to stabilise or recover, the regulatory trajectory in key consuming markets would need to halt or reverse. Neither scenario can be forecast from the supply data alone; the trajectory is as much a matter of national regulatory decisions and bilateral trade policy as it is of geology or processing economics.
Qui le produit
Voir sur une carte →Mine production
Mine productionmetric tons 2025 (estimé) Total mondial 960,000 metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of fibre. · source ↗
Faire défiler le tableau latéralement pour afficher les colonnes restantes.
| Pays | Production | Part mondiale |
|---|---|---|
| Russia | 310,000 | 32.3% |
| Kazakhstan | 250,000 | 26.0% |
| China | 250,000 | 26.0% |
| Brazil | 150,000 | 15.6% |
| United States | Zero | — |
| Total mondial | 960,000 | 100% |
« Withheld » signifie que l'USGS a supprimé le chiffre afin de ne pas divulguer les données d'une entreprise individuelle — cela ne signifie pas zéro. La somme des lignes par pays ne correspond pas toujours au total mondial, car la source arrondit chaque chiffre de manière indépendante et ne détaille pas toujours une ligne « autres pays ».
Qui détient les réserves
Reserves
Reservesmetric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Pays | Réserves | Part mondiale |
|---|---|---|
| Russia | 110,000,000 | 73.3% |
| Kazakhstan | 20,000,000 | 13.3% |
| Brazil | 11,000,000 | 7.3% |
| China | 7,100,000 | 4.7% |
| United States | Zero | — |
| Total mondial | 150,000,000 | 100% |
Prix
average U.S. customs unit value of imports, dollars per ton
Moyenne annuelledollars per ton
Base: average U.S. customs unit value of imports, dollars per ton. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.