Module 3 · Midstream: moving the barrel
Tankers, freight and the straits that matter
Level 2 · Working knowledge 10 min read 4 questions
Most crude crosses an ocean. Ship size decides which ports and canals are available, freight is a live component of the delivered price, and a handful of narrow passages carry a large share of the world's seaborne oil.
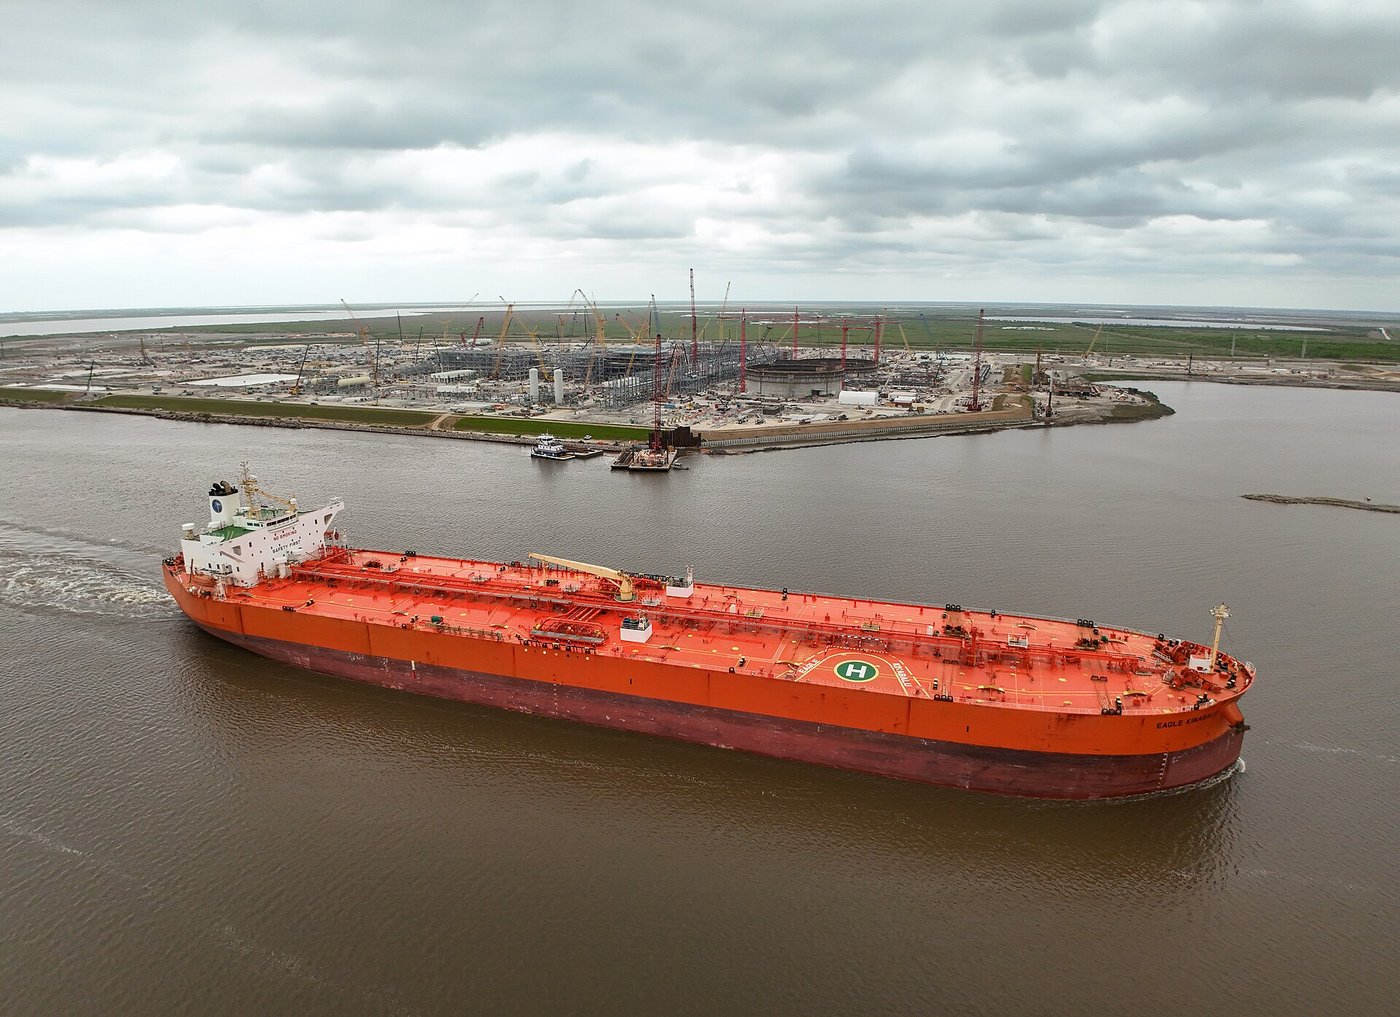
Oil's geography of supply and its geography of demand do not match, so most of it goes to sea. The shipping market is a separate industry with its own cycles, and freight is not a footnote to the oil price - it is part of the delivered price, and it moves independently.
Ship classes, and why the names matter
Tanker classes are defined by size, and size determines which ports, canals and straits a ship can use at all. The names are commercial conventions rather than a standard, but they are used consistently enough to be a working vocabulary.
| Class | Rough capacity | Typical use |
|---|---|---|
| Aframax | About 0.5-0.8 million barrels | Short-haul and regional trades, ports with draft limits |
| Suezmax | About 0.8-1.0 million barrels | The largest that can transit the Suez Canal fully laden |
| VLCC (very large crude carrier) | About 2 million barrels | Long-haul, especially Middle East to Asia |
| ULCC (ultra large crude carrier) | Above about 3 million barrels | Rare; very few ports can handle them |
Conventional class definitions; capacities are approximate and vary by vessel · Standard shipping-market classifications as used in EIA and IEA market reporting
Capacity in barrels depends on the density of the cargo. The same ship carries fewer barrels of a heavy crude than of a light one for the same deadweight.
Freight is part of the price
A cargo is normally quoted either FOB - free on board, priced at the loading port, with the buyer arranging and paying for shipping - or CIF/CFR, priced delivered, with the seller arranging it. The difference between the two for the same cargo is the freight, the insurance and the risk of the voyage. When freight rates spike, long-haul barrels become relatively less attractive than short-haul ones without any change in the oil itself, and trade routes reshuffle.
The chokepoints
A chokepoint is a narrow passage through which a large share of seaborne trade must pass, with no quick alternative. Oil has a small number of them, and they are the most studied physical risk in the commodity.
- Strait of Hormuz
- The exit from the Persian Gulf. The single most important passage for seaborne crude, with limited pipeline bypass capacity.
- Strait of Malacca
- The shortest route between the Indian Ocean and East Asia, and therefore the main artery for Middle East crude heading to Asian refiners.
- Suez Canal and the SUMED pipeline
- The short route between the Gulf and Europe. The canal has a draft limit, and the parallel pipeline exists precisely because of it.
- Bab el-Mandeb
- The southern entrance to the Red Sea, and therefore the approach to Suez.
- Turkish Straits, Danish Straits, Panama Canal
- Regionally critical rather than globally, but binding for particular trades.
This site keeps a general treatment of the idea at chokepoints, which is worth reading alongside this lesson: the same logic applies to concentration in refining and in processing, where the chokepoint is a plant rather than a strait. Lesson 15 returns to this.
Ship-to-ship transfers and opacity
Cargoes are sometimes transferred between vessels at sea, legitimately - to break a large cargo into parcels for shallow ports, or to top up a VLCC - and sometimes to obscure origin. Transponders can be switched off, documents can be re-papered, and blends can be relabelled. The result is that seaborne flow data is an estimate built from satellite tracking and port records, not a measurement. Treat single-source flow figures accordingly.
- Tanker class sets which routes exist for a cargo at all; freight is a live part of the delivered price.
- A handful of straits carry a large share of seaborne crude and have no quick alternatives.
- Disruption raises cost through insurance, rerouting and fleet utilisation long before any barrel stops moving.
- VLCC
- Very large crude carrier, roughly two million barrels.
- FOB / CIF
- Priced at the load port, buyer ships / priced delivered, seller ships and insures.
- Chokepoint
- A narrow passage carrying a large share of trade with no quick alternative.
- Chokepointson this site
- Export controls and sanctionson this site
- Port of Rotterdam bulk terminalson this site
- EIA Today in Energyprimary source
Check yourself
1. Why does a spike in tanker freight rates change which refineries buy which crudes?
Freight is part of the delivered cost, and it is distance-weighted. When it rises, the relative advantage shifts towards nearby sources.
2. A cargo is sold FOB. Who arranges and pays for the voyage?
FOB prices the cargo at the load port; the buyer takes it from there, arranging and paying for shipping and insurance.
3. Rerouting tankers around a cape instead of through a canal tightens the global freight market because:
Effective fleet capacity is ships multiplied by voyages per year. Lengthening every voyage removes capacity even though no ship has been lost.
4. Published seaborne crude flow figures should be treated as:
Flow data is inferred. Ship-to-ship transfers, transponder gaps and re-papering all degrade it, which is why sources disagree.