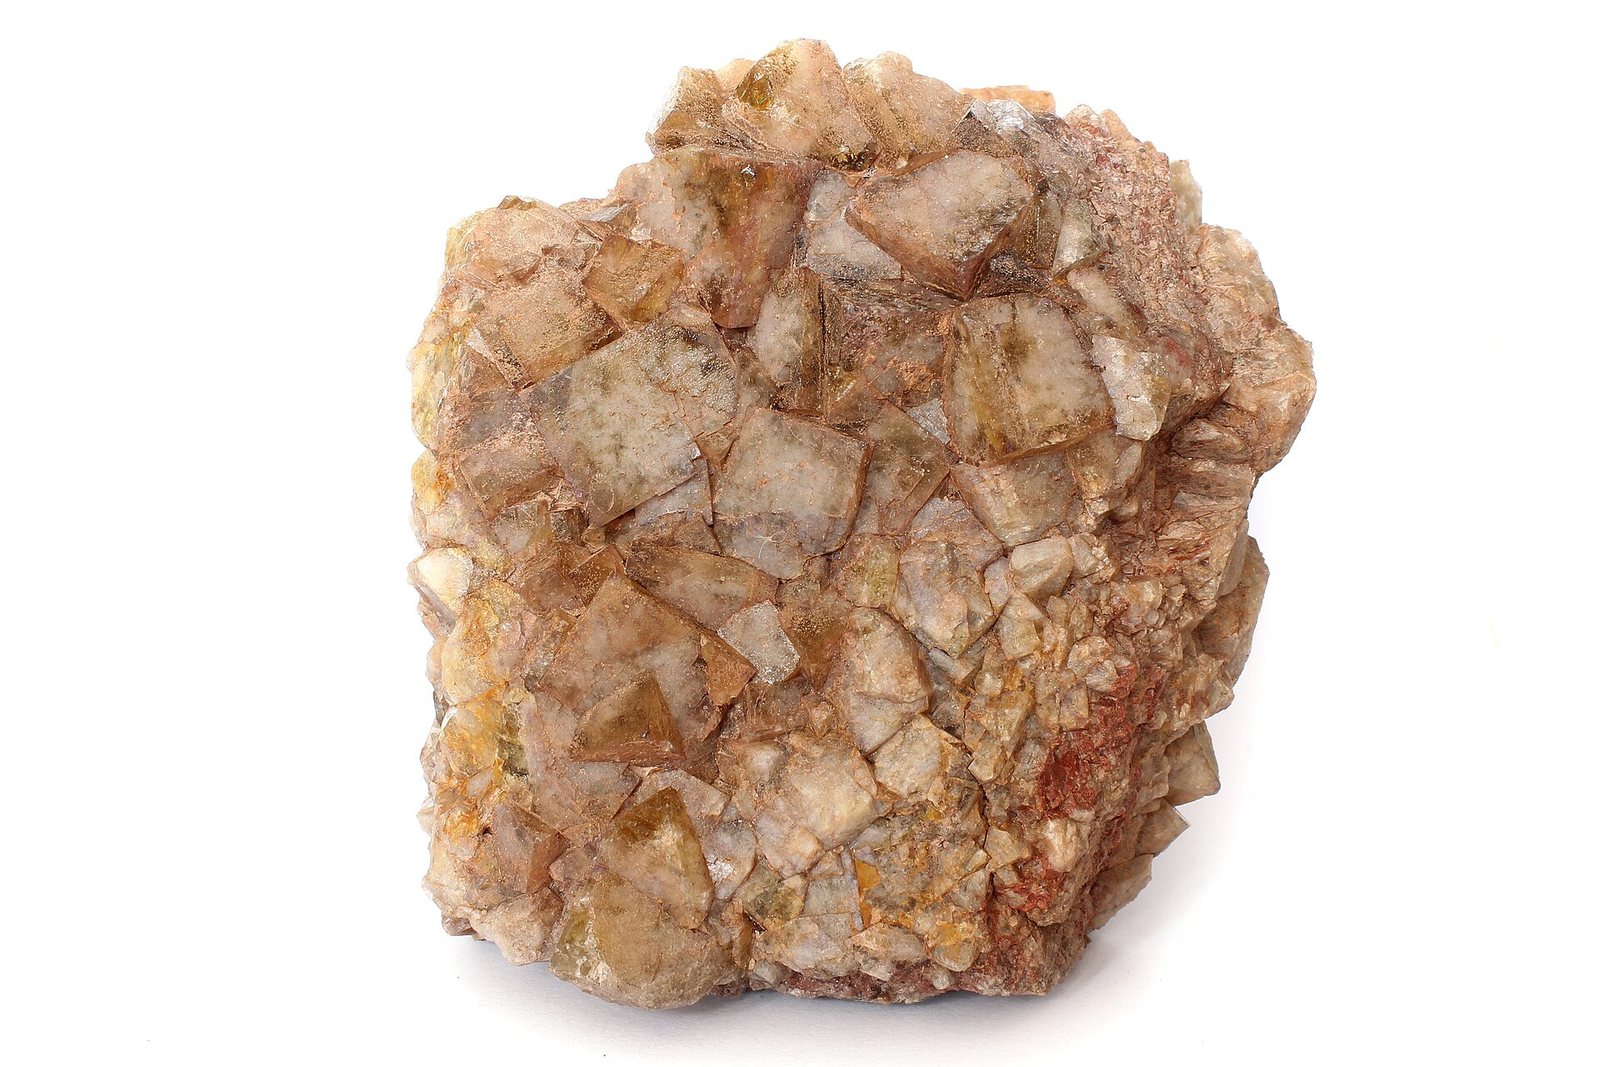
ما هو؟
Calcium fluoride, the mineral that every fluorine atom in industry ultimately comes from — including the fluorine in battery electrolyte.
لماذا يهم هذا؟
Hydrofluoric acid from fluorspar makes refrigerants, aluminium smelting flux, uranium hexafluoride and the LiPF6 salt in lithium-ion cells.
Where it is in the Earth
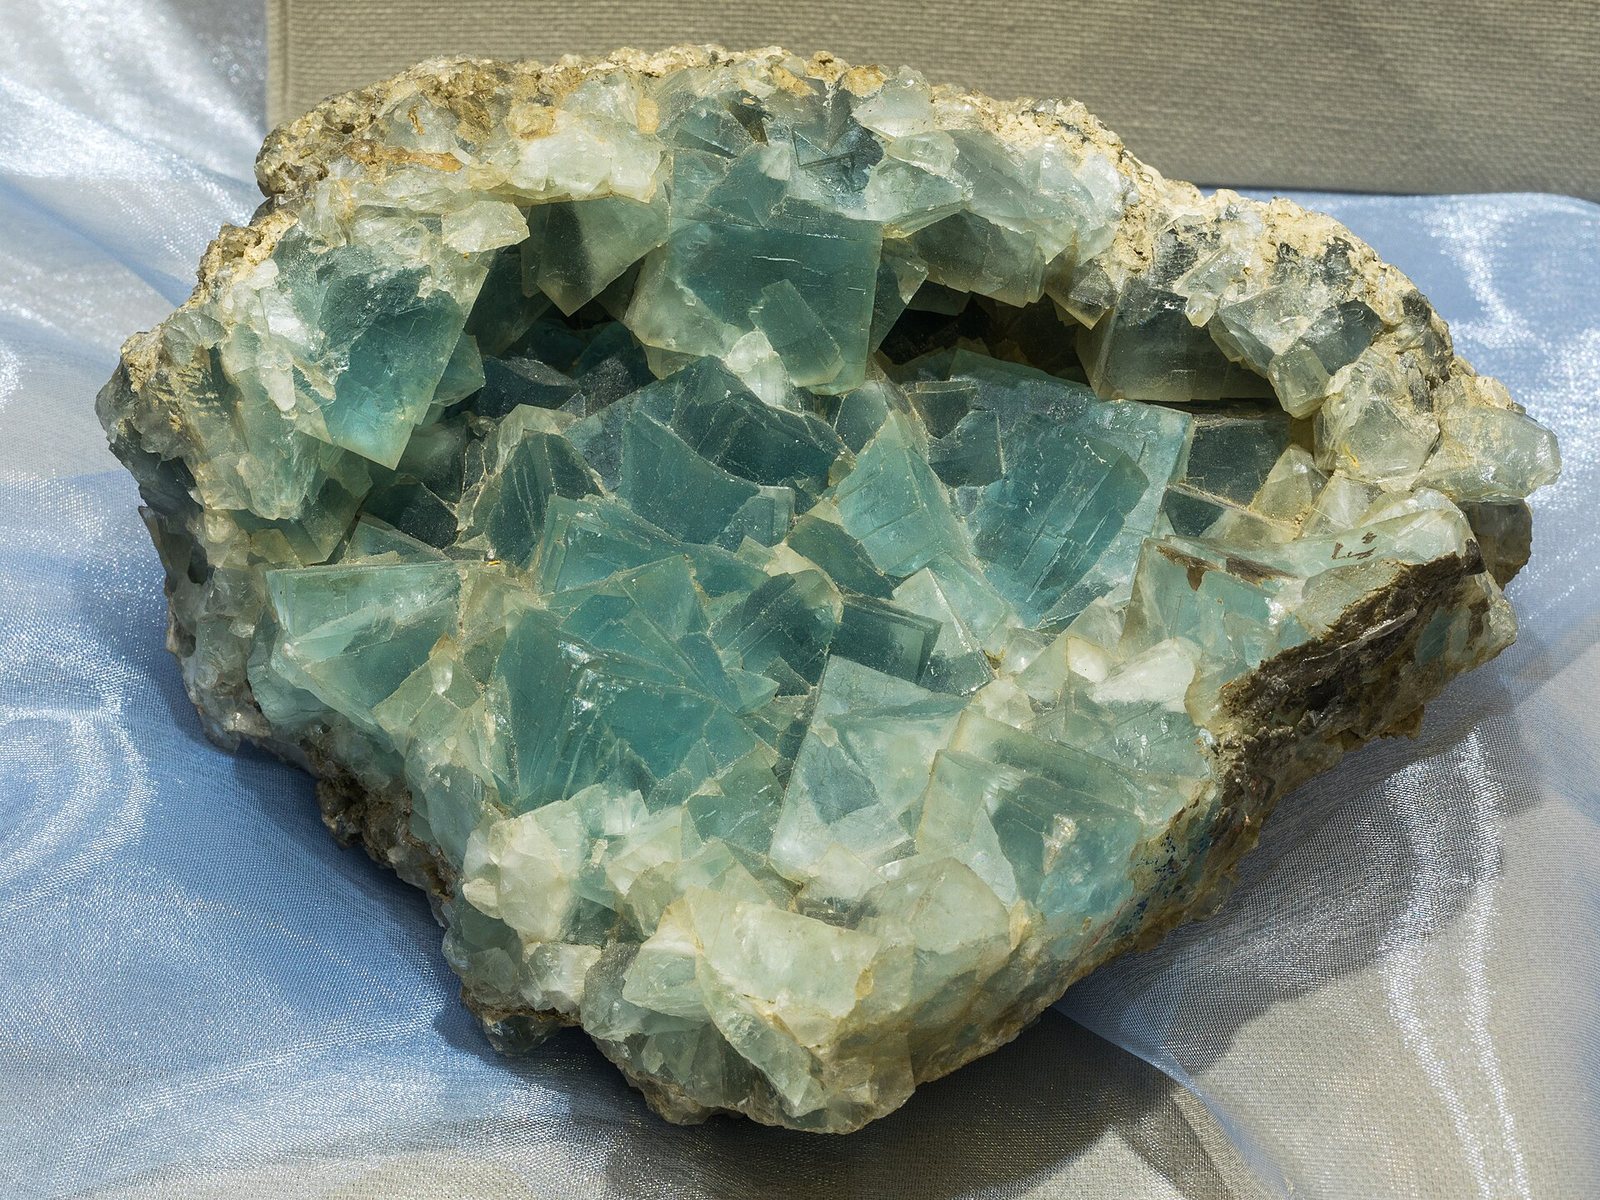
Fluorite — the mineral form of calcium fluoride — forms almost exclusively through hydrothermal processes. Hot, fluorine-bearing fluids, usually derived from the later stages of granite magmatism or from deeply circulating groundwater that has leached fluorine from surrounding rocks, migrate upward along faults and into porous limestone or dolomite beds. As the fluids cool and encounter carbonate rock, calcium and fluoride ions combine and precipitate out of solution, sometimes filling entire fault planes or replacing the host limestone wholesale. The first process produces what geologists call a vein deposit, typically a narrow but steeply dipping body of fluorite mixed with quartz and calcite gangue (the waste minerals that accompany the ore). The second produces a stratabound or manto deposit — a broadly flat, replacement body that can be far larger and easier to mine in bulk.
This distinction in deposit style matters because it controls both the grade of the ore and the type of mining that follows. Vein deposits tend to be high-grade and irregular, demanding selective mining. Manto deposits, such as those in Mexico's San Luis Potosí region, are lower-grade but geometrically predictable and amenable to large-scale extraction. South Africa's deposits, associated with the Bushveld Complex, are a different expression again, occurring in broadly flat, sedimentary layers interbedded with igneous rocks. Mongolia's Bor Undur district exploits large veins cutting Palaeozoic basement. The common thread in every case is an adequate source of fluorine, a plumbing system of fractures to carry it, and a chemically reactive carbonate host to fix it in place.
Fluorine is not rare in the Earth's crust — it is present in granites, in micas, in apatite, and in seawater — but it is rarely concentrated to ore grade. The association with carbonate terranes explains why the great fluorspar districts cluster along ancient continental margins and rift zones where limestone is abundant and where magmatic or tectonic heat drove fluid circulation over geologically long periods.
Getting it out
Most fluorspar is mined by open-pit methods where deposits are shallow, flat-lying, or weathered enough that the rock can be drilled and blasted economically from the surface. Underground mining is used where ore bodies are deep, narrow, or steeply dipping — as is common in classic vein districts. The choice between the two determines how much surrounding rock, called waste or overburden, must be moved for every tonne of ore recovered. Open-pit operations typically move considerably more total rock per tonne of product than underground mines do, but they allow larger machinery and lower labour costs per tonne, which often makes them cheaper overall where the geometry permits.
The grade of a fluorspar deposit is expressed as the percentage of calcium fluoride (CaF₂) in the run-of-mine ore — the material as it comes straight from the blast. Run-of-mine grades vary enormously between deposit types. A high-grade vein might deliver ore that is already close to marketable specification, while a manto or bedded deposit might yield ore that requires extensive processing before it approaches the purity that buyers expect. The two principal commercial grades — acid grade (at least 97% CaF₂) and metallurgical grade (broadly 60–85% CaF₂) — are not simply different names for different ores; they are different products destined for different industries and trading at materially different prices, as the import value data on this page shows.
Because fluorspar is almost always the principal product rather than a by-product of mining something else, the economics of a mine depend directly on the fluorite content of the ore and on how much of that fluorite can be recovered during processing. Dilution — the unavoidable mixing of ore with adjacent waste rock during blasting — reduces effective head grade and therefore increases the processing cost per tonne of saleable product. Managing dilution is a central operational concern, particularly in narrow underground veins.
What pulls on it
The starting point for understanding fluorspar demand is that the mineral is not itself an end product. It is a feedstock, and virtually all of the acid-grade material consumed worldwide is converted into hydrofluoric acid as a first step. From hydrofluoric acid, the fluorine atom is routed into an array of downstream products whose end markets are quite different from one another. Refrigerants — the hydrofluorocarbon and hydrofluoroolefin compounds used in air conditioning and refrigeration — account for a large share of hydrofluoric acid consumption. Aluminium smelting, which uses fluorspar directly as a flux in the cryolite bath of electrolytic reduction cells, represents the largest single use of metallurgical-grade material. Steelmakers also consume metallurgical-grade fluorspar as a slag conditioner. Uranium enrichment requires uranium hexafluoride, and the sole fluorinating agent that can produce it at scale is hydrofluoric acid derived from fluorspar.
The energy transition has added a new dimension to demand. Lithium-ion battery electrolytes use lithium hexafluorophosphate (LiPF₆) as the conducting salt, and its production requires hydrofluoric acid; the same is true of the polyvinylidene fluoride (PVDF) binders used in battery electrodes. As battery manufacturing capacity grows, the fluorine required for these applications grows with it. The significance of this is not merely that demand increases in aggregate, but that the downstream chemistry for battery materials requires acid-grade fluorspar of consistent purity — a different supply proposition from metallurgical-grade flux.
Demand could change sharply in either direction under a limited set of conditions. A large shift toward natural refrigerants — ammonia, carbon dioxide, hydrocarbons — in air conditioning and refrigeration would reduce one of the largest consumption streams. Conversely, a sustained acceleration in battery gigafactory construction would increase demand for the fluorine-intensive materials in electrolyte and electrode manufacturing. The relationship between these two vectors, and which moves faster, will determine the net direction of fluorspar demand over the coming decade, though this page does not forecast the outcome.
من أين يأتي في الصخر
جميع المعادن الخامة →هذه هي المعادن التي تحمل فعلياً fluorspar. لا يُعدّ الرسوب خاماً إلا إذا كان تركيز أحد معادنه كافياً لتغطية تكاليف استخراجه.
من ينتجه
اعرضه على خريطة →Mine production
Mine productionthousand metric tons 2025 (مُقدَّر) المجموع العالمي 10,000 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of all grades; acid grade and metallurgical grade are different markets. · المصدر ↗
مرِّر الجدول أفقياً لعرض الأعمدة المتبقية.
| الدولة | الإنتاج | حصة من العالم |
|---|---|---|
| China | 6,000 | 60.0% |
| Mongolia | 1,500 | 15.0% |
| Mexico | 1,500 | 15.0% |
| South Africa | 410.0 | 4.1% |
| Other countries | 200.0 | 2.0% |
| Vietnam | 160.0 | 1.6% |
| Spain | 140.0 | 1.4% |
| Brazil | 100.0 | 1.0% |
| Iran | 70.00 | 0.7% |
| Thailand | 55.00 | 0.6% |
| Pakistan | 50.00 | 0.5% |
| Germany | 35.00 | 0.3% |
| Tajikistan | 15.00 | 0.1% |
| United States | Not applicable | — |
| المجموع العالمي | 10,000 | 100% |
«محجوب» يعني أن USGS أخفى الرقم تفاديًا للإفصاح عن بيانات شركة بعينها — وهو لا يعني صفرًا. لا يُساوي مجموع صفوف الدول دائمًا المجموع العالمي لأن المصدر يُقرِّب كل رقم باستقلالية ولا يُفصِّل دائمًا خانة «دول أخرى».
من يحتفظ بالاحتياطيات
Reserves
Reservesthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · المصدر ↗
| الدولة | الاحتياطيات | حصة من العالم |
|---|---|---|
| China | 110,000 | 33.3% |
| Mexico | 68,000 | 20.6% |
| South Africa | 41,000 | 12.4% |
| Mongolia | 34,000 | 10.3% |
| Other countries | 32,000 | 9.7% |
| Vietnam | 16,000 | 4.8% |
| Spain | 15,000 | 4.5% |
| Iran | 7,600 | 2.3% |
| Thailand | 3,600 | 1.1% |
| Brazil | 2,500 | 0.8% |
| United States | Not applicable | — |
| Germany | Not applicable | — |
| Pakistan | Not applicable | — |
| Tajikistan | Not applicable | — |
| المجموع العالمي | 330,000 | 100% |
السعر
average unit value of imports, cost, insurance, and freight, dollars per metric ton: Metallurgical grade
المتوسط السنويdollars per metric ton
الأساس: average unit value of imports, cost, insurance, and freight, dollars per metric ton: Metallurgical grade. متوسطات سنوية كما نُشرت في USGS Mineral Commodity Summaries 2026 · المصدر ↗. هذه متوسطات سنوية مرجعية، وليست أسعار سوق آنية.
average unit value of imports, cost, insurance, and freight, dollars per metric ton: Acid grade
المتوسط السنويdollars per metric ton
الأساس: average unit value of imports, cost, insurance, and freight, dollars per metric ton: Acid grade. متوسطات سنوية كما نُشرت في USGS Mineral Commodity Summaries 2026 · المصدر ↗. هذه متوسطات سنوية مرجعية، وليست أسعار سوق آنية.
أين تتم معالجته وتكريره
| المنشأة | النوع | المرحلة | الدولة | الدور |
|---|---|---|---|---|
| Port Hope Conversion Facility | منشأة كيميائية | التكرير | Canada | المدخل |
ما الذي يُستخدم فيه
جميع الأسواق النهائية →| السوق النهائية | ما الذي يؤديه هناك | الأهمية |
|---|---|---|
| Nuclear Power | Fluorine for uranium hexafluoride | مهم |