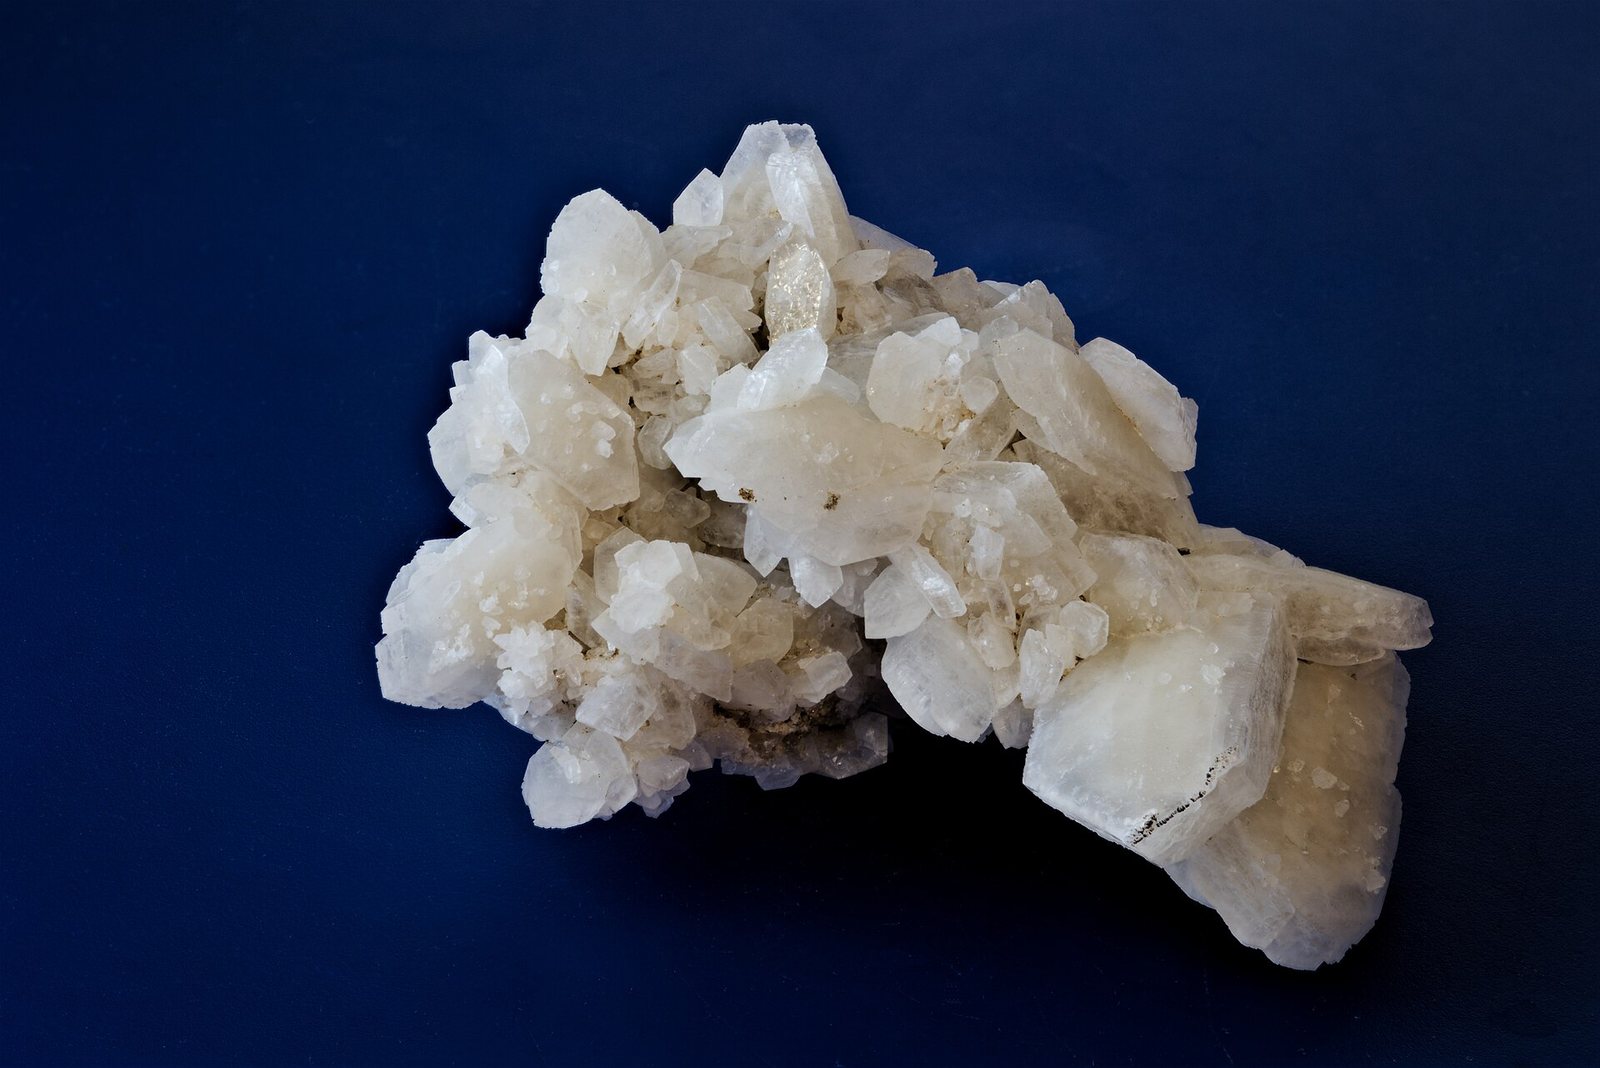
ما هو؟
A soft white rock that becomes plasterboard — the interior surface of most buildings in the developed world.
لماذا يهم هذا؟
A large share of gypsum supply is synthetic, captured from coal-plant flue gas. Closing coal plants removes that supply.
Where it is in the Earth
Gypsum is calcium sulfate dihydrate — a calcium sulfate molecule with two water molecules chemically bound into its crystal structure. It forms almost exclusively in evaporite sequences: ancient shallow seas or landlocked basins that dried out slowly, concentrating dissolved salts until minerals began to crystallise out of the brine. Gypsum is typically one of the first minerals to precipitate in this sequence, appearing before halite (common salt) because it becomes insoluble at lower concentrations. The result is thick, laterally extensive beds of white or grey rock interlayered with limestone, shale and anhydrite — anhydrite being the anhydrous form of calcium sulfate, which forms when gypsum loses its bound water under heat or pressure.
Because evaporite basins accumulated during many different geological periods, gypsum deposits are found on every continent. The large reserves in China, Thailand, Iran and North America reflect ancient seaways that covered those regions hundreds of millions of years ago. In some areas, such as parts of Spain and the American Southwest, the beds sit close to the surface and were exposed by later erosion, making them straightforward to mine. In others the rock lies beneath younger sediments, requiring deeper workings. Importantly, gypsum is also produced chemically at industrial scale as a by-product of scrubbing sulfur dioxide from coal-fired power station flue gas — a process called flue-gas desulfurisation, or FGD. This synthetic gypsum is chemically equivalent to the mined mineral and now accounts for a substantial share of total supply in countries with large coal fleets and environmental controls, particularly Germany, Japan and the United States.
Getting it out
The great majority of natural gypsum is extracted by open-pit quarrying. The rock is soft enough — it scores just 2 on the Mohs hardness scale, meaning a fingernail can scratch it — that drilling and blasting are often sufficient, and in some deposits mechanical rippers attached to bulldozers can break the rock without explosives at all. The soft, massive beds also mean that waste-to-ore ratios are generally modest compared with hard-rock metallic mining; overburden (the rock and soil that must be removed to reach the deposit) is stripped and stockpiled, but the gypsum beds themselves are thick and relatively pure, so a high proportion of what is dug becomes saleable product.
Underground mining is used where deposits sit beneath towns, sensitive land or other minerals that must be preserved, or where the depth makes surface working uneconomical. Room-and-pillar methods are common: miners extract rectangular panels of rock and leave regular pillars standing to support the roof, producing a grid-like void. Because gypsum is weak, pillar design is important, and mine layouts tend to be conservative. A small quantity of gypsum is also recovered as a by-product of phosphoric acid production, where sulfuric acid reacts with phosphate rock and generates a calcium sulfate residue called phosphogypsum. Most phosphogypsum contains low levels of naturally occurring radioactive materials and is stockpiled rather than used, though some countries do use it in agriculture and construction.
Grade, in the context of gypsum, is expressed as purity — the percentage of calcium sulfate dihydrate in the run-of-mine rock. High-purity deposits are preferred for plasterboard manufacture, where consistency matters. Rock that is intimately mixed with limestone or clay requires more processing to reach specification and may command a lower price or be relegated to agricultural uses where purity requirements are looser.
What pulls on it
Gypsum's dominant end use is the manufacture of plasterboard — the flat panels of set gypsum sandwiched between paper sheets that line the interior walls and ceilings of most buildings in the developed world. Demand therefore tracks construction activity very closely, with residential building particularly important because new homes are fitted out with plasterboard at a consistent rate per square metre of floor area. When housing construction slows, gypsum demand falls; when it recovers, demand recovers with it. This makes gypsum one of the more cyclically sensitive industrial minerals, even though the underlying geology suggests essentially unlimited long-run supply.
Beyond plasterboard, gypsum has a secondary role as a soil amendment in agriculture: it supplies calcium and sulfur to crops without significantly altering soil pH, and it is used to break up heavy clay soils. Cement production uses a small quantity of gypsum as a set retarder — added at the grinding stage, it controls how quickly concrete hardens. These applications are smaller but more stable than construction demand, and they absorb some gypsum that is too impure or too finely ground for wallboard specification.
The structural shift worth understanding is the relationship between FGD gypsum supply and coal-fired power generation. In countries where coal plants are being retired for reasons of climate policy or economics, the flow of synthetic gypsum diminishes. Wallboard manufacturers that built their supply chains around cheap, locally produced FGD material must then either source natural gypsum — often from greater distances — or import wallboard itself. This is not a demand change but a supply displacement that has real consequences for regional market balance. Equally, in countries that are still building coal capacity with sulfur controls, FGD gypsum supply is growing, and that growth can displace natural quarrying.
Turning ore into product المستوى 3
Run-of-mine gypsum is crushed and screened to remove coarse impurities. Depending on end use, the rock may be sold as crude lump or ground to a fine powder. The decisive processing step for most applications is calcination: heating the crushed rock to drive off part of the chemically bound water, converting calcium sulfate dihydrate to calcium sulfate hemihydrate, the substance known commercially as stucco or plaster of Paris. The calcination temperature is held carefully — too high and the product loses too much water, forming anhydrite, which rehydrates too slowly to be useful in wallboard; too low and conversion is incomplete. Kettle calciners and rotary kilns are both used, each producing hemihydrate with slightly different particle characteristics that affect the working time and final strength of the set plaster.
The price tables on this page illustrate what calcination adds to value: crude gypsum at the mine gate is priced in low single-digit to low double-digit dollars per metric tonne, while calcined material leaving the plant commands several times that. The processing step is therefore where much of the commercial value is created. For wallboard manufacture, the calcined stucco is mixed with water, additives and a paper or glass-fibre facing, cast as a continuous slab between two facing sheets, and then passed through a drying kiln to set and dry. Synthetic FGD gypsum feeds directly into this process, typically requiring less crushing but sometimes more drying because it is produced wet. Blending natural and synthetic material is routine in wallboard plants that have access to both sources.
Losses in the system are low by the standards of metallurgical processing: gypsum is not concentrated from a low-grade matrix, so there is no equivalent of mineral flotation tailings. The main losses are fines generated during crushing and handling, and kiln dust captured in bag filters — both of which are usually recycled back into the process or sold for agricultural use. The unit-basis for all production figures in the table is crude gypsum at gross weight, meaning synthetic and natural material are counted on the same footing, which simplifies aggregation but can obscure changes in the source mix within a country's reported total.
Substitution and recycling المستوى 3
For plasterboard, no material fully replicates gypsum's combination of properties at comparable cost. The mineral's chemistry is the reason: when hemihydrate rehydrates it sets rigid, releases no harmful by-products, bonds reliably to paper and fibreglass facing, and provides useful fire resistance because the bound water in the dihydrate crystal must be driven off before the panel can combust. Alternatives such as fibre-cement board, magnesium oxide board and calcium silicate board exist and are used in specific applications — high-humidity environments, exterior cladding — but they are considerably more expensive per unit of covered area, and their manufacturing processes are more energy-intensive. In most interior drylining applications, they are not economically competitive with gypsum wallboard.
Recycling of gypsum is technically straightforward. Demolished plasterboard can be crushed, the paper facing separated, and the gypsum powder calcined and reused. The material cycles well and does not degrade chemically through the process. The constraint is logistical: plasterboard waste arises from construction and demolition sites that are geographically dispersed, the panels are bulky and low in value by weight, and collection and transport costs frequently exceed the value of the recovered material. In markets where landfill costs are high or where regulation restricts gypsum from landfill — as is the case in parts of Europe, where decomposing gypsum in anaerobic landfill can generate hydrogen sulfide — recycling rates are meaningfully higher than elsewhere, because the economics shift in favour of collection. The practical ceiling on recycling is set by the availability of demolition arisings relative to total demand: even in well-organised systems, recycled material supplements rather than replaces primary supply.
Where the chain is fragile المستوى 4
Gypsum's geological abundance means that long-run physical scarcity is not a credible risk. Reported reserves in the table dwarf current production rates by factors of hundreds to thousands of years at present consumption. The more genuine fragilities are structural and regional. The most discussed is the FGD supply question: a significant fraction of world supply — and a particularly large fraction in Germany, Japan and the United States — originates as a by-product of flue-gas desulfurisation at coal-fired power stations. Reporting conventions count this material identically to mined gypsum in aggregate production statistics, so the headline world production figure gives no indication of how the source mix is shifting. As coal retirements accelerate in some jurisdictions, FGD output falls, and the burden falls on natural quarrying or imports to fill the gap. The lead time to permit, develop and commission a new quarry is typically measured in years, so the adjustment is not instantaneous.
Concentration risk at the country level is modest for natural gypsum — the reserve base is distributed across many nations and the mineral is mined on every inhabited continent — but regional market structures can still be tight. Gypsum and wallboard are heavy and low in value per tonne, which means they are rarely shipped long distances; most trade is regional rather than global. A disruption to supply in one region therefore cannot easily be offset by exports from another, and price responses are localised rather than globalised. This is a structural feature that published world-price series, which typically reflect the dominant trading region, do not fully capture.
A further uncertainty in published data is the treatment of phosphogypsum. Very large quantities accumulate at phosphoric acid plants worldwide, mostly in uncounted stockpiles. The portion that enters commerce is recorded; the rest is not. Any significant change in the regulatory environment that either permitted or restricted the use of phosphogypsum would alter apparent supply statistics without changing geological endowment, creating discontinuities in time-series comparisons. Analysts working with historical production data should be aware that changes in what is counted as usable supply — driven by environmental classification rather than physical availability — can make trend lines misleading.
من ينتجه
اعرضه على خريطة →Mine production
Mine productionthousand metric tons 2025 (مُقدَّر) المجموع العالمي 160,000 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Crude gypsum, gross weight. · المصدر ↗
مرِّر الجدول أفقياً لعرض الأعمدة المتبقية.
| الدولة | الإنتاج | حصة من العالم |
|---|---|---|
| United States | 20,000 | 12.5% |
| Other countries | 20,000 | 12.5% |
| Iran | 16,000 | 10.0% |
| Oman | 14,000 | 8.8% |
| China | 12,000 | 7.5% |
| Spain | 11,000 | 6.9% |
| Turkey | 10,000 | 6.2% |
| Thailand | 8,700 | 5.4% |
| Brazil | 5,800 | 3.6% |
| Mexico | 5,400 | 3.4% |
| Germany | 4,700 | 2.9% |
| Japan | 4,300 | 2.7% |
| India | 4,300 | 2.7% |
| Russia | 4,300 | 2.7% |
| Australia | 4,200 | 2.6% |
| Saudi Arabia | 3,800 | 2.4% |
| Canada | 3,600 | 2.2% |
| Algeria | 2,500 | 1.6% |
| Uzbekistan | 2,500 | 1.6% |
| France | 2,400 | 1.5% |
| المجموع العالمي | 160,000 | 100% |
«محجوب» يعني أن USGS أخفى الرقم تفاديًا للإفصاح عن بيانات شركة بعينها — وهو لا يعني صفرًا. لا يُساوي مجموع صفوف الدول دائمًا المجموع العالمي لأن المصدر يُقرِّب كل رقم باستقلالية ولا يُفصِّل دائمًا خانة «دول أخرى».
من يحتفظ بالاحتياطيات
Reserves
Reservesthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · المصدر ↗
| الدولة | الاحتياطيات | حصة من العالم |
|---|---|---|
| China | 1,800,000 | — |
| Thailand | 910,000 | — |
| Iran | 750,000 | — |
| United States | 700,000 | — |
| Canada | 450,000 | — |
| Brazil | 450,000 | — |
| France | 300,000 | — |
| Turkey | 200,000 | — |
| India | 37,000 | — |
| Uzbekistan | Not applicable | — |
| Other countries | Not applicable | — |
| Japan | Not applicable | — |
| Algeria | Not applicable | — |
| Australia | Not applicable | — |
| Germany | Not applicable | — |
| Mexico | Not applicable | — |
| Oman | Not applicable | — |
| Russia | Not applicable | — |
| Saudi Arabia | Not applicable | — |
| Spain | Not applicable | — |
| المجموع العالمي | Large | 100% |
السعر
annual average, dollars per metric ton: Crude, free on board (f.o.b.) mine
المتوسط السنويdollars per metric ton
الأساس: annual average, dollars per metric ton: Crude, free on board (f.o.b.) mine. متوسطات سنوية كما نُشرت في USGS Mineral Commodity Summaries 2026 · المصدر ↗. هذه متوسطات سنوية مرجعية، وليست أسعار سوق آنية.
annual average, dollars per metric ton: Calcined, f.o.b. plant
المتوسط السنويdollars per metric ton
الأساس: annual average, dollars per metric ton: Calcined, f.o.b. plant. متوسطات سنوية كما نُشرت في USGS Mineral Commodity Summaries 2026 · المصدر ↗. هذه متوسطات سنوية مرجعية، وليست أسعار سوق آنية.
ما الذي يُستخدم فيه
جميع الأسواق النهائية →| السوق النهائية | ما الذي يؤديه هناك | الأهمية |
|---|---|---|
| Construction & Steel | Plasterboard | مهم |
ضوابط التصدير
| الدولة | سيطرة | ينطبق على |
|---|---|---|
| Angola | Export ban | Quartz and gypsum (2024). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.