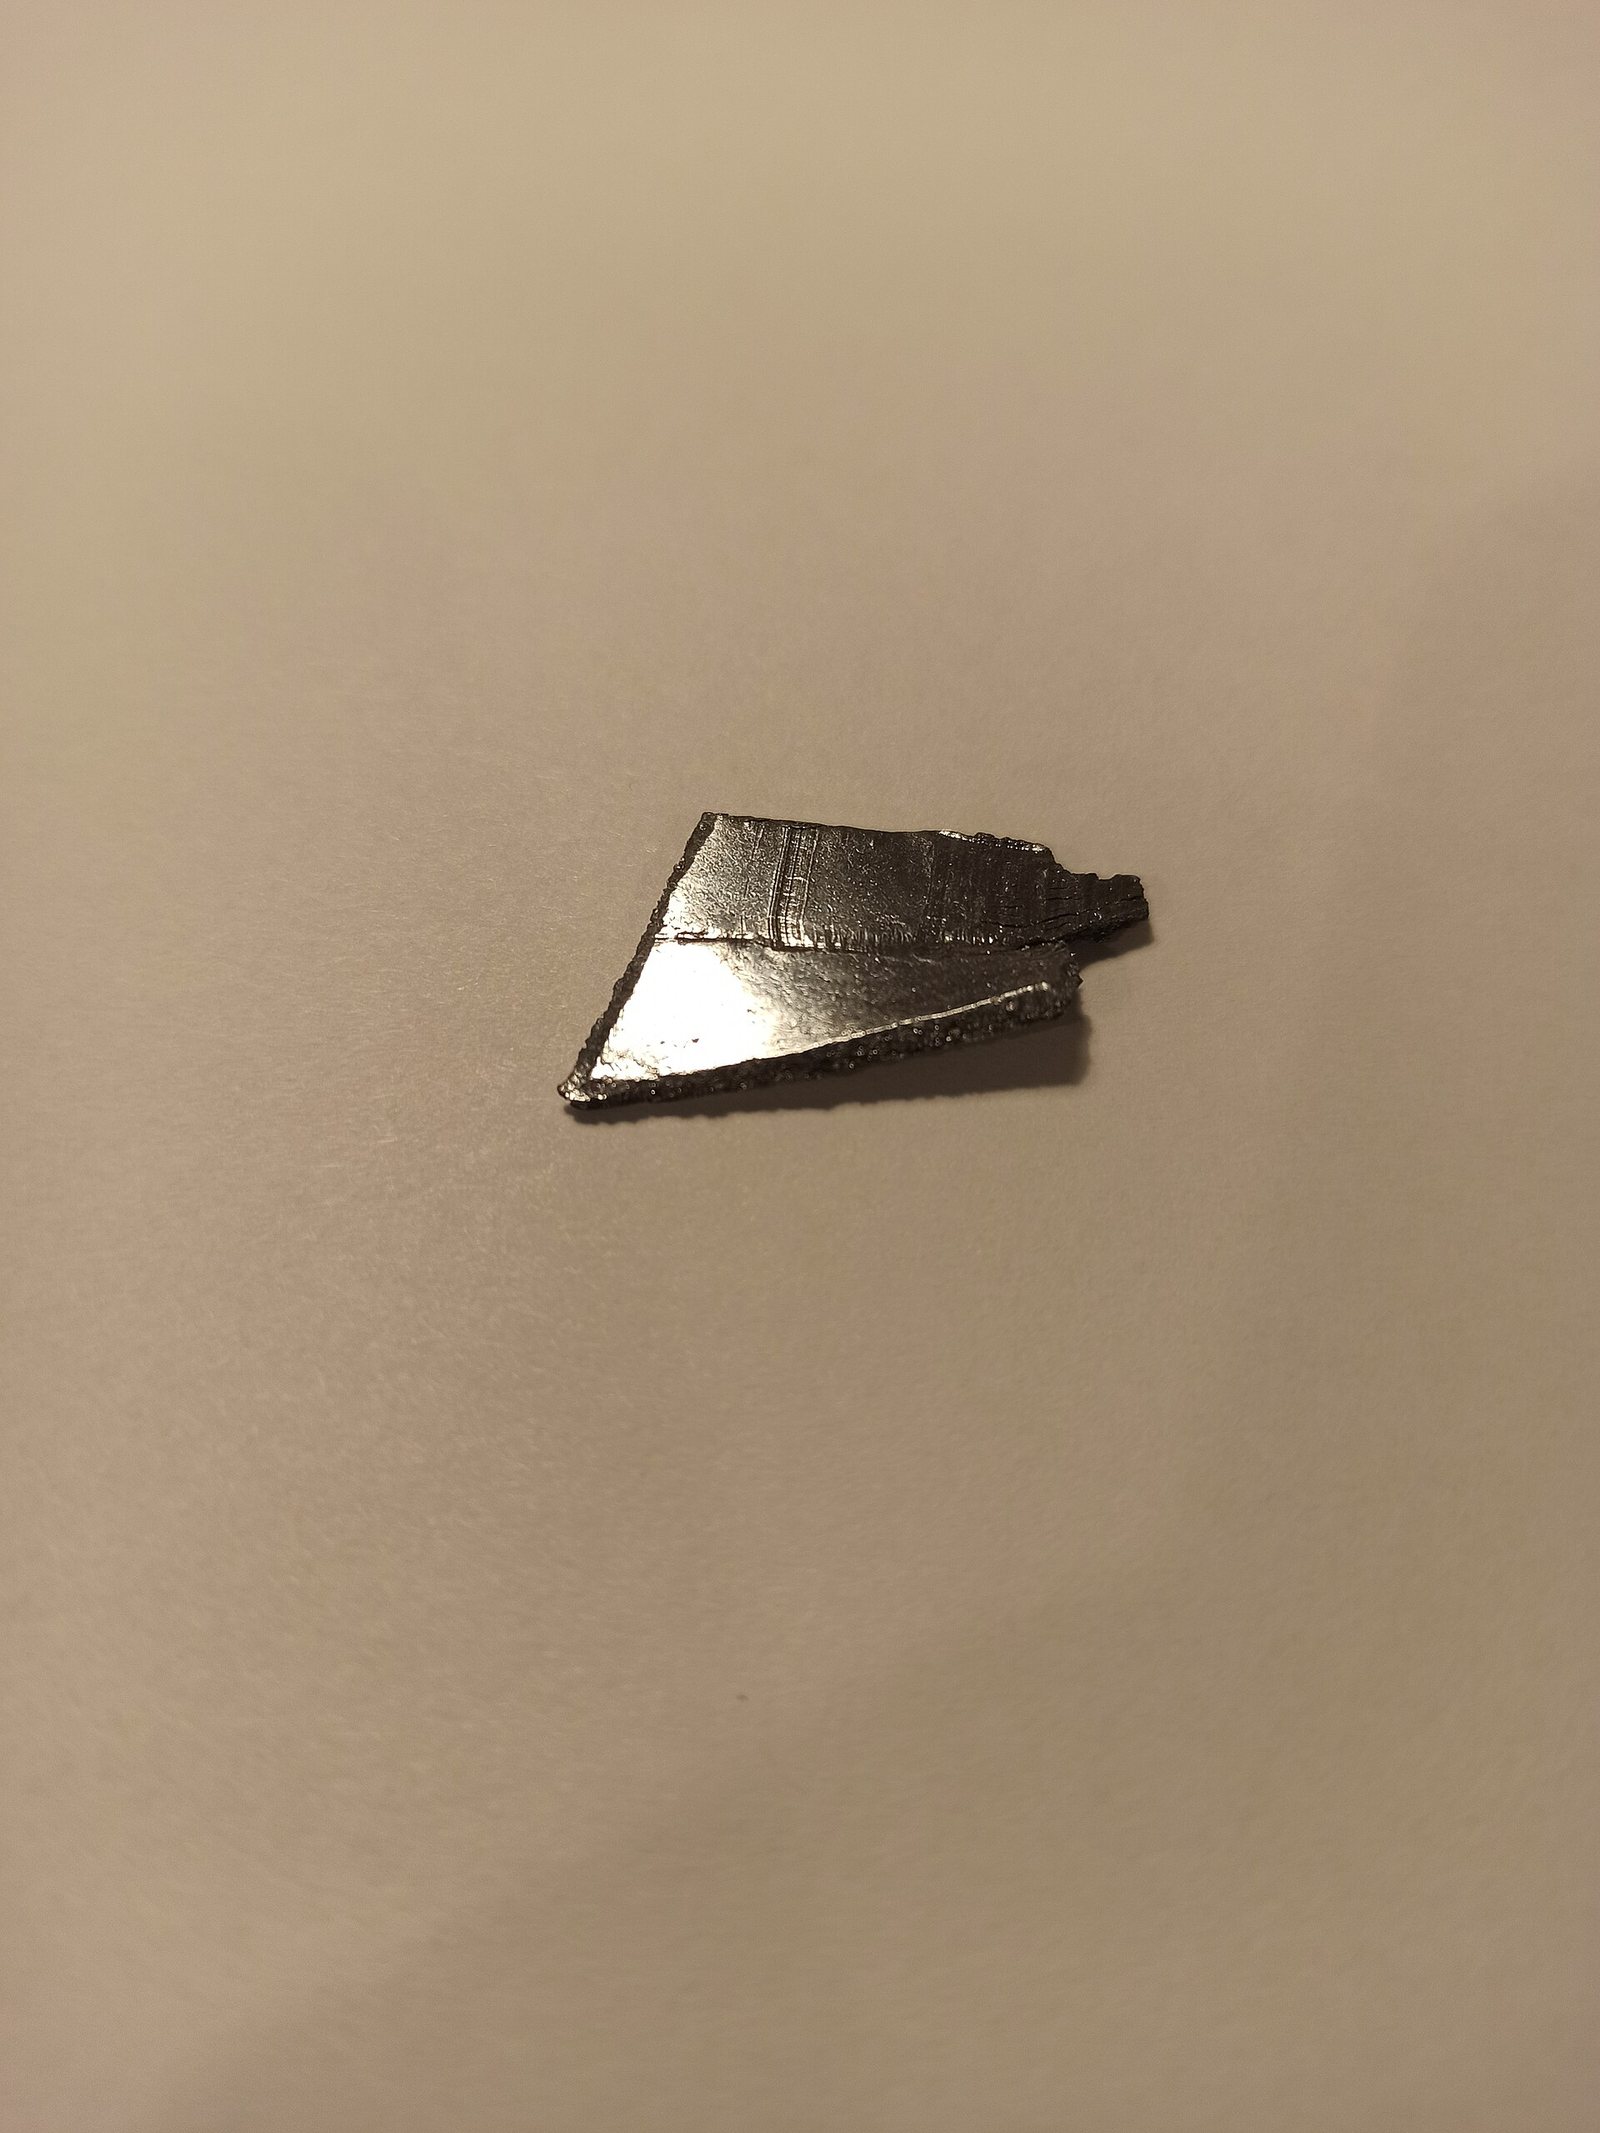
이것은 무엇인가?
One of the rarest metals in the crust, recovered from molybdenum roasting, and the ingredient that lets a jet turbine blade run hotter.
왜 중요한가?
Second- and third-generation single-crystal superalloys contain 3-6% rhenium. Engine efficiency is directly tied to that temperature margin.
Where it is in the Earth
Rhenium is one of the rarest elements in the Earth's crust, and it does not form ore minerals of its own in any commercially meaningful sense. Instead, it occurs in trace amounts within molybdenite (molybdenum disulfide, MoS₂), the principal ore mineral of molybdenum. Molybdenite has a layered crystal structure that can accommodate rhenium atoms substituting for molybdenum, so wherever molybdenite forms in quantity, a small but recoverable fraction of rhenium comes along with it. The concentrations involved are extraordinarily low — far below what would register as a grade in any conventional mining context — yet because molybdenite itself is mined in large volumes, the absolute quantities of rhenium that pass through the system become economically meaningful.
The deposits that carry most of the world's rhenium are porphyry copper-molybdenum systems: large, low-grade bodies of mineralisation formed when metal-rich fluids expelled from cooling granite intrusions percolated outward into the surrounding rock and deposited sulphide minerals over immense volumes. The word porphyry refers to the texture of the host rock, which contains large crystals set in a finer-grained matrix. These systems are geologically young by crustal standards and tend to cluster along continental arcs — the chains of volcanoes thrown up where one tectonic plate dives beneath another. Chile's position along the Andean arc places it above one of the most productive belts of porphyry mineralisation on Earth, which is why Chile holds both the largest reserves and the largest annual output of rhenium. The same arc-related geology recurs in Central Asia, the western United States, and parts of East Asia, explaining the geographic spread of producing countries shown in the table above.
Because rhenium is bound inside molybdenite at the atomic level rather than occurring as a separate mineral phase, it cannot be concentrated by any process that targets rhenium specifically. Its geography is entirely inherited from the geography of molybdenum, and ultimately from the distribution of porphyry copper systems around the world's subduction zones.
Getting it out
Rhenium is never the reason a mine exists. It arrives entirely as a by-product — a secondary recovery from operations whose economics are driven first by copper and, to a lesser degree, by molybdenum. The large porphyry deposits that host it are almost always worked by open-pit mining, a method suited to low-grade, high-volume ore bodies where the mineralisation is too dispersed and too near the surface to justify the cost and complexity of underground workings. In open-pit mining, rock is drilled, blasted, and removed in a descending series of benches, with the ore trucked to a processing plant and the waste rock stacked separately. The ratio of waste to ore moved — the strip ratio — can be high in these operations, meaning that very large quantities of material must be shifted to access each tonne of copper-bearing rock.
The rhenium content of the ore is not a figure that drives any mining decision. Operators measure it, because it determines what they will recover downstream, but the mine plan is set around the copper and molybdenum grades. For a reader trying to understand what the production figures in the table mean in practice, the key point is that rhenium output from any country is essentially a function of how much molybdenite concentrate that country's copper mines are producing in a given year, not of any deliberate choice to produce rhenium. When copper demand falls and mines curtail output or reduce throughput, rhenium supply falls with it, regardless of what the rhenium market is doing.
What pulls on it
The dominant use of rhenium is in the single-crystal nickel superalloys from which the high-pressure turbine blades of jet engines are made. To understand why rhenium matters here, it helps to know what a single-crystal superalloy is. Conventional metal alloys are made up of many small crystalline grains bonded together; at very high temperatures, those grain boundaries weaken and allow the material to creep and deform. Engineers in the mid-twentieth century learned to cast turbine blades as a single uninterrupted crystal, eliminating grain boundaries entirely and dramatically extending the temperature at which the blade remains mechanically sound. Rhenium, added at concentrations of a few percent, further stabilises the crystal structure at extreme temperatures by slowing the diffusion of atoms through the alloy — a phenomenon called creep resistance. Higher operating temperatures mean more efficient combustion and lower fuel consumption for a given thrust, which is why engine manufacturers have strong incentive to use rhenium-bearing alloys in the hottest parts of their turbines.
The civil aviation industry is the largest single source of demand, followed by military aviation and industrial gas turbines used in power generation. Demand in these sectors tracks the production rate of new engines rather than the size of the existing fleet, because rhenium is consumed when an engine is built or its hot-section components are replaced. When new commercial aircraft orders are strong and engine manufacturers are running at high rates, rhenium demand rises accordingly. A prolonged reduction in new aircraft deliveries — whether from an economic downturn, a supply-chain disruption, or a shift in airline ordering — would reduce rhenium consumption materially, because there is no other use of comparable scale to absorb the difference.
Rhenium also appears in reforming catalysts used in petroleum refining to improve the octane rating of gasoline, and in smaller quantities in thermocouples, electrical contacts, and laboratory instruments that exploit its exceptional melting point. However, the superalloy application dwarfs all others, and the trajectory of demand is largely a story about commercial aerospace build rates and the continued preference of engine designers for rhenium-bearing alloy generations over alternatives.
생산 주체
지도에서 보기 →Mine production
Mine productionkilograms 2025 (추정치) 세계 합계 81,000 kilograms
USGS Mineral Commodity Summaries 2026 · Reported in kilograms, not tonnes — annual world output is measured in tens of tonnes. · 출처 ↗
나머지 열을 보려면 표를 옆으로 스크롤하십시오.
| 국가 | 생산 | 세계 비중 |
|---|---|---|
| Chile | 30,000 | 37.0% |
| China | 20,000 | 24.7% |
| Poland | 10,000 | 12.3% |
| United States | 9,800 | 12.1% |
| Uzbekistan | 7,000 | 8.6% |
| Korea, Republic of | 3,000 | 3.7% |
| Kazakhstan | 1,000 | 1.2% |
| Armenia | 200.0 | 0.2% |
| Russia | Not applicable | — |
| 세계 합계 | 81,000 | 100% |
'비공개'는 USGS가 개별 기업의 데이터 노출을 막기 위해 수치를 억제한 것으로, 0을 의미하지 않습니다. 출처가 각 수치를 독립적으로 반올림하고 '기타 국가' 항목을 항상 별도로 구분하지는 않기 때문에, 국가별 합계가 세계 합계와 일치하지 않을 수 있습니다.
매장량 보유 주체
Reserves
Reserveskilograms 2025
USGS Mineral Commodity Summaries 2026 · 출처 ↗
| 국가 | 매장량 | 세계 비중 |
|---|---|---|
| Chile | 1,300,000 | — |
| United States | 400,000 | — |
| Russia | 310,000 | — |
| China | 200,000 | — |
| Kazakhstan | 190,000 | — |
| Armenia | 95,000 | — |
| Korea, Republic of | Not applicable | — |
| Poland | Not applicable | — |
| Uzbekistan | Not applicable | — |
| 세계 합계 | Large | 100% |
가격
average value, gross weight, dollars per kilogram: Metal, 99.99% pure
연간 평균dollars per kilogram
기준: average value, gross weight, dollars per kilogram: Metal, 99.99% pure. 다음 자료에 게재된 연간 평균 USGS Mineral Commodity Summaries 2026 · 출처 ↗. 이 수치는 기준 연간 평균값이며, 실시간 시장 가격이 아니다.
average value, gross weight, dollars per kilogram: Ammonium perrhenate
연간 평균dollars per kilogram
기준: average value, gross weight, dollars per kilogram: Ammonium perrhenate. 다음 자료에 게재된 연간 평균 USGS Mineral Commodity Summaries 2026 · 출처 ↗. 이 수치는 기준 연간 평균값이며, 실시간 시장 가격이 아니다.
처리·정련 지점
| 시설 | 종류 | 단계 | 국가 | 역할 |
|---|---|---|---|---|
| Aero-Engine Turbine Plant, Derby | 제조 플랜트 | 제품 | United Kingdom | 투입물 |
용도
전체 최종 시장 →| 최종 시장 | 거기에서의 기능 | 중요도 |
|---|---|---|
| Aerospace & Defence | Single-crystal superalloy | 정의 |
기술별 소요량
| 기술 | 수량 | 고시 가격 | 기준 |
|---|---|---|---|
| Single-Crystal Turbine Blade A few percent of a metal produced in tens of tonnes a year worldwide. | 미량 | per blade set | 3-6% of second and third generation superalloys |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. 재료 계산기에서 임의의 규모로 이 수치를 계산하십시오. →