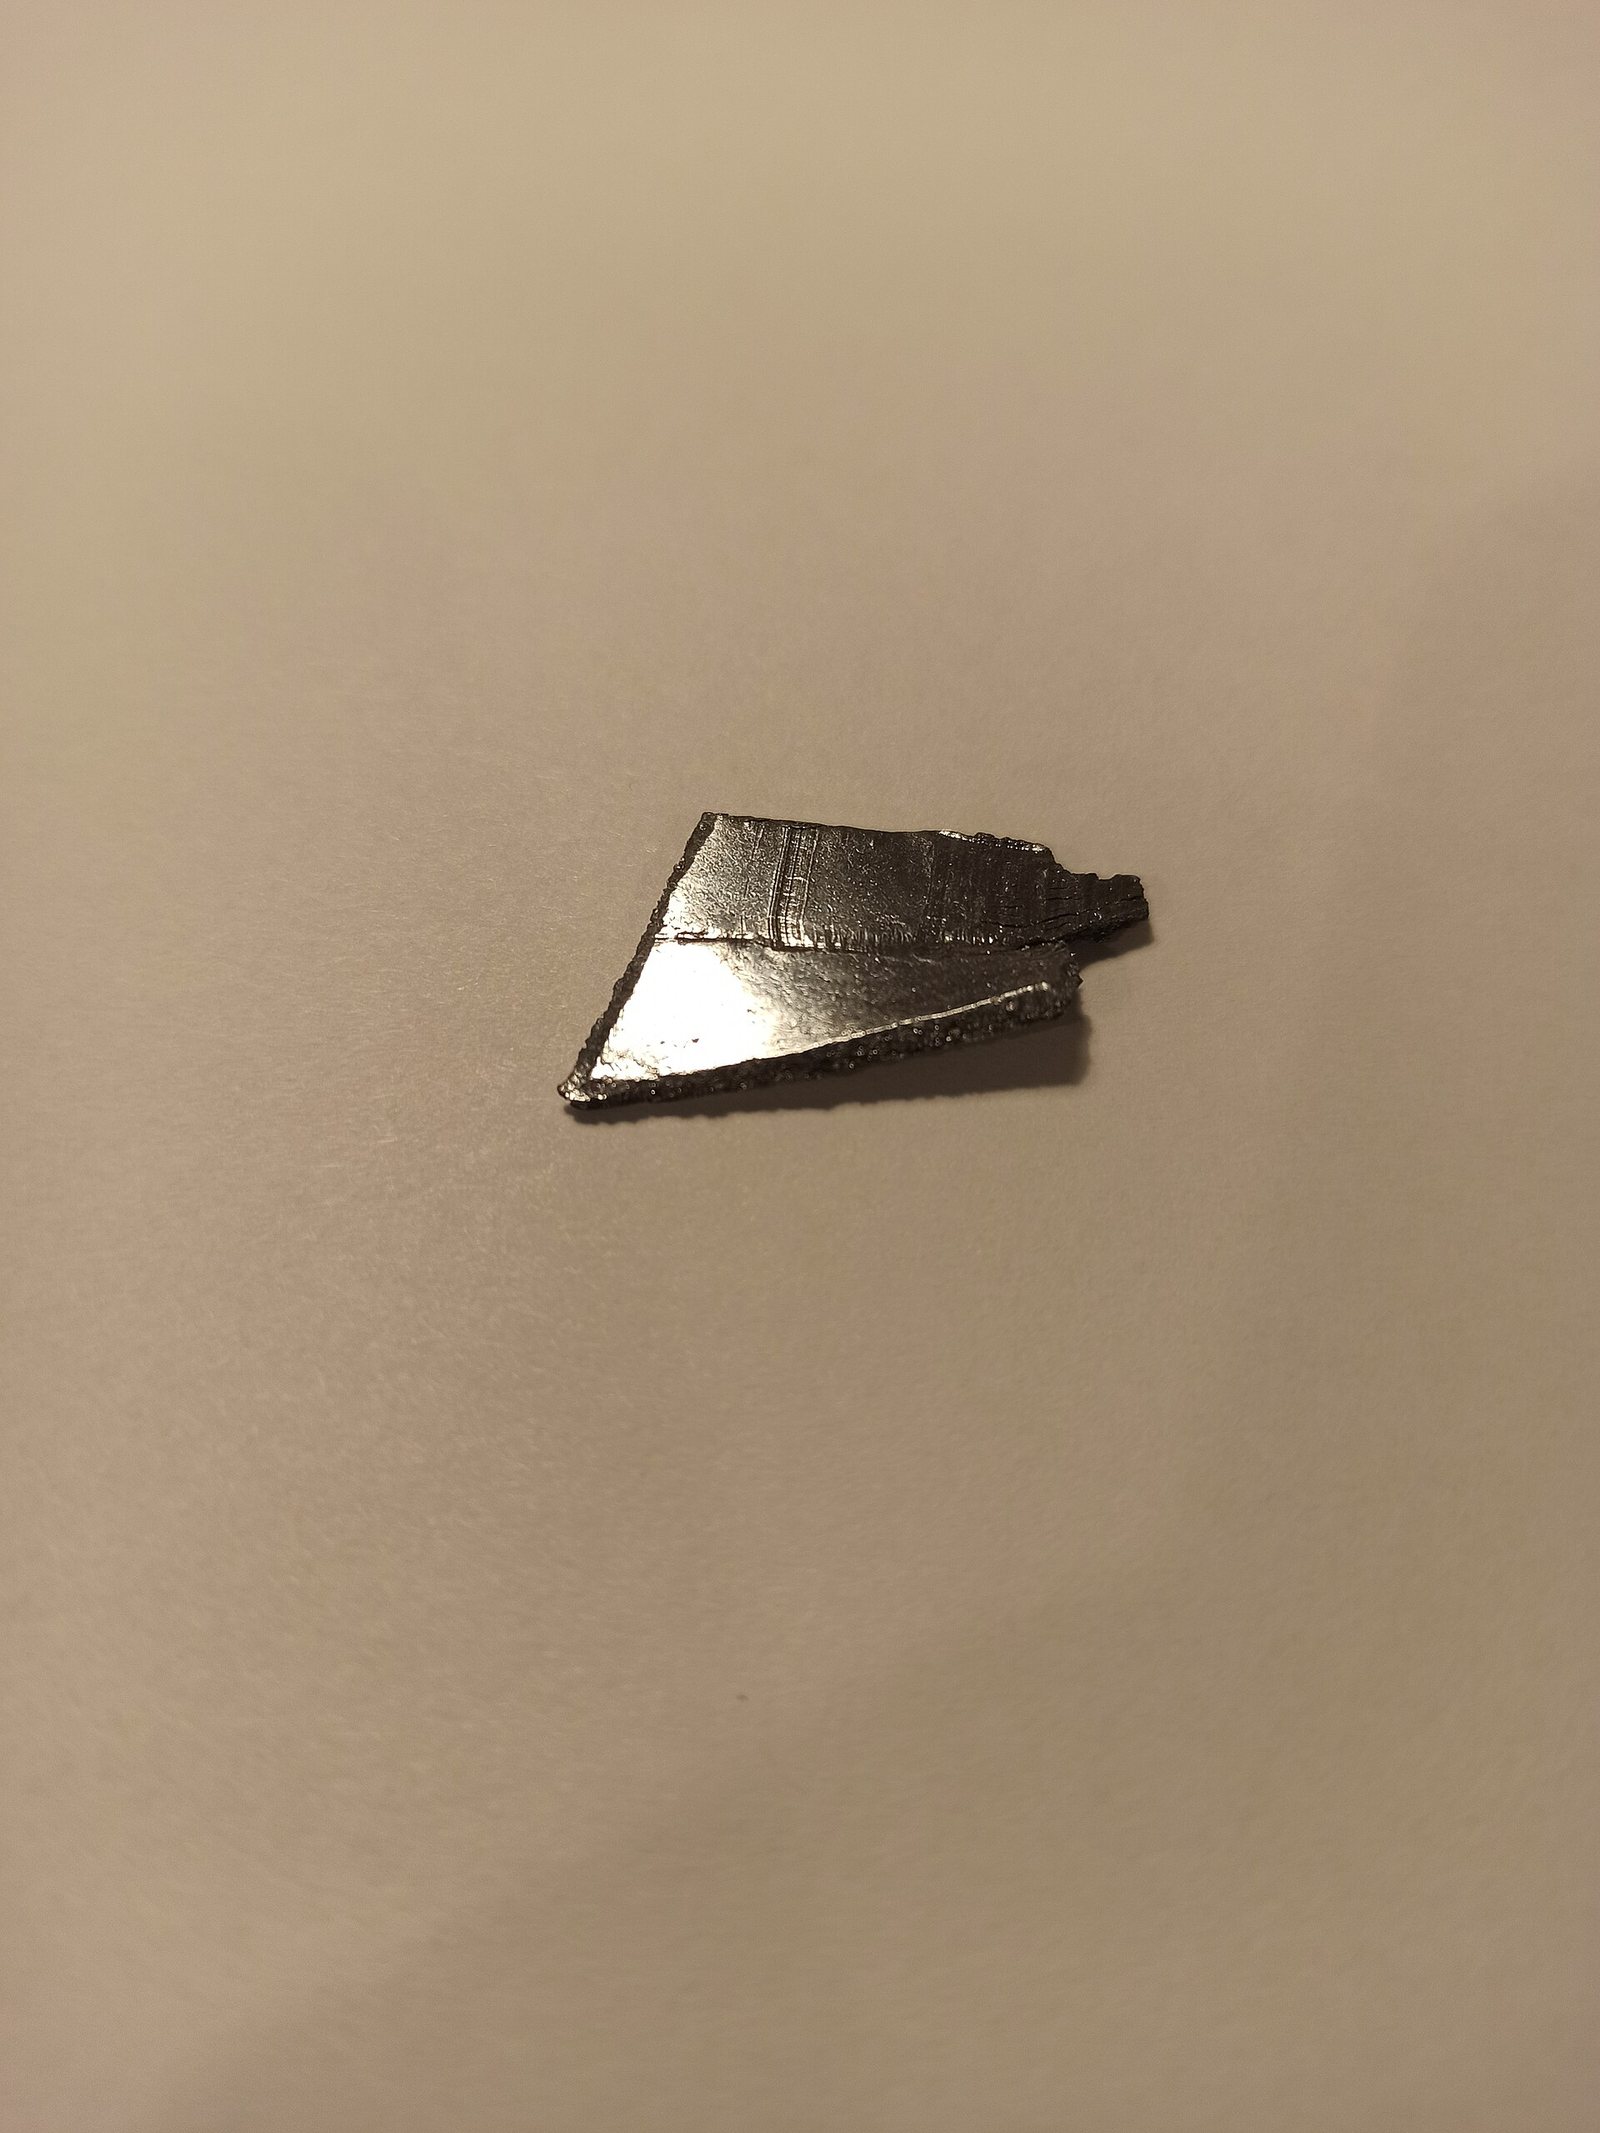
Qu'est-ce que c'est ?
One of the rarest metals in the crust, recovered from molybdenum roasting, and the ingredient that lets a jet turbine blade run hotter.
Pourquoi est-ce important ?
Second- and third-generation single-crystal superalloys contain 3-6% rhenium. Engine efficiency is directly tied to that temperature margin.
Where it is in the Earth
Rhenium is one of the rarest elements in the Earth's crust, and it does not form ore minerals of its own in any commercially meaningful sense. Instead, it occurs in trace amounts within molybdenite (molybdenum disulfide, MoS₂), the principal ore mineral of molybdenum. Molybdenite has a layered crystal structure that can accommodate rhenium atoms substituting for molybdenum, so wherever molybdenite forms in quantity, a small but recoverable fraction of rhenium comes along with it. The concentrations involved are extraordinarily low — far below what would register as a grade in any conventional mining context — yet because molybdenite itself is mined in large volumes, the absolute quantities of rhenium that pass through the system become economically meaningful.
The deposits that carry most of the world's rhenium are porphyry copper-molybdenum systems: large, low-grade bodies of mineralisation formed when metal-rich fluids expelled from cooling granite intrusions percolated outward into the surrounding rock and deposited sulphide minerals over immense volumes. The word porphyry refers to the texture of the host rock, which contains large crystals set in a finer-grained matrix. These systems are geologically young by crustal standards and tend to cluster along continental arcs — the chains of volcanoes thrown up where one tectonic plate dives beneath another. Chile's position along the Andean arc places it above one of the most productive belts of porphyry mineralisation on Earth, which is why Chile holds both the largest reserves and the largest annual output of rhenium. The same arc-related geology recurs in Central Asia, the western United States, and parts of East Asia, explaining the geographic spread of producing countries shown in the table above.
Because rhenium is bound inside molybdenite at the atomic level rather than occurring as a separate mineral phase, it cannot be concentrated by any process that targets rhenium specifically. Its geography is entirely inherited from the geography of molybdenum, and ultimately from the distribution of porphyry copper systems around the world's subduction zones.
Getting it out
Rhenium is never the reason a mine exists. It arrives entirely as a by-product — a secondary recovery from operations whose economics are driven first by copper and, to a lesser degree, by molybdenum. The large porphyry deposits that host it are almost always worked by open-pit mining, a method suited to low-grade, high-volume ore bodies where the mineralisation is too dispersed and too near the surface to justify the cost and complexity of underground workings. In open-pit mining, rock is drilled, blasted, and removed in a descending series of benches, with the ore trucked to a processing plant and the waste rock stacked separately. The ratio of waste to ore moved — the strip ratio — can be high in these operations, meaning that very large quantities of material must be shifted to access each tonne of copper-bearing rock.
The rhenium content of the ore is not a figure that drives any mining decision. Operators measure it, because it determines what they will recover downstream, but the mine plan is set around the copper and molybdenum grades. For a reader trying to understand what the production figures in the table mean in practice, the key point is that rhenium output from any country is essentially a function of how much molybdenite concentrate that country's copper mines are producing in a given year, not of any deliberate choice to produce rhenium. When copper demand falls and mines curtail output or reduce throughput, rhenium supply falls with it, regardless of what the rhenium market is doing.
What pulls on it
The dominant use of rhenium is in the single-crystal nickel superalloys from which the high-pressure turbine blades of jet engines are made. To understand why rhenium matters here, it helps to know what a single-crystal superalloy is. Conventional metal alloys are made up of many small crystalline grains bonded together; at very high temperatures, those grain boundaries weaken and allow the material to creep and deform. Engineers in the mid-twentieth century learned to cast turbine blades as a single uninterrupted crystal, eliminating grain boundaries entirely and dramatically extending the temperature at which the blade remains mechanically sound. Rhenium, added at concentrations of a few percent, further stabilises the crystal structure at extreme temperatures by slowing the diffusion of atoms through the alloy — a phenomenon called creep resistance. Higher operating temperatures mean more efficient combustion and lower fuel consumption for a given thrust, which is why engine manufacturers have strong incentive to use rhenium-bearing alloys in the hottest parts of their turbines.
The civil aviation industry is the largest single source of demand, followed by military aviation and industrial gas turbines used in power generation. Demand in these sectors tracks the production rate of new engines rather than the size of the existing fleet, because rhenium is consumed when an engine is built or its hot-section components are replaced. When new commercial aircraft orders are strong and engine manufacturers are running at high rates, rhenium demand rises accordingly. A prolonged reduction in new aircraft deliveries — whether from an economic downturn, a supply-chain disruption, or a shift in airline ordering — would reduce rhenium consumption materially, because there is no other use of comparable scale to absorb the difference.
Rhenium also appears in reforming catalysts used in petroleum refining to improve the octane rating of gasoline, and in smaller quantities in thermocouples, electrical contacts, and laboratory instruments that exploit its exceptional melting point. However, the superalloy application dwarfs all others, and the trajectory of demand is largely a story about commercial aerospace build rates and the continued preference of engine designers for rhenium-bearing alloy generations over alternatives.
Turning ore into product Niveau 3
The path from mine to usable rhenium runs through several distinct stages, each with its own recovery losses. At the concentrator attached to a porphyry copper mine, the crushed ore is processed by froth flotation, a method that exploits differences in surface chemistry to float sulphide minerals — including molybdenite — away from waste rock in a stream of air bubbles. The resulting molybdenum concentrate contains the bulk of the rhenium that was in the ore. This concentrate is then sent to a roaster, where it is heated in air to convert molybdenum sulphide into molybdenum oxide. The sulphur is driven off as sulfur dioxide, and the rhenium, which is volatile at roasting temperatures, exits the furnace as rhenium heptoxide vapour. Scrubbing systems capture this vapour by passing the gas stream through water or alkaline solution, producing a liquid rich in perrhenate ions. That solution is processed — typically through ion exchange and crystallisation — to yield ammonium perrhenate (APR), the standard intermediate commodity form of rhenium shown in the price table.
Ammonium perrhenate can be reduced to rhenium metal powder by heating it in a hydrogen atmosphere, a step that strips away the ammonium and oxygen to leave pure metal. The powder is then either pressed and sintered into shapes or, more commonly for aerospace use, dissolved into a nickel-base master alloy melt — a concentrated intermediate that superalloy producers blend into their final compositions. Each conversion step carries some loss, and the overall yield from ore to finished metal is considerably below one hundred percent. The processing chain is geographically fragmented: a copper mine in Chile may send molybdenum concentrate to a roaster in the United States or Europe, where APR is produced and then sold onward to a metal refiner or alloy maker in another country entirely. The Rolls-Royce manufacturing facility in Derby listed in the plant table represents the downstream end of this chain, where rhenium-bearing superalloy is worked into turbine components.
One consequence of this structure is that the point of rhenium production — the roaster — is not necessarily in the same country as the mine, which complicates national-level reporting. A country may appear in the production table because it operates roasters fed by imported concentrates rather than because it mines rhenium-bearing ore domestically. South Korea's entry in the production table reflects exactly this situation: it operates molybdenum roasting capacity supplied partly by imported concentrates rather than significant domestic porphyry mining.
Substitution and recycling Niveau 3
Within the superalloy application, substitution is technically possible but involves a direct performance penalty. First-generation single-crystal superalloys contain no rhenium; second- and third-generation alloys add progressively more, gaining higher temperature capability with each step. An engine designer could specify a first-generation alloy and avoid rhenium entirely, but the blade would need to operate at a lower temperature or with greater cooling air flow, reducing overall engine efficiency. The decision is not simply about material cost: it involves certification of a new alloy in a qualified engine, which is a lengthy and expensive process. Once an engine design has been certified with a specific alloy generation, changing it requires effectively re-certifying the affected components. This inertia means that even when rhenium prices rise sharply — as the price table shows they have done between 2023 and 2025 — established engine programmes do not switch away quickly.
Research into fourth-generation and later alloys has in some cases explored ruthenium as a partial substitute or complement for rhenium, not to eliminate rhenium but to allow its content to be reduced while maintaining or extending temperature capability. Whether this reduces net demand for rhenium depends on the alloy composition chosen and the production volumes involved. Separately, ceramic matrix composites (CMCs) are being introduced into turbine hot sections in some engine designs; these materials require no rhenium at all, and their gradual adoption in components where they can tolerate the mechanical loading involved will over time reduce the rhenium intensity of new engines. The pace of CMC adoption is constrained by manufacturing maturity and the range of components for which the material is qualified.
Recycling of rhenium from spent turbine blades is technically straightforward and commercially practised. When blades are removed from service — either at end of engine life or during overhaul — the superalloy can be remelted and the rhenium recovered. The recovery rate from this stream is meaningful, but the total quantity returned is limited by the size of the installed base of rhenium-bearing engines relative to annual primary production, and by the fact that blades sometimes remain in service for many years before retirement. The recycled fraction supplements primary supply but is not large enough to reduce the market's dependence on primary production from copper-molybdenum operations.
Where the chain is fragile Niveau 4
The supply chain for rhenium carries several structural vulnerabilities that are worth distinguishing from one another. The first and most fundamental is by-product dependence: because rhenium can only be recovered during the processing of molybdenite, its production cannot be adjusted in response to rhenium-specific demand signals. A spike in rhenium prices does not cause more rhenium to be produced; it causes slightly more careful recovery at existing roasters, and perhaps some marginal improvement in yields, but it cannot call new supply into existence. Conversely, a contraction in copper mining reduces rhenium output regardless of how tight the rhenium market is. This decoupling of price signal from supply response is unusual among industrial metals and makes the market structurally prone to imbalances that persist longer than they would in a primary-mined commodity.
The second risk is geographic concentration. Chile accounted for 30,000 kilograms of the 81,000-kilogram world total in 2025 — more than any other country — and holds 1,300,000 kilograms of identified reserves, again the largest national figure. A disruption at one of the large Chilean copper-molybdenum operations, whether from labour action, water constraints in the Atacama, regulatory change, or infrastructure failure, would remove a substantial share of world rhenium supply with essentially no short-run replacement available. The U.S. net import reliance figure of 75 percent for 2025 illustrates how exposed consuming nations are to this concentration. Russia's production figure is withheld by the source, which itself reflects a data gap that complicates any assessment of how the market would respond to a geopolitical disruption involving that country; reserve figures suggest Russia holds a meaningful share of the global total.
A third layer of fragility lies in the processing infrastructure. The roasting capacity that converts molybdenum concentrate into ammonium perrhenate is concentrated at relatively few facilities, and each facility represents a single point of failure between the mine and the market. Published production statistics report rhenium at the point of recovery — typically the roaster output — but the accounting conventions used by different national statistical agencies are not uniform. Some report by country of mining origin, others by country of processing, and the traded intermediate (ammonium perrhenate) may cross multiple borders before becoming metal. This means that the country-level figures in the production table may reflect different things depending on the source, and reconciling them against trade statistics can produce apparent discrepancies that are artefacts of reporting convention rather than genuine data errors. Researchers working with these figures should examine whether a given national series is tracking concentrate production, roaster output, or refined metal, as the three do not always align in the same calendar year.
Qui le produit
Voir sur une carte →Mine production
Mine productionkilograms 2025 (estimé) Total mondial 81,000 kilograms
USGS Mineral Commodity Summaries 2026 · Reported in kilograms, not tonnes — annual world output is measured in tens of tonnes. · source ↗
Faire défiler le tableau latéralement pour afficher les colonnes restantes.
| Pays | Production | Part mondiale |
|---|---|---|
| Chile | 30,000 | 37.0% |
| China | 20,000 | 24.7% |
| Poland | 10,000 | 12.3% |
| United States | 9,800 | 12.1% |
| Uzbekistan | 7,000 | 8.6% |
| Korea, Republic of | 3,000 | 3.7% |
| Kazakhstan | 1,000 | 1.2% |
| Armenia | 200.0 | 0.2% |
| Russia | Not applicable | — |
| Total mondial | 81,000 | 100% |
« Withheld » signifie que l'USGS a supprimé le chiffre afin de ne pas divulguer les données d'une entreprise individuelle — cela ne signifie pas zéro. La somme des lignes par pays ne correspond pas toujours au total mondial, car la source arrondit chaque chiffre de manière indépendante et ne détaille pas toujours une ligne « autres pays ».
Qui détient les réserves
Reserves
Reserveskilograms 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Pays | Réserves | Part mondiale |
|---|---|---|
| Chile | 1,300,000 | — |
| United States | 400,000 | — |
| Russia | 310,000 | — |
| China | 200,000 | — |
| Kazakhstan | 190,000 | — |
| Armenia | 95,000 | — |
| Korea, Republic of | Not applicable | — |
| Poland | Not applicable | — |
| Uzbekistan | Not applicable | — |
| Total mondial | Large | 100% |
Prix
average value, gross weight, dollars per kilogram: Metal, 99.99% pure
Moyenne annuelledollars per kilogram
Base: average value, gross weight, dollars per kilogram: Metal, 99.99% pure. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
average value, gross weight, dollars per kilogram: Ammonium perrhenate
Moyenne annuelledollars per kilogram
Base: average value, gross weight, dollars per kilogram: Ammonium perrhenate. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
Où c'est traité et raffiné
| Usine | Type | Étape | Pays | Rôle |
|---|---|---|---|---|
| Aero-Engine Turbine Plant, Derby | Usine de fabrication | Produit | United Kingdom | Intrant |
À quoi cela sert
Tous les marchés finaux →| Marché final | Ce qu'il fait là-bas | Importance |
|---|---|---|
| Aerospace & Defence | Single-crystal superalloy | Définition de |
Quelle quantité en nécessite une technologie
| Technologie | Quantité | Coté | Base |
|---|---|---|---|
| Single-Crystal Turbine Blade A few percent of a metal produced in tens of tonnes a year worldwide. | trace | per blade set | 3-6% of second and third generation superalloys |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. Appliquer ces chiffres à n'importe quelle échelle dans le calculateur de matériaux →