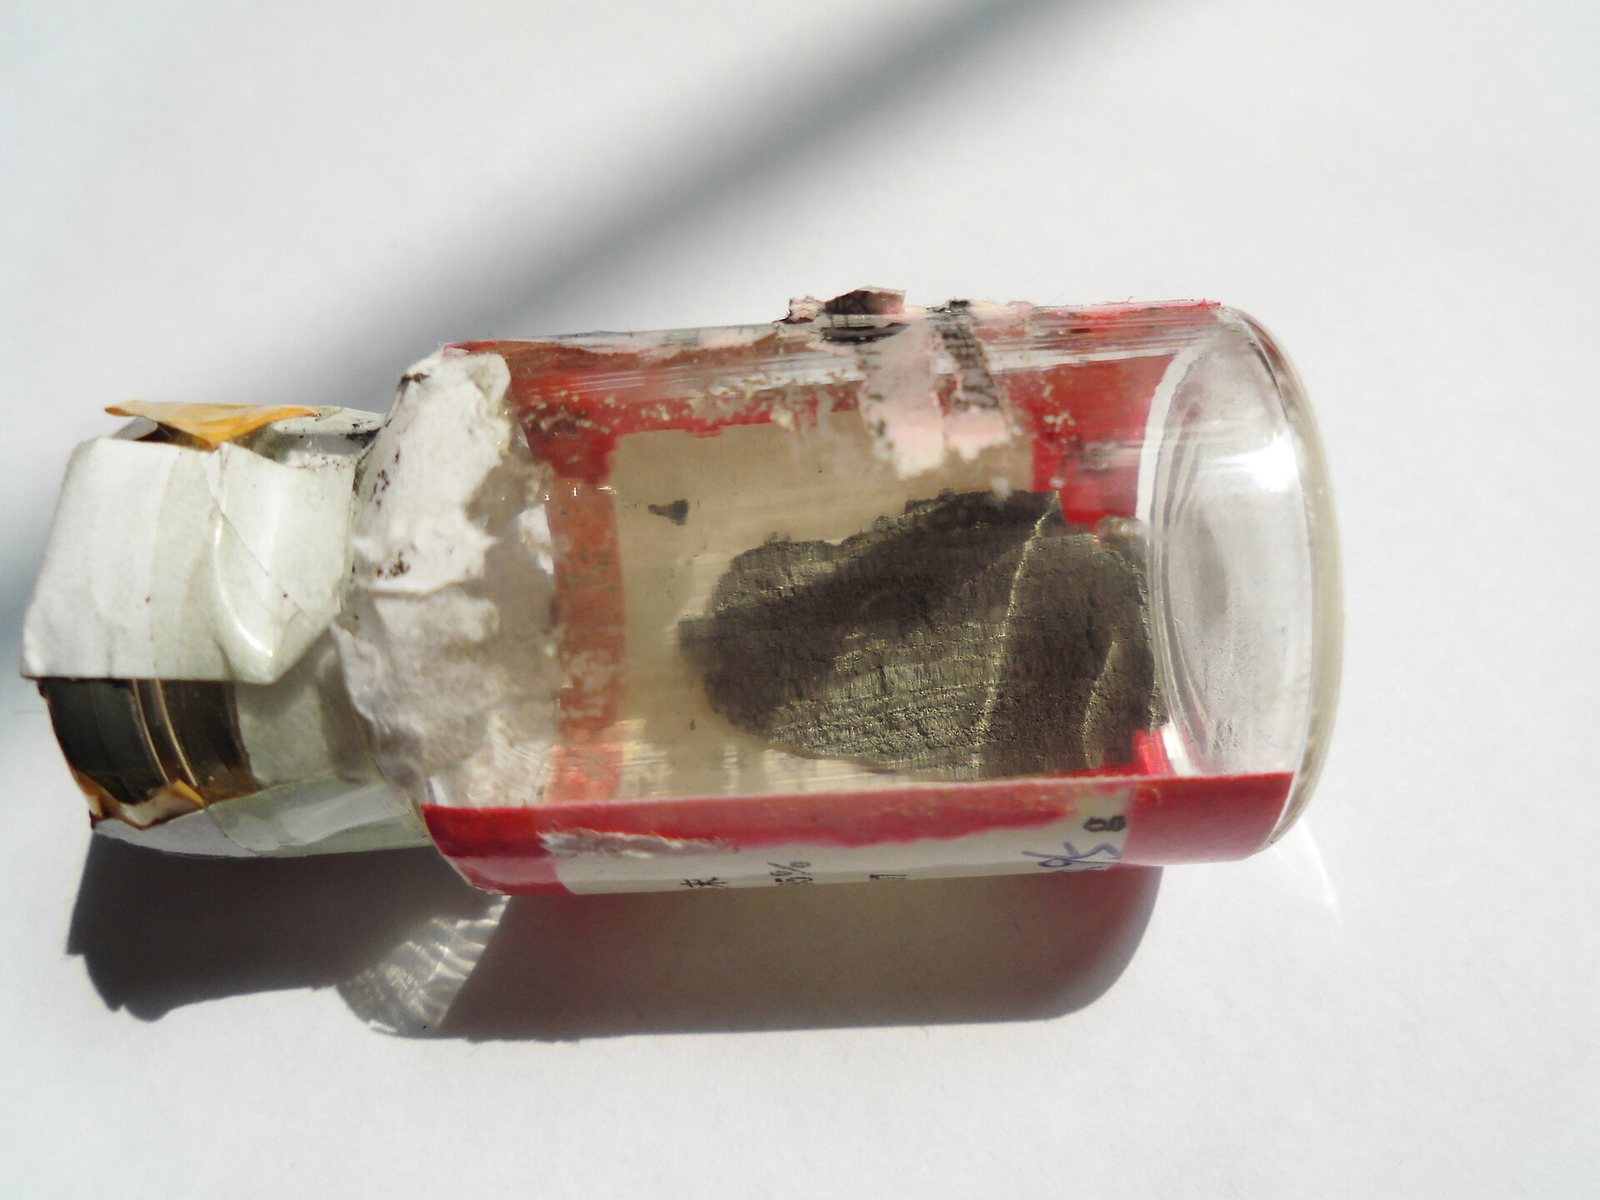
Was ist das?
A hard platinum-group metal used in tiny quantities inside hard drives and increasingly in chip interconnects.
Warum ist das wichtig?
As copper wiring inside chips shrinks below a certain width, ruthenium starts to conduct better than copper does.
Where it is in the Earth
Ruthenium belongs to the platinum-group metals, a cluster of six chemically similar elements that tend to occur together in nature. The geological story behind all of them begins with a particular kind of igneous rock called a layered mafic intrusion — a body of magma, rich in iron and magnesium, that cooled slowly deep in the crust over millions of years. As the melt crystallised, dense sulphide minerals sank and pooled into discrete horizons. Platinum-group metals, including ruthenium, were chemically drawn into those sulphide pools, concentrating there rather than remaining dispersed through the silicate rock above. The result is a series of thin but laterally extensive ore layers, sometimes only a metre or two thick, that can be traced for many kilometres across a single intrusion.
The overwhelming majority of the world's platinum-group metal endowment sits within a single geological structure: the Bushveld Igneous Complex in South Africa. This intrusion is both unusually large and unusually well preserved, which is why South Africa dominates the supply of the entire platinum-group suite. Smaller but significant concentrations occur in the Great Dyke of Zimbabwe and in the Norilsk-Talnakh deposits of northern Russia, where nickel-copper sulphides host platinum-group metals as a secondary constituent. In all these settings, ruthenium does not form its own discrete mineral in commercially meaningful quantities — the data block shows no ore minerals for it — because it travels within the sulphide lattice of other minerals and is only separated later, during refining.
This geological dependence on a specific rock type in a small number of locations is not incidental to how ruthenium is supplied; it is the entire explanation. There is no ruthenium ore in any conventional sense. There is platinum ore, and ruthenium is recovered from it. The concentration of ruthenium relative to crustal abundance is real, but it is inseparable from the concentration of the other platinum-group metals in the same rock.
Getting it out
Because ruthenium exists only as a trace constituent dispersed within platinum-group metal ore, it is never mined in its own right. The mining that matters to the ruthenium supply chain is the underground hard-rock mining of platinum reefs in layered intrusions, principally in South Africa. The ore horizons — called reefs — are thin, often steeply inclined, and lie at depths that make open-pit extraction impractical for the most productive sections. Underground methods therefore dominate, with miners following the reef along strike and extracting a narrow cut of rock. The amount of surrounding waste rock broken and moved per unit of reef material is substantial, because the reef itself is so thin that some dilution with barren footwall and hanging-wall rock is unavoidable.
Grade in this context is measured as the combined mass of platinum-group metals per tonne of ore, and ruthenium's share of that combined figure is a fraction. The grade of platinum-group metal ore is expressed in grams per tonne, which conveys how small the quantities involved are: a tonne of rock yields only a few grams of all platinum-group metals combined, of which ruthenium is a portion. This means the economics of mining are driven entirely by the value of platinum and palladium, which are present in larger proportions and command prices that historically exceed ruthenium's. Ruthenium has no influence on whether a mine is developed or kept open; it simply comes along when the platinum does.
The practical consequence for anyone trying to understand ruthenium supply is that no new mining project will ever be planned around ruthenium. Supply can grow only if platinum and palladium mining expands, and it can shrink for reasons — platinum market conditions, labour relations in South Africa, energy costs at deep mines — that have nothing to do with ruthenium demand.
What pulls on it
Ruthenium has historically found its largest use in data storage. Hard disk drives contain a thin layer of a ruthenium alloy within the recording stack — quantities that are small per drive but significant in aggregate given the scale of global hard disk production. This application draws on ruthenium's ability to influence the magnetic properties of the recording layer when deposited in very thin films. The quantities involved per device are tiny, measured in fractions of a gram, but the cumulative demand from billions of drives manufactured each year makes this a meaningful end market.
The end market the data block highlights — semiconductor interconnects at the smallest chip nodes — represents a different and more recent source of demand. As the copper wiring inside logic chips has been scaled down to extremely narrow dimensions, the electrical resistance of copper at those scales increases in ways that impair performance. Ruthenium does not suffer the same degradation at very small dimensions, which makes it a candidate material for the liners and fills used in the narrowest wiring levels. This is not a choice made for chemical elegance; it is a response to a physical constraint that copper cannot escape as feature sizes continue to shrink. The USGS identifies catalysts as a further application alongside electronic components and computer chips, and chlor-alkali electrodes — industrial cells used to produce chlorine and caustic soda — represent another established use where ruthenium oxide coatings extend electrode life.
What would need to change for demand to shift sharply? On the upside, broader adoption of ruthenium as an interconnect metal in leading-edge semiconductor manufacturing would add demand that is structurally different from disk drive consumption — less cyclical, more tied to chip production volumes, and potentially less easy to substitute away from once a process is qualified. On the downside, continued erosion of hard disk drives by solid-state storage removes a portion of existing demand that has no equivalent ruthenium content. The net direction depends on how quickly semiconductor interconnect adoption grows relative to how quickly spinning-disk storage shrinks.
Preis
dollars per troy ounce: Ruthenium
Jahresdurchschnittdollars per troy ounce
Grundlage: dollars per troy ounce: Ruthenium. Jahresdurchschnitte gemäß Veröffentlichung in USGS Mineral Commodity Summaries 2026 · Quelle ↗. Dies sind jährliche Referenzdurchschnittswerte, kein Live-Marktpreis.
Wo es aufbereitet und raffiniert wird
| Anlage | Art | Stufe | Land | Rolle |
|---|---|---|---|---|
| Rustenburg Base & Precious Metals Refineries | Raffinerie | Raffination | South Africa | Ausgabe |
Wofür es verwendet wird
Alle Endmärkte →| Endmarkt | Was es dort tut | Bedeutung |
|---|---|---|
| Semiconductors | Interconnect at the smallest nodes | Wichtig |