これは何か
A dense metal whose oxide layer stores charge extremely reliably, which is why it is in the capacitors of anything that must not fail.
なぜ重要なのか
Tantalum is also one of the '3TG' conflict minerals, so its supply chain carries formal due-diligence obligations in the US and EU.
Where it is in the Earth
Tantalum does not form its own rock. It is a minor constituent that became concentrated through the same igneous processes that built some of the world's most unusual granites. The relevant process is called magmatic differentiation: as a body of silica-rich magma cools slowly deep in the crust, the common elements crystallise out first, leaving the residual melt progressively enriched in elements that do not fit easily into ordinary minerals. Tantalum, together with niobium, is one of those elements. In the final, water- and volatile-rich fraction of the melt, conditions allow the growth of a rock type called a pegmatite — a coarse-grained granite in which individual crystals can reach extraordinary sizes and in which rare elements reach economically interesting concentrations.
The mineral that carries tantalum in these pegmatites is columbite-tantalite, familiarly abbreviated to coltan. It belongs to the oxide mineral group and accommodates both tantalum and niobium in variable proportions within the same crystal structure; when the tantalum content predominates the mineral is called tantalite, when niobium predominates it is columbite, and the real world offers every mixture between. Pegmatites that carry significant coltan belong to a geochemically distinct family known as LCT pegmatites — a shorthand for lithium, caesium and tantalum — reflecting the suite of rare elements that tend to travel together in this particular kind of residual melt. These bodies are typically tabular or lens-shaped, a few metres to tens of metres wide, cutting through older metamorphic or igneous host rocks.
The geographic distribution of tantalum deposits reflects where ancient, stable continental cores — called cratons — preserve the deep-crustal environments in which pegmatites were emplaced and then exhumed by billions of years of erosion. Central and West Africa sit on one of the world's oldest cratons, which is why the Democratic Republic of Congo, Rwanda, Nigeria and neighbouring countries host so much of the world's current production. Australia's long-stable Yilgarn and Pilbara cratons carry major hard-rock resources; Brazil's Amazonian craton is similarly endowed. The corollary of long erosion is that tantalum also accumulates in alluvial and eluvial placers — river gravels and weathered soils — where coltan grains, being dense and chemically resistant, survive transport and settling. Much of Central Africa's artisanal production comes from exactly these secondary placer deposits rather than from primary hard rock.
Getting it out
Because coltan occurs both in hard-rock pegmatites and in loose alluvial sediments, tantalum is extracted by two quite different methods. The hard-rock deposits in Australia are mined as open pits: the overlying soil and rock (called overburden) is removed by blasting and excavation to expose the pegmatite body below. This is capital-intensive and requires heavy machinery, but it is well-controlled and produces a consistent feed to the processing plant. The mine-to-product waste ratio in open-pit pegmatite mining is relatively high, because the ore mineral is a minor component of a rock that is itself mostly feldspar, quartz and other common silicates; large volumes of crushed rock must be processed to recover a small amount of coltan.
In Central Africa and parts of Brazil, a large share of production comes from artisanal and small-scale mining, usually of placer deposits. Miners dig or sluice river gravels and use the density difference between coltan (which is dense, at 16.65 grams per cubic centimetre for pure tantalum metal) and ordinary sand and clay (much lighter) to concentrate the heavy mineral by hand or with simple water-driven equipment. The technique is low in capital cost but is labour-intensive and difficult to monitor, which is directly relevant to the conflict-mineral due-diligence obligations that the tables on this page describe. Because the ore is already partially sorted by river transport, grades in alluvial concentrates can be surprisingly good, though they vary widely from site to site.
A distinct mode of supply is recovery as a by-product, most notably from the processing of tin ore (cassiterite). In parts of Nigeria and Central Africa, tin smelters have long recovered coltan from their feed material, and this by-product relationship means that tantalum output from some operations is tied to the economics of tin rather than to tantalum demand or price alone. The practical implication is that mine supply cannot always respond smoothly to changes in tantalum demand; a producer whose primary revenue comes from tin may continue or curtail tantalum output for reasons entirely unrelated to tantalum markets.
What pulls on it
Tantalum's dominant use is in capacitors — specifically tantalum electrolytic capacitors, which store and release electrical charge in electronic circuits. A capacitor made with tantalum is not simply a component choice of convenience; it is chosen because tantalum's oxide layer (tantalum pentoxide, Ta2O5) is exceptionally stable, has a high dielectric constant (meaning it stores a large amount of charge for its physical size), and does not degrade in the way that other capacitor chemistries can. This matters most where failure is unacceptable or where space is severely constrained: medical implants, military electronics, aerospace control systems and the power-management circuitry in smartphones and similar devices. Consumer electronics has historically been the single largest end market, driven by the number of capacitors packed into each device.
Data centres have become a growing source of demand, because the power-delivery circuits of server motherboards and networking equipment rely on many of the same tantalum capacitor designs used in consumer devices. The rapid expansion of computing infrastructure for machine learning and related workloads has added to this draw. Aerospace and defence demand is smaller in volume but notably price-insensitive — the specifications for military-grade tantalum capacitors are often written directly into procurement standards, which makes substitution slow even when it is technically feasible. The semiconductor segment, where tantalum is deposited as a very thin diffusion barrier in advanced chip manufacturing, is smaller still but growing as transistor geometries shrink and the number of metal layers in a chip increases.
For demand to change sharply in either direction, something structural would have to shift. A sustained move away from tantalum capacitors toward multi-layer ceramic capacitors (MLCCs) — which use no tantalum — is already visible in consumer electronics, where designers choose ceramics where reliability and size requirements permit. Expansion of data-centre build-out, of defence spending, or of advanced chip production would pull the other way. The two forces have roughly offset each other in recent years, keeping aggregate demand relatively stable, though the composition of that demand has been shifting away from consumer electronics and toward industrial and defence applications.
Turning ore into product レベル 3
Getting from coltan concentrate to a form that electronics manufacturers can use involves several distinct stages, each with its own yield losses and cost structure. The concentrate leaving a mine or artisanal operation is a mixed heavy-mineral product. It first undergoes physical upgrading — screening, gravity separation and, where equipment is available, magnetic or electrostatic separation — to remove lighter gangue minerals and to separate coltan from other dense minerals such as cassiterite or wolframite (the principal tungsten ore) that tend to co-occur. The product at this stage is typically traded as coltan concentrate, and its commercial value is quoted per kilogram on a tantalum pentoxide (Ta2O5) basis, as the price table on this page shows.
The concentrate is then chemically processed, almost entirely outside the producing countries, to extract pure tantalum compounds. The standard route begins with digestion in hydrofluoric acid, which dissolves the oxide minerals and brings tantalum and niobium into solution together. Solvent extraction — passing the solution through an organic solvent that selectively pulls one element across a liquid–liquid boundary — separates tantalum from niobium, which is a persistent companion throughout the process. The tantalum-rich stream is then precipitated as potassium tantalum fluoride, known in the industry as K-salt (K2TaF7), which is the intermediate traded form. K-salt is subsequently reduced — typically using sodium metal in a sealed vessel under inert atmosphere — to produce tantalum powder. This powder is the direct feedstock for capacitor manufacturing, where it is pressed into pellets, sintered and anodised. Alternatively, tantalum is consolidated into ingots or wire for superalloy and other metallurgical uses.
The processing chain concentrates value at each step, but it also concentrates the production of hazardous waste, particularly fluoride-bearing effluents from the acid digestion stage. The refining capacity that handles the bulk of global coltan is located in Asia and Europe, not in the mining countries, creating a structural separation between where the ore is produced and where it becomes a usable material. Losses occur at every stage — in physical concentration, in leaching, in solvent extraction and in reduction — and the cumulative yield from ore to finished powder is materially lower than 100 percent. The proportion of the original contained tantalum that ultimately reaches a capacitor factory depends on the efficiency of each individual plant, the quality of the concentrate feed, and how carefully the intermediate streams are managed.
Substitution and recycling レベル 3
The primary substitute for tantalum capacitors is the multi-layer ceramic capacitor, or MLCC. MLCCs use barium titanate as their dielectric and contain no tantalum at all; they are cheaper per unit and are produced in very large quantities. Where a circuit designer can tolerate the characteristics of a ceramic capacitor — including a capacitance that varies with applied voltage and temperature — the MLCC is a workable alternative, and substitution in consumer devices has been ongoing for years. The performance penalty is real but acceptable in many applications: tantalum capacitors do not exhibit the same voltage-dependent capacitance variation and have a long history of predictable ageing behaviour, which is why they remain the default choice in aerospace, defence and medical specifications. The qualification process for changing a component in a flight-certified or implantable device is long and expensive, which insulates tantalum demand in those segments from rapid substitution pressure regardless of price.
In the superalloy and sputtering-target applications — where tantalum metal or its compounds are used directly in high-temperature alloys or thin-film deposition — substitution is harder still. Niobium can replace tantalum in some superalloy compositions, but the two metals do not perform identically at elevated temperatures, and a change of alloy specification in an aero-engine component requires extensive re-testing. In diffusion-barrier applications in semiconductor fabrication, tantalum nitride is chosen because it reliably prevents copper from migrating into the surrounding silicon; alternative materials exist but have not displaced it at scale in advanced nodes.
Recycling of tantalum is technically straightforward from end-of-life capacitors and manufacturing scrap, and some tantalum powder is reclaimed from capacitor production waste. However, the quantity recovered from post-consumer electronics is modest relative to primary production. The reason is partly economic — tantalum is present in very small quantities per device, and separating it from the mass of other materials in an old phone or laptop requires processes whose cost can exceed the value recovered — and partly logistical, in that collection rates for small consumer electronics remain low in most markets. Manufacturing scrap, by contrast, is well-captured because it arises in clean, known quantities at processing plants and capacitor factories.
Where the chain is fragile レベル 4
The fragility of the tantalum supply chain has several distinct dimensions, and they are not all captured by any single statistic. The most obvious is geographic concentration at the mine stage: the production table shows that the Democratic Republic of Congo alone accounts for 1,300 of the 2,500 metric tonnes of world output in the reference year, and Rwanda and Nigeria together add several hundred more. This is not simply a matter of political risk in those countries, though that risk is real and documented; it is also a measurement problem. A substantial fraction of DRC and Rwandan output comes from artisanal and small-scale operations whose output is estimated rather than metered, and whose routing to international markets passes through intermediary chains of variable transparency. The unit basis note for this dataset explicitly acknowledges that much production comes from artisanal sources. Published country-level figures should therefore be read as informed estimates, not audited accounts.
A second structural fragility is the by-product relationship with tin. Where tantalum is recovered from tin-smelter residues rather than mined as a primary product, supply cannot be managed in response to tantalum market signals alone. A downturn in tin demand, a change in smelter economics, or a shift in smelter location can alter tantalum supply independently of what tantalum buyers need. This makes the effective supply elasticity lower than the existence of large resources in politically stable countries — Australia, Brazil, China — would suggest. Those resources are real, and the reserves figures in the table are substantial for China and Australia in particular, but converting a known resource into reliable annual production requires mine permitting, capital commitment and, for a primary tantalum project, a revenue case that rests on tantalum prices alone rather than on a more valuable co-product.
The processing bottleneck sits outside the mining countries entirely. The conversion of coltan concentrate to K-salt, and then to capacitor-grade powder, is performed by a small number of facilities concentrated in Asia and Europe. The United States source withholds its domestic production figure, and U.S. net import reliance is reported at 100 percent, with imports sourced from China, Australia, Germany and Indonesia in recent years. This means the effective supply chain runs from Central African and Australian mines, through Asian and European refiners, to capacitor manufacturers, many of which are also in Asia, before reaching device assemblers globally. A disruption at any point in that chain — conflict-mineral compliance failures that interrupt concentrate exports, refinery capacity constraints, or trade policy changes affecting intermediate materials — propagates quickly because there is little strategic stockholding at any stage. Lead times from a new mine decision to first production in a primary hard-rock tantalum operation have historically been measured in years to over a decade, which limits how quickly supply can respond to a perceived shortage.
岩石中の産出箇所
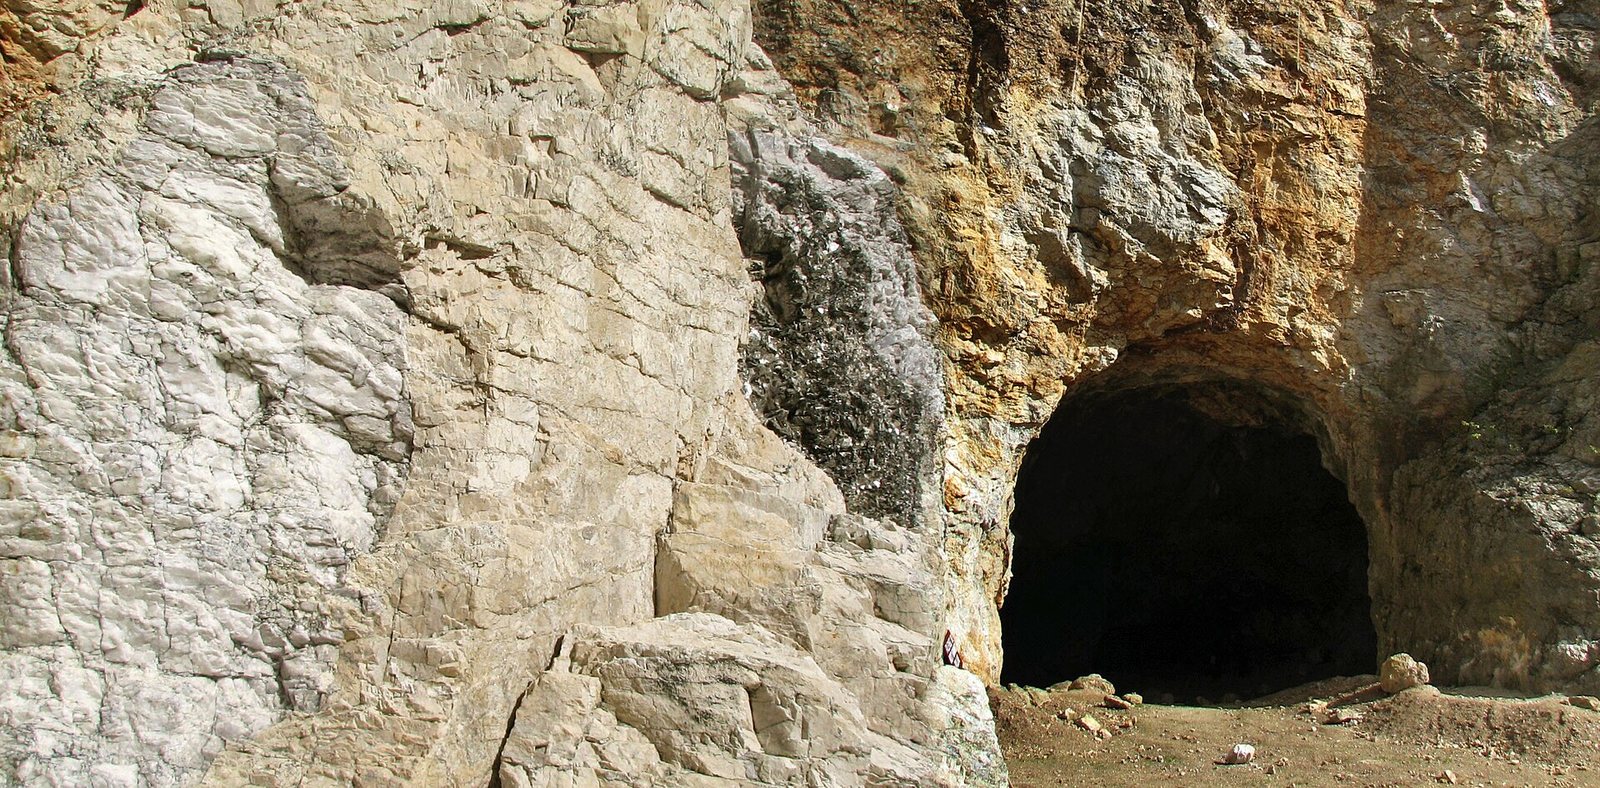
全鉱石鉱物 →実際に以下を担う鉱物 tantalum. 鉱床が鉱体となるのは、採掘コストを回収できるほど十分な濃度で鉱石が濃集している場合に限られる。
生産者
地図で見る →Mine production
Mine productionmetric tons 2025 (推定値) 世界合計 2,500 metric tons
USGS Mineral Commodity Summaries 2026 · Mine production of contained tantalum; much comes from artisanal sources. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| Congo (Kinshasa) | 1,300 | 52.0% |
| Rwanda | 400.0 | 16.0% |
| Nigeria | 390.0 | 15.6% |
| Brazil | 190.0 | 7.6% |
| China | 80.00 | 3.2% |
| Australia | 50.00 | 2.0% |
| Ethiopia | 40.00 | 1.6% |
| Russia | 30.00 | 1.2% |
| Burundi | 2.00 | 0.1% |
| Bolivia | 2.00 | 0.1% |
| Mozambique | 1.00 | 0.0% |
| United States | Zero | — |
| 世界合計 | 2,500 | 100% |
「非開示」とは、個別企業のデータが特定されないようUSGSが数値を公表しなかったことを意味し、ゼロを意味するものではありません。出典が各数値を独立して丸め処理しており、「その他の国」の内訳を常に示しているわけではないため、各国の数値の合計が世界合計と一致しないことがあります。
埋蔵量の保有者
Reserves
Reservesmetric tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| China | 240,000 | — |
| Australia | 120,000 | — |
| Brazil | 40,000 | — |
| Russia | 150.0 | — |
| Ethiopia | Not applicable | — |
| Mozambique | Not applicable | — |
| Nigeria | Not applicable | — |
| Rwanda | Not applicable | — |
| United States | Zero | — |
| Bolivia | Not applicable | — |
| Burundi | Not applicable | — |
| Congo (Kinshasa) | Not applicable | — |
| 世界合計 | Not applicable | 100% |
価格
tantalite, annual average, dollars per kilogram of tantalum oxide (Ta2O5) content
年間平均dollars per kilogram
基準: tantalite, annual average, dollars per kilogram of tantalum oxide (Ta2O5) content. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
産出鉱山
全鉱山 →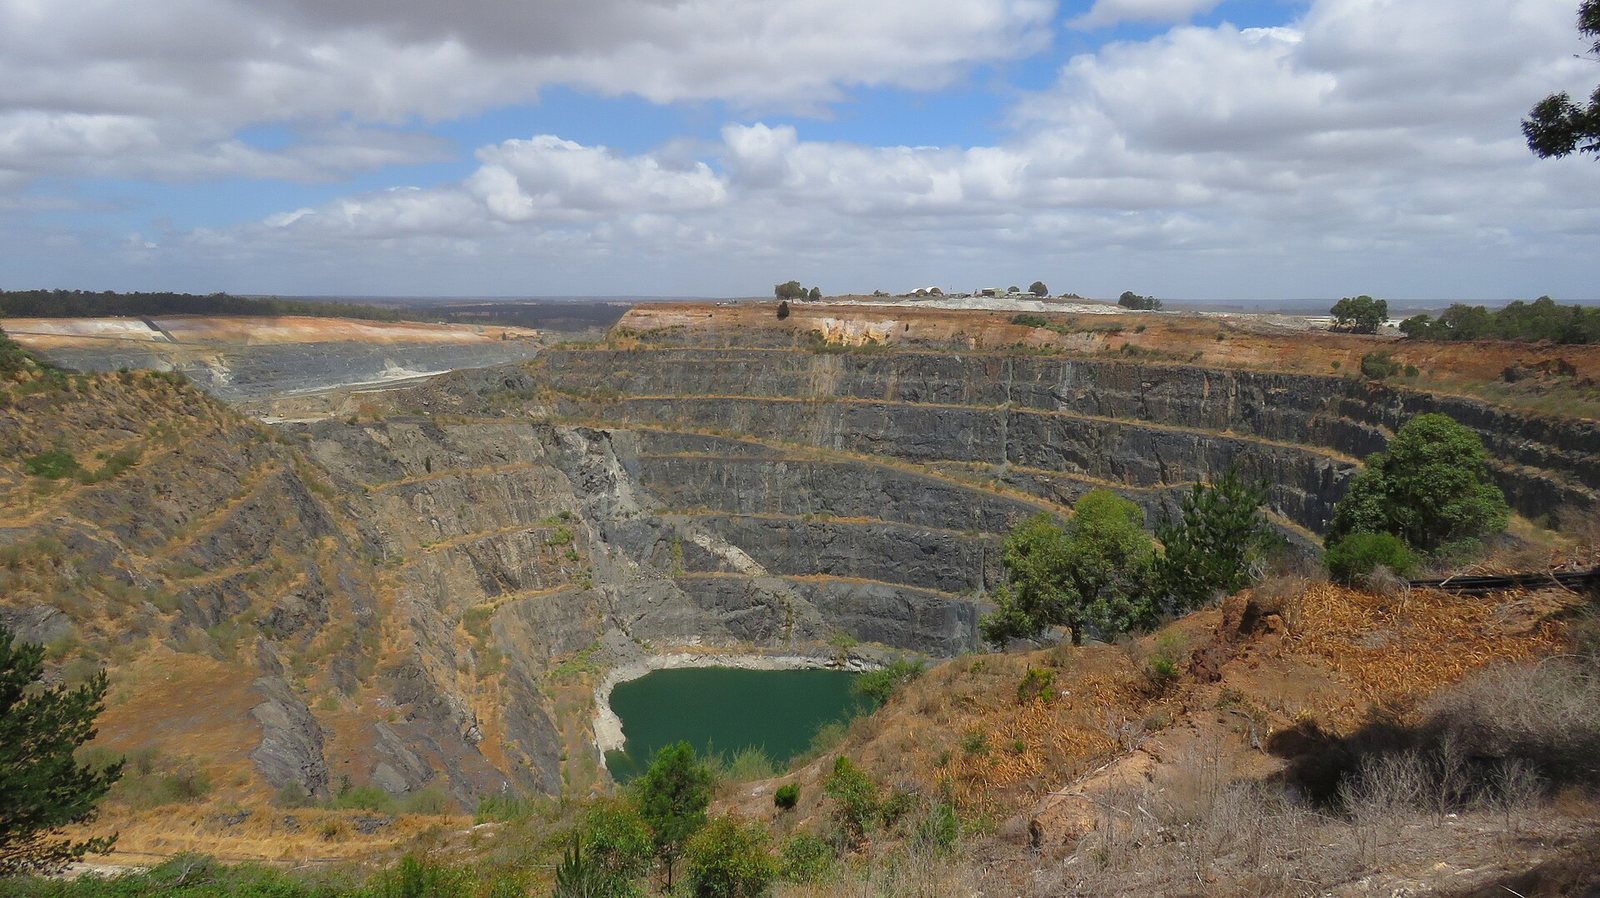
処理・精製が行われる場所
| プラント | 種別 | ステージ | 国 | 役割 |
|---|---|---|---|---|
| Aero-Engine Turbine Plant, Derby | 製造プラント | 製品 | United Kingdom | 投入 |
用途
全エンドマーケット →| 最終市場 | そこでの機能 | 重要度 |
|---|---|---|
| Consumer Electronics | Capacitors | 定義 |
| Data Centres & AI | Capacitors on power delivery | 重要 |
| Aerospace & Defence | Superalloy and capacitors | 重要 |
| Semiconductors | Diffusion barrier and capacitors | 重要 |
技術が必要とする量
| 技術 | 数量 | 建値 | 基準 |
|---|---|---|---|
| Single-Crystal Turbine Blade | 微量 | per blade set | Solid-solution strengthening |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. 素材計算機で任意の規模に換算して実行 →