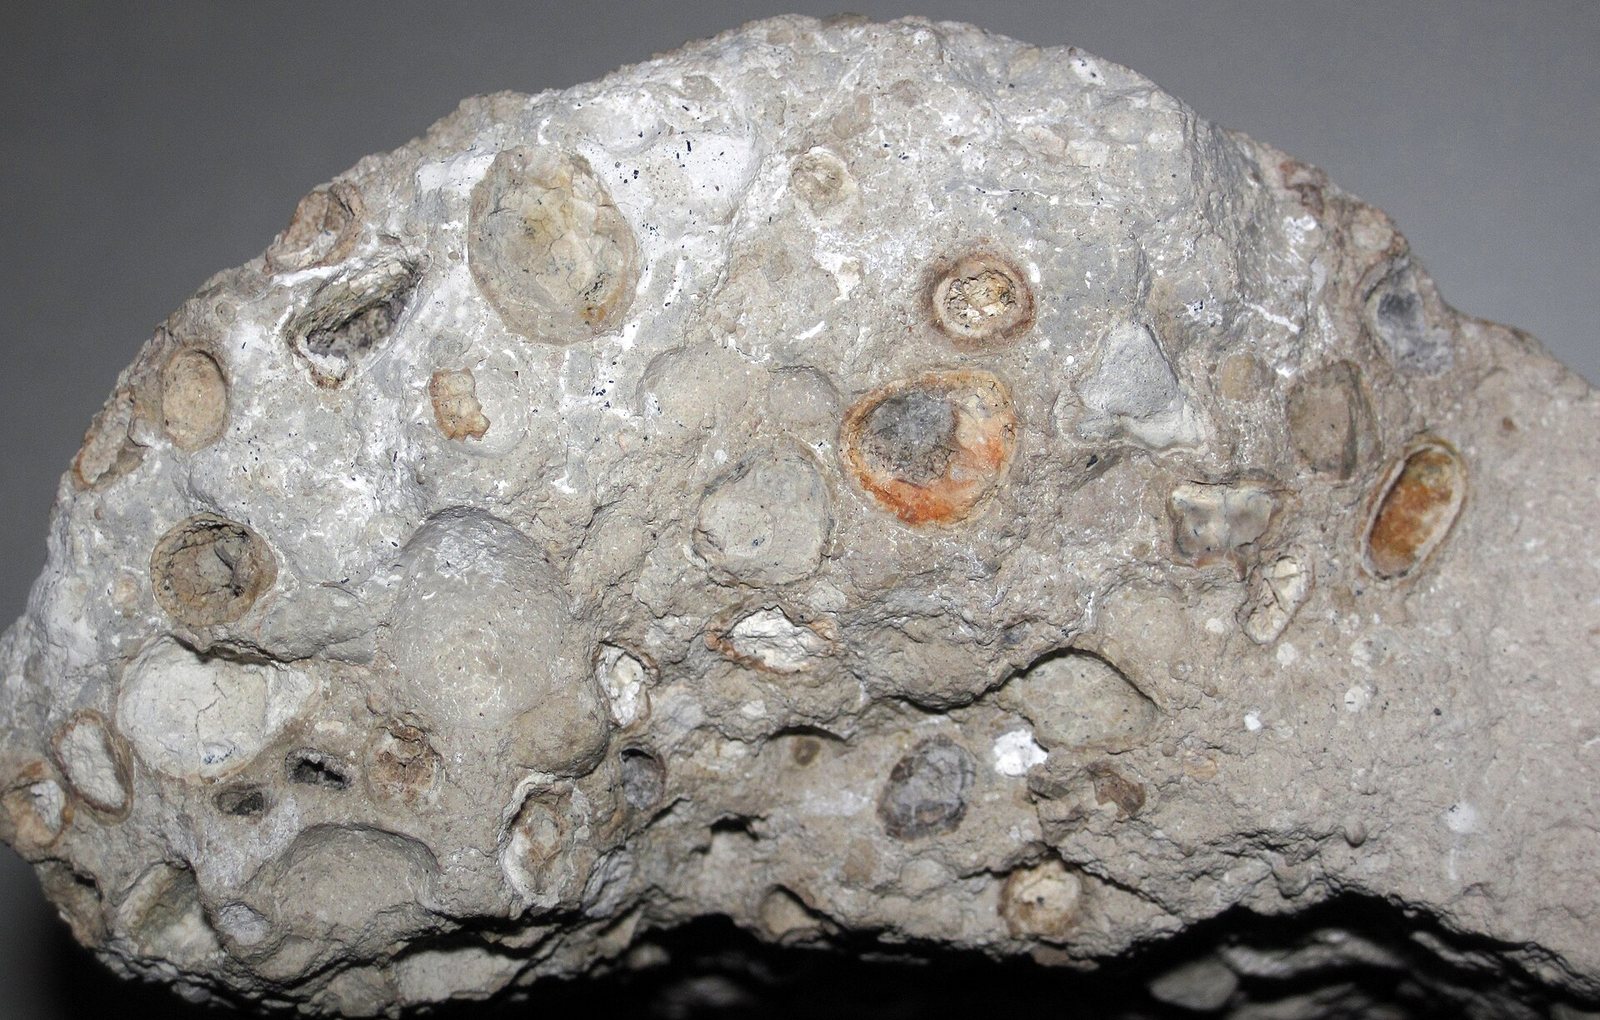
これは何か
A reddish soil-like rock, formed where tropical rain has rotted rock for millions of years, and the only ore aluminium is made from at scale.
なぜ重要なのか
Roughly four to five tonnes of bauxite become two tonnes of alumina become one tonne of aluminium. The chain starts in a handful of tropical countries.
Where it is in the Earth
Bauxite is not a single mineral but a mixture of aluminium-bearing hydroxide minerals — principally gibbsite (Al(OH)₃) and boehmite (AlO(OH)) — along with iron oxides, clay minerals, and silica. The rock forms at the surface, not deep underground, through a process called laterisation. In tropical and subtropical climates where rainfall is heavy and the wet season long, slightly acidic rainwater percolates through rock and slowly dissolves away the more soluble elements — silicon, calcium, magnesium — leaving behind aluminium and iron, which are far less mobile in those chemical conditions. Over millions of years, this residual enrichment builds up a layered crust that geologists call a laterite profile. Bauxite is the aluminium-rich upper portion of that profile.
Because the process depends on climate and time, the world's largest deposits sit close to the equator or at latitudes that were tropical during earlier geological periods. Guinea, which holds 7,400,000 thousand metric dry tons of reserves — more than a quarter of the world total of 29,000,000 thousand metric dry tons — sits squarely in the West African humid tropics. Australia's large deposits in the Cape York Peninsula and the Darling Range formed on ancient, deeply weathered cratons that have been stable and wet for long enough to build up thick ore profiles. Vietnam and Indonesia hold substantial reserves for the same reasons. The underlying bedrock matters too: rocks rich in aluminium-bearing silicates, such as granites, syenites, or nepheline syenites, provide more raw material for the weathering process to work on, though bauxite can also form over basalt and other rock types given enough time and rainfall.
The resulting ore body is typically a broad, shallow blanket rather than a deep vein or pipe. Ore zones commonly sit only a few metres below a thin topsoil layer, extending over tens or even hundreds of square kilometres, but rarely reaching more than twenty or thirty metres in depth. This geometry determines almost everything about how bauxite is mined.
Getting it out
The shallow, blanket-like geometry of most bauxite deposits makes open-pit mining the standard approach. Strip mining, a variant where ore is removed in long successive strips across a wide area, is particularly common because the ore horizon is thin and the overburden — the material sitting above it — is relatively modest. Machinery scrapes away the topsoil, which is typically stockpiled separately for later rehabilitation, then removes any soft overburden before excavators and scrapers load the ore directly into trucks. Because bauxite is already soft and friable from the weathering process that created it, blasting is often unnecessary, which reduces both cost and disturbance compared with hard-rock mining.
The grade of bauxite ore is expressed primarily as the available alumina content, often written as available Al₂O₃, alongside a measure of reactive silica. Reactive silica matters because it consumes reagent during processing, so a high silica content raises costs even if aluminium content looks acceptable. The ratio of how much ore must be moved to produce a given unit of alumina at the refinery is therefore not simply a function of aluminium grade but also of silica penalty and moisture content. The data underpinning this page records bauxite on a dry-weight basis, which strips out the moisture that ore can carry in large quantities given its soil-like texture.
After mining, ore is typically crushed and screened at or near the mine, then transported — often by rail or slurry pipeline — to a port for shipment. Some integrated operations process the ore directly at a nearby refinery. The relatively low value per tonne of raw bauxite compared with alumina or aluminium means that freight costs loom large, and most trade moves on long-term contracts rather than through spot markets.
What pulls on it
Aluminium is the end destination for the great majority of bauxite mined, and so the demand picture for bauxite is largely the demand picture for aluminium, filtered back through the conversion ratios in the chain. A smaller but not trivial fraction of bauxite is used without conversion to metal: calcined bauxite finds use as a refractory material (able to withstand very high temperatures) in steelmaking furnaces and kilns, and as an abrasive. These non-metallurgical uses draw on different ore grades and mineralogy, but they remain secondary to the aluminium pathway.
Aluminium's breadth of use — in transport, construction, packaging, electrical conductors, and consumer goods — means that demand for bauxite tracks broad industrial and economic activity rather than any single end market. The transport sector, particularly automotive and aerospace, tends to favour aluminium where light weight is worth paying for. Packaging, especially beverage cans, represents a high-volume, relatively stable use. Construction uses vary considerably with building activity in different regions. The growth of electricity infrastructure, including power cables and, more recently, components related to renewable generation and grid expansion, has kept electrical applications steady or growing in many markets.
A sharp change in bauxite demand would require either a major shift in the rate at which aluminium is used, or a significant change in how much aluminium comes from primary production (new metal from ore) versus secondary production (recycled metal). Both transitions are slow. Aluminium-intensive structures last for years to decades before the metal returns to the recycling stream, so even a rapid expansion of recycling takes considerable time to reduce the call on primary ore. Demand would fall if a sustained economic contraction reduced construction and manufacturing output across multiple large economies simultaneously, or if a material substituting for aluminium across multiple end uses were to become cost-competitive at scale — neither of which can be assumed to happen quickly.
岩石中の産出箇所
全鉱石鉱物 →実際に以下を担う鉱物 bauxite. 鉱床が鉱体となるのは、採掘コストを回収できるほど十分な濃度で鉱石が濃集している場合に限られる。
生産者
地図で見る →Bauxite, mine production
Bauxite, mine productionthousand metric dry tons 2025 (推定値) 世界合計 440,000 thousand metric dry tons
USGS Mineral Commodity Summaries 2026 · Gross weight of dry bauxite, not alumina or metal content. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| Guinea | 150,000 | 34.1% |
| Australia | 97,000 | 22.0% |
| China | 87,000 | 19.8% |
| Brazil | 33,000 | 7.5% |
| India | 25,000 | 5.7% |
| Indonesia | 10,000 | 2.3% |
| Other countries | 8,000 | 1.8% |
| Jamaica | 6,200 | 1.4% |
| Saudi Arabia | 5,700 | 1.3% |
| Russia | 5,700 | 1.3% |
| Kazakhstan | 4,800 | 1.1% |
| Turkey | 3,800 | 0.9% |
| Vietnam | 3,800 | 0.9% |
| Greece | 960.0 | 0.2% |
| Ireland | Zero | — |
| United States | Withheld | — |
| Canada | Zero | — |
| Germany | Zero | — |
| Spain | Zero | — |
| United Arab Emirates | Zero | — |
| 世界合計 | 440,000 | 100% |
「非開示」とは、個別企業のデータが特定されないようUSGSが数値を公表しなかったことを意味し、ゼロを意味するものではありません。出典が各数値を独立して丸め処理しており、「その他の国」の内訳を常に示しているわけではないため、各国の数値の合計が世界合計と一致しないことがあります。
埋蔵量の保有者
Bauxite reserves
Bauxite reservesthousand metric dry tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| Guinea | 7,400,000 | 25.5% |
| Other countries | 5,300,000 | 18.3% |
| Australia | 3,700,000 | 12.8% |
| Vietnam | 3,100,000 | 10.7% |
| Indonesia | 2,900,000 | 10.0% |
| Jamaica | 2,000,000 | 6.9% |
| Brazil | 1,700,000 | 5.9% |
| China | 710,000 | 2.4% |
| Russia | 650,000 | 2.2% |
| India | 650,000 | 2.2% |
| Saudi Arabia | 180,000 | 0.6% |
| Kazakhstan | 160,000 | 0.6% |
| Turkey | 69,000 | 0.2% |
| United States | 20,000 | 0.1% |
| Ireland | Zero | — |
| Canada | Zero | — |
| Germany | Zero | — |
| Greece | Zero | — |
| Spain | Zero | — |
| United Arab Emirates | Zero | — |
| 世界合計 | 29,000,000 | 100% |
価格
average unit value of imports, free alongside ship (f.a.s.), dollars per metric ton
年間平均dollars per metric ton
基準: average unit value of imports, free alongside ship (f.a.s.), dollars per metric ton. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
処理・精製が行われる場所
| プラント | 種別 | ステージ | 国 | 役割 |
|---|---|---|---|---|
| Bayer-Process Alumina Refineries, Western Australia | 精製所 | 処理 | Australia | 投入 |
| Port of Rotterdam Bulk Terminals | 港湾 | 処理 | Netherlands | 投入 |
輸出規制
| 国 | 支配 | 適用対象 |
|---|---|---|
| Indonesia | Export ban | Bauxite (2023), copper concentrates (2023), and nickel ore (2020). ↗ |
| Venezuela | Export ban | Bauxite, cassiterite, columbite-tantalite, copper, gold, rhodium, silver, and thorium (2024). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.
越境地点をたどる
すべての輸送経路 →この素材の特定の貨物が実際にたどる経路——すべての国、すべての管理者、各工程で残されるもの。
Guinean bauxite to an aluminium window frame Four tonnes of tropical soil, two tonnes of white powder, one tonne of metal — and the metal is made wherever the power is…