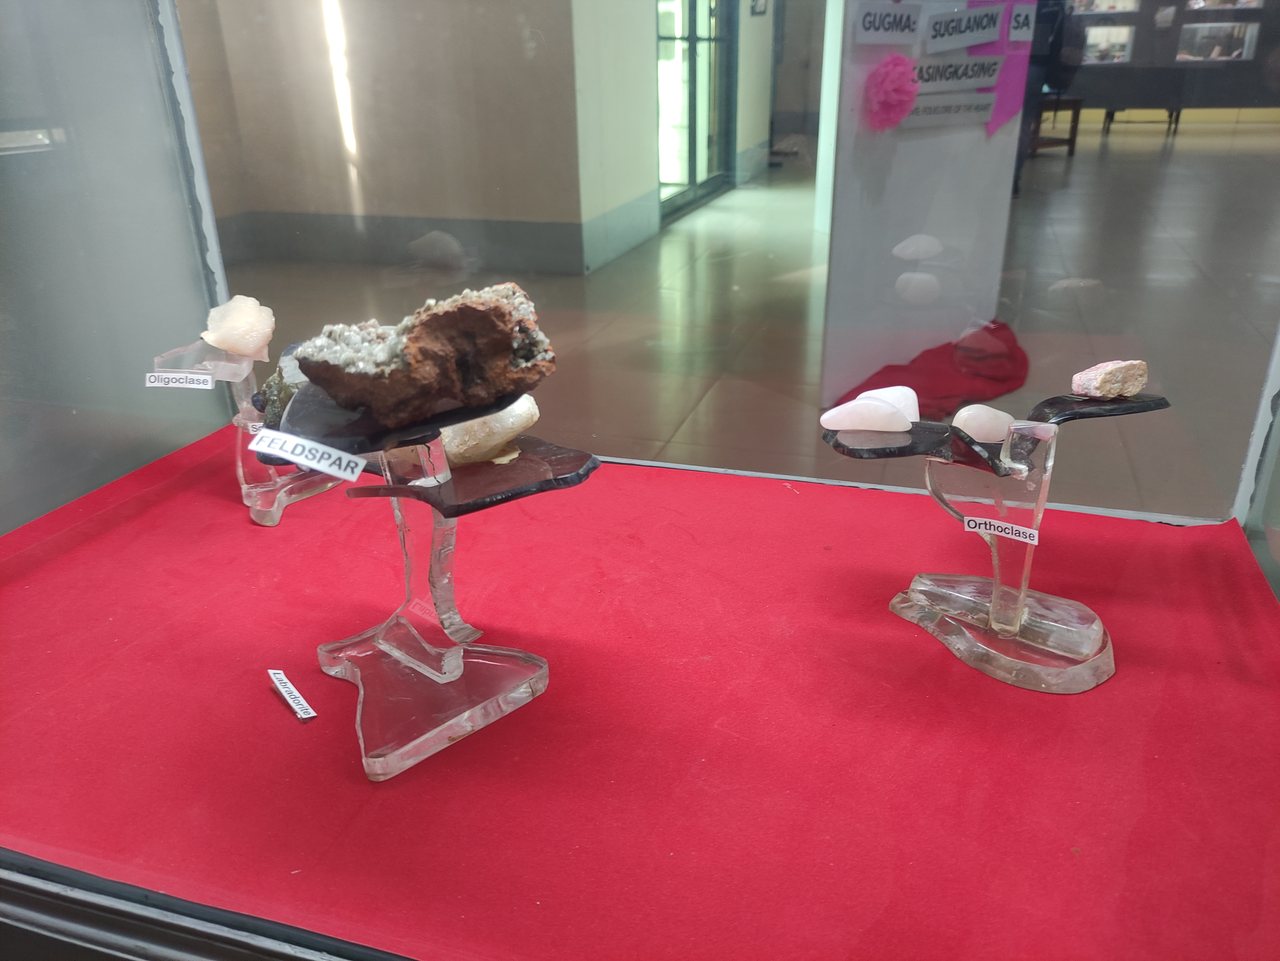
これは何か
The most abundant mineral group in the crust, used as the flux that lets glass and ceramic melt at a workable temperature.
なぜ重要なのか
Without a flux, glass would have to be melted hundreds of degrees hotter. Feldspar is a quiet energy saving on an enormous scale.
Where it is in the Earth
Feldspar is not a single mineral but a family of closely related silicate minerals built from silicon, oxygen, aluminium, and varying proportions of potassium, sodium, and calcium. Because these elements are among the most common in the Earth's crust, feldspar ends up in nearly every type of igneous rock — granite, syenite, rhyolite, and their volcanic equivalents — as well as in many metamorphic rocks that have been recrystallised under heat and pressure. The sheer abundance of feldspar in the crust is what makes it commercially interesting: the challenge is not finding it but finding it in a form that can be separated cleanly from quartz, mica, and other minerals that arrive alongside it.
Nepheline syenite is a different but related material. It forms when silica-poor magma solidifies and produces a rock rich in nepheline (a sodium-potassium aluminium silicate) rather than quartz. Because quartz is absent, nepheline syenite carries a higher aluminium oxide and alkali content than most feldspathic granites, which matters to the glass and ceramics industries for reasons explained under demand. The largest nepheline syenite deposits are associated with ancient, deeply eroded alkaline igneous complexes — the kind that form when unusual, silica-depleted melts intrude continental crust over millions of years.
Commercially worked feldspar deposits tend to cluster in pegmatites and in weathered or hydrothermally altered granite masses. Pegmatites are very coarse-grained igneous bodies that crystallise slowly from residual, water-rich magma, and the slow cooling allows individual feldspar crystals to grow large enough to separate mechanically. Countries such as Turkey and India sit on extensive belts of granitic and pegmatitic terrain, which explains why they appear so prominently in the production figures. China and Iran have broadly comparable geology. European producers, particularly Italy and Spain, have historically served the ceramic tile industry with feldspar from pegmatite districts close to their main consuming regions.
Getting it out
Almost all feldspar and nepheline syenite is won by open-pit mining, a method well suited to deposits that are broad, relatively shallow, and hosted in rock that does not require deep underground access. In an open pit, overburden — the soil and waste rock covering the ore — is stripped away by excavators and trucks, and the exposed feldspar-bearing rock is drilled, blasted, and loaded for transport to a processing plant nearby. Because feldspar deposits are typically massive and relatively uniform rather than narrow veins, open-pit operations can be designed to move material efficiently and at low cost per tonne.
The concept of grade matters differently here than in metal mining. There is no single percentage of feldspar in the rock that defines whether something is ore or waste; instead, the relevant qualities are the alkali content (how much potassium and sodium the feldspar carries), the iron content (which must be low to avoid discolouring glass or ceramics), and the particle size that can be achieved after grinding. A deposit that is mineralogically abundant but contains enough iron-bearing minerals to stain the product may be unworkable for premium end uses, even if it is physically straightforward to extract. The ratio of waste rock moved to marketable product shipped depends on deposit geometry and how much of the mined rock falls below specification, but for well-situated pegmatite quarries the ratio is generally modest compared with hard-rock metal mines.
Nepheline syenite operations follow the same broad approach, though the rock tends to be harder and more uniform, which influences blasting patterns and crusher settings. Because the deposits are often free of quartz — quartz is an impurity that must be removed in processing — the selectivity required at the mining stage can be less demanding than for feldspar from granitic sources, where quartz and feldspar are intimately intergrown and must be separated later by flotation.
What pulls on it
The single largest use of feldspar and nepheline syenite is as a flux in glass and ceramics manufacturing. A flux, in this context, is a material that lowers the temperature at which a mixture melts. Pure silica — the main ingredient in glass — has a melting point far beyond what most industrial furnaces can sustain economically. Adding feldspar introduces alkali oxides (principally potassium oxide and sodium oxide) that disrupt the silica network and bring the melting temperature down to a range that is commercially practical. The same logic applies in ceramic bodies and glazes: feldspar acts as a bonding phase that develops during firing and binds the other ingredients together. This is not a marginal contribution. As the plain definition on this page notes, feldspar represents a quiet energy saving repeated across an enormous industrial base.
The ceramic tile industry has historically been the dominant consumer, and its geography closely tracks where global feldspar production is concentrated. Countries producing large quantities of ceramic tiles — and the construction activity that absorbs them — drive a substantial share of demand. Sanitary ware, tableware, and technical ceramics also consume feldspar, though in smaller volumes. Flat glass (used in buildings and vehicles) and container glass are significant glass-sector consumers. Paints, rubber, and plastic fillers absorb a smaller share of output, typically the finer grades or material that does not meet the chemical specification for glass or ceramics.
Demand would shift materially if construction activity in major consuming economies fell sharply, since ceramic tiles and flat glass are strongly tied to the construction cycle. Conversely, growth in construction in South and South-east Asia has underpinned rising output from India, Iran, and Thailand over recent years. There is no obvious large new application on the horizon that would dramatically change the overall scale of consumption, and no technology trend that is rapidly eliminating feldspar from its existing uses. The material is not associated with any high-growth technology sector in the way that lithium or cobalt are, which means its demand profile is relatively steady and tied closely to broader economic and construction conditions.
生産者
地図で見る →Mine production
Mine productionthousand metric tons 2025 (推定値) 世界合計 31,000 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of marketable product. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| India | 6,000 | 19.4% |
| Turkey | 5,300 | 17.1% |
| Iran | 3,900 | 12.6% |
| China | 3,700 | 11.9% |
| Other countries | 3,400 | 11.0% |
| Italy | 2,200 | 7.1% |
| Thailand | 1,900 | 6.1% |
| Korea, Republic of | 1,000 | 3.2% |
| Morocco | 720.0 | 2.3% |
| Russia | 650.0 | 2.1% |
| Saudi Arabia | 650.0 | 2.1% |
| United States | 440.0 | 1.4% |
| 世界合計 | 31,000 | 100% |
Mine production: beneficiated, marketable
Mine production: beneficiated, marketablethousand metric tons 2025 (推定値)
USGS Mineral Commodity Summaries 2026 · Gross weight of marketable product. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| Brazil | 620.0 | — |
Mine production: includes pegmatites
Mine production: includes pegmatitesthousand metric tons 2025 (推定値)
USGS Mineral Commodity Summaries 2026 · Gross weight of marketable product. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| Spain | 620.0 | — |
「非開示」とは、個別企業のデータが特定されないようUSGSが数値を公表しなかったことを意味し、ゼロを意味するものではありません。出典が各数値を独立して丸め処理しており、「その他の国」の内訳を常に示しているわけではないため、各国の数値の合計が世界合計と一致しないことがあります。
埋蔵量の保有者
Reserves
Reservesthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| China | 730,000 | — |
| Turkey | 720,000 | — |
| India | 320,000 | — |
| Korea, Republic of | 200,000 | — |
| Iran | 130,000 | — |
| Thailand | 45,000 | — |
| United States | Not applicable | — |
| Italy | Not applicable | — |
| Morocco | Not applicable | — |
| Russia | Not applicable | — |
| Saudi Arabia | Not applicable | — |
| Other countries | Not applicable | — |
| 世界合計 | Large | 100% |
Reserves: beneficiated, marketable
Reserves: beneficiated, marketablethousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| Brazil | 150,000 | — |
Reserves: includes pegmatites
Reserves: includes pegmatitesthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| Spain | Not applicable | — |
価格
average unit value, dollars per metric ton: Feldspar only, marketable production
年間平均dollars per metric ton
基準: average unit value, dollars per metric ton: Feldspar only, marketable production. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
average unit value, dollars per metric ton: Nepheline syenite, imports
年間平均dollars per metric ton
基準: average unit value, dollars per metric ton: Nepheline syenite, imports. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。