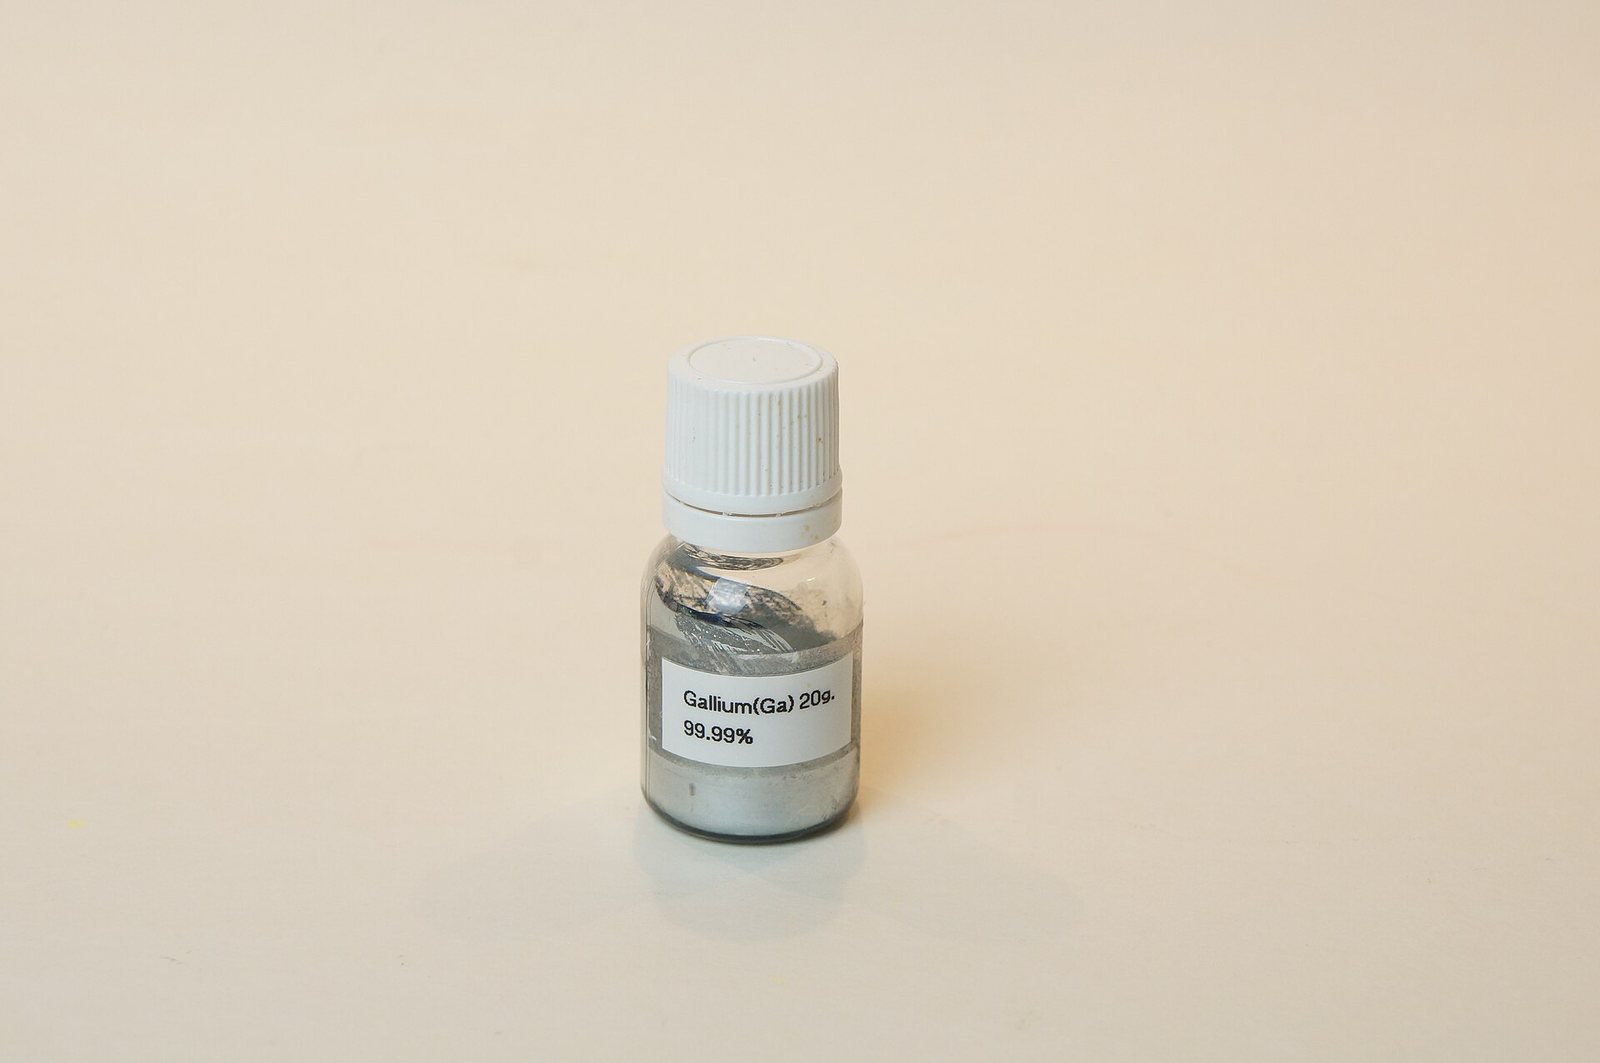
이것은 무엇인가?
A silvery metal that melts in your hand, and the basis of the compound semiconductors in fast chargers, radar and LEDs.
왜 중요한가?
Gallium nitride switches far faster than silicon, which is why it appears in phone chargers, 5G base stations, radar and satellite power systems.
Where it is in the Earth
Gallium is not a mineral in its own right. Unlike copper or gold, which form discrete ore minerals that can be selectively concentrated, gallium exists only as a trace impurity lodged inside the crystal structures of other minerals. The two host minerals that matter commercially are gibbsite and boehmite — the aluminium hydroxide and oxyhydroxide minerals that make up bauxite — and sphalerite, the zinc sulfide mineral that is the world's principal source of zinc. In both cases, gallium atoms substitute for aluminium or zinc atoms in the crystal lattice because their ionic radii are similar enough to allow the substitution. The concentrations involved are minute: gallium in bauxite is typically measured in parts per million relative to the aluminium present.
Bauxite forms in tropical and subtropical climates through a process called laterisation. When aluminium-bearing rocks are subjected to intense weathering over long periods, silica and most other elements are progressively leached away, leaving a residue enriched in aluminium hydroxide minerals. Because gallium behaves geochemically similarly to aluminium, it concentrates alongside aluminium during this weathering. The result is that wherever thick, high-aluminium bauxite deposits formed — across West Africa, Australia, the Caribbean and parts of South-East Asia — gallium is also present, albeit at trace levels. The same laterisation process that creates commercial bauxite is therefore the same process that creates any future gallium resource, even though gallium was never the target.
Sphalerite deposits, by contrast, form in entirely different geological settings: hydrothermal veins and sediment-hosted massive sulfide bodies, where metal-bearing fluids circulated through the crust and deposited zinc, lead and iron sulfides. Gallium follows zinc into sphalerite for the same substitution reasons, and some zinc districts carry appreciably higher gallium concentrations than others, though the variation is poorly characterised in public literature. The global distribution of gallium therefore mirrors the combined geography of bauxite and zinc deposits, but the amount recoverable depends on what happens in the processing plant, not in the mine.
Getting it out
Because gallium has no mine of its own, the question of how it is mined has no direct answer. The bauxite that carries most of the world's gallium is extracted by open-pit mining: the thin topsoil and clay overburden above the bauxite horizon is stripped away, the ore is dug out with excavators and shovels, and it is trucked or conveyor-belted to a crushing facility. The operations are large and relatively shallow. The gallium content of the bauxite is not a factor in the mining decision at all — the mine exists for aluminium, and gallium comes along for the ride.
What this means in practice is that the quantity of gallium potentially available to the world is enormous, dwarfing what is actually recovered. Every tonne of bauxite processed through an alumina refinery contains some gallium, but that gallium is only captured if the refinery is equipped to extract it and the economics make doing so worthwhile. Most refineries, historically, have not bothered. The same logic applies to zinc smelters processing sphalerite concentrates: gallium is present in the feed material, but recovering it requires additional processing steps that most smelters do not operate. The effective grade of gallium as a recoverable product is therefore determined more by refinery configuration and operating decisions than by the geological grade of the host ore.
There is no waste-rock calculation for gallium in the way there would be for a primary metal mine. The host ore — bauxite or zinc sulfide — is moved and processed regardless. Gallium recovery is an incremental activity layered on top of an existing industrial process, which is both its economic advantage and the source of its structural vulnerability.
What pulls on it
The applications that consume gallium all depend on the same underlying property: gallium forms compound semiconductors — most importantly gallium arsenide (GaAs) and gallium nitride (GaN) — with electronic and optical characteristics that silicon cannot replicate. Silicon remains the dominant material for general-purpose computing, but it struggles at high frequencies, high temperatures and at the wavelengths used in light emission. Gallium-based compounds handle all three better. GaN transistors switch far faster and at higher voltages than silicon equivalents, which is why GaN has become the material of choice for power conversion in compact chargers, for the amplifiers inside 5G base stations and for the transmit-receive modules in radar systems. GaAs remains important for radio-frequency front-end components in mobile handsets and for solar cells used in space, where its high efficiency per unit area justifies the cost premium over silicon.
The end markets listed for gallium span a wide range, but they share a common thread: they are all situations where the performance gap between gallium compounds and silicon justifies the higher material cost. LEDs and laser diodes rely on gallium compounds for light emission — silicon does not emit light efficiently because of the way its electronic band structure is arranged. CIGS thin-film solar cells use gallium as a dopant to tune the semiconductor's light-absorption characteristics. As power electronics migrate toward higher frequencies and higher power densities — driven by electrification, data centre efficiency requirements and defence electronics — the applications pulling on gallium tend to grow rather than shrink.
A sharp change in demand would most plausibly come from one of two directions. The first is a faster-than-expected adoption of GaN in power electronics and 5G infrastructure, pulling demand up. The second is a technological shift that reduces the gallium content per device — as has happened historically when manufacturers found ways to thin wafers or recover and reuse kerf losses from wafer slicing. The defence and radar segment is relatively insensitive to material cost and would be among the last to substitute away. Consumer electronics are more price-sensitive but have few practical alternatives at the frequencies involved.
Turning ore into product 수준 3
The recovery of primary gallium begins inside the Bayer process, the standard industrial method for refining bauxite into alumina (aluminium oxide) ahead of smelting. In the Bayer process, crushed bauxite is digested in hot concentrated sodium hydroxide solution, which dissolves the aluminium hydroxide minerals into a sodium aluminate liquor. Gallium, being chemically similar to aluminium, dissolves alongside it. The undissolved residue — red mud — is separated, and the aluminate liquor is seeded to precipitate aluminium hydroxide crystals, which are then calcined to produce alumina. Over repeated cycles of digestion and precipitation, gallium accumulates in the circulating Bayer liquor because it does not precipitate as readily as aluminium. This concentration effect in the liquor is what makes recovery feasible: the gallium is, in effect, pre-concentrated by the normal operation of the alumina plant.
Once gallium has built up to a sufficient level in the Bayer liquor, it is extracted by one of several routes: solvent extraction, ion exchange, or electrochemical deposition. The output is crude gallium, often described as low-grade metal, which is then further refined to higher purity grades. Electronics applications — particularly compound semiconductors — require exceptionally pure material. The semiconductor industry works with gallium expressed as a number of nines: 6N means 99.9999 percent pure, 7N means 99.99999 percent. Achieving these grades requires multiple passes through zone refining or other purification steps, each of which adds cost and removes small quantities of material as impurity-bearing waste. The losses at each step accumulate, so the yield from Bayer liquor to finished 6N or 7N gallium is a fraction of the gallium that entered the refinery in the bauxite. Recovery from zinc processing follows a different route — gallium is typically captured in the leach solutions and flue dusts of zinc hydrometallurgy — but the principle of accumulation and selective extraction is the same.
The cost structure of primary gallium is therefore unusual. The mining and ore-processing costs are borne by the aluminium or zinc business; the gallium producer's direct costs are the extraction and refining steps applied to liquor or residue streams that would exist regardless. This means gallium production can be expanded or curtailed in response to gallium prices without affecting the host refinery's operation, but it also means that a refinery owner who judges gallium recovery uneconomic will simply discharge the gallium into tailings. The decision about how much gallium to capture is made separately from — and often indifferently to — the decisions made by the semiconductor industry that ultimately depends on it.
Substitution and recycling 수준 3
Substitution for gallium in compound semiconductors is technically possible in some applications and essentially impractical in others. Silicon carbide (SiC) competes with GaN in power electronics, particularly at the highest voltages, and both materials are advancing simultaneously. In the radio-frequency domain, indium phosphide offers performance advantages over GaAs at millimetre-wave frequencies, and silicon-on-insulator technologies have displaced GaAs in some lower-frequency mobile handset applications where the cost difference was decisive. Each substitution carries a performance trade-off: the replacement material either operates less efficiently, requires more die area, generates more heat, or is itself a critical or constrained material. Indium, for instance, is no less supply-constrained than gallium, and SiC depends on a separate supply chain with its own concentration risks.
Recycling of gallium is technically achievable but commercially limited. The largest recoverable stream is the kerf — the material lost when semiconductor wafers are cut from ingots by wire saws — together with rejected or off-specification wafers and epitaxial growth waste. Some of this is collected and reprocessed, particularly in Japan and Germany, where wafer manufacturers have established internal recycling loops. However, once gallium has been incorporated into a finished device — a packaged LED, a radar module, a phone charger — recovery becomes extremely difficult. The gallium content per device is small, the devices are encapsulated in plastics and ceramics, and the collection infrastructure for consumer electronics is not designed to segregate gallium-bearing components at the level required for economic recovery. The recycling rate for gallium from end-of-life products is, by general understanding in the literature, very low. The principal constraint is not the chemistry of recovery but the economics of collection: the gallium in any individual device is worth very little, and the sorting required to accumulate meaningful quantities is costly relative to the value recovered.
Where the chain is fragile 수준 4
The production figures in the table make the supply picture plain. In 2025, China accounted for 900,000 kilograms of primary gallium production, a figure that equals the reported world total for that year. Russia and Japan together contributed 9,000 kilograms — roughly one percent of the Chinese figure. The United States reported no primary production, and the source withholds figures for other countries. The United States Geological Survey recorded U.S. net import reliance at 100 percent for 2025. This is a degree of single-country supply concentration that has few parallels among industrial metals. The concentration is not primarily the result of China having exceptional gallium geology; it reflects sustained investment in Bayer-liquor extraction infrastructure across Chinese alumina refineries, combined with the willingness of Chinese operators to produce gallium at prices that have historically deterred investment elsewhere.
The by-product structure compounds the fragility. Primary gallium output is governed by alumina and zinc production volumes, not by gallium demand. If alumina refineries outside China were equipped to recover gallium from their Bayer liquor — as the Western Australian refineries listed in the processing plants table theoretically could — the feedstock already exists. The constraint is the capital investment in extraction circuits and the uncertainty about whether gallium prices would remain high enough over a refinery's operating life to justify that investment. Lead times for adding gallium recovery to an existing alumina refinery are shorter than for building a primary mine, but they are not trivial: engineering, procurement, permitting and commissioning of new solvent-extraction or electrochemical circuits typically runs to several years. During that interval, a supply disruption cannot be bridged by switching suppliers.
A further uncertainty in published figures concerns the definition of what is being counted. The unit basis given here is primary low-grade gallium, meaning metal recovered from Bayer liquor and zinc processing before further refining. Secondary gallium — recovered from manufacturing scrap, wafer kerf and internal recycling loops — is reported inconsistently across national statistics and is sometimes aggregated into primary figures and sometimes excluded entirely. This makes year-on-year comparisons across different data sources unreliable and means that the apparent dominance of Chinese production may partly reflect differences in what is being measured rather than purely in what is being produced. The price series in the table, expressed as average unit values of imports, reflects the traded market for refined metal and is subject to its own distortions: thin trading volumes, bilateral contracts not captured in customs data, and the fact that some gallium moves embedded in wafers rather than as metal, which may place it under different customs headings altogether.
암석 내 산출 위치
전체 광석 광물 →실제로 이를 함유하는 광물은 다음과 같다: gallium. 광체(orebody)란 채굴 비용을 충당할 만큼 특정 광물이 충분히 농집된 광상을 말한다.
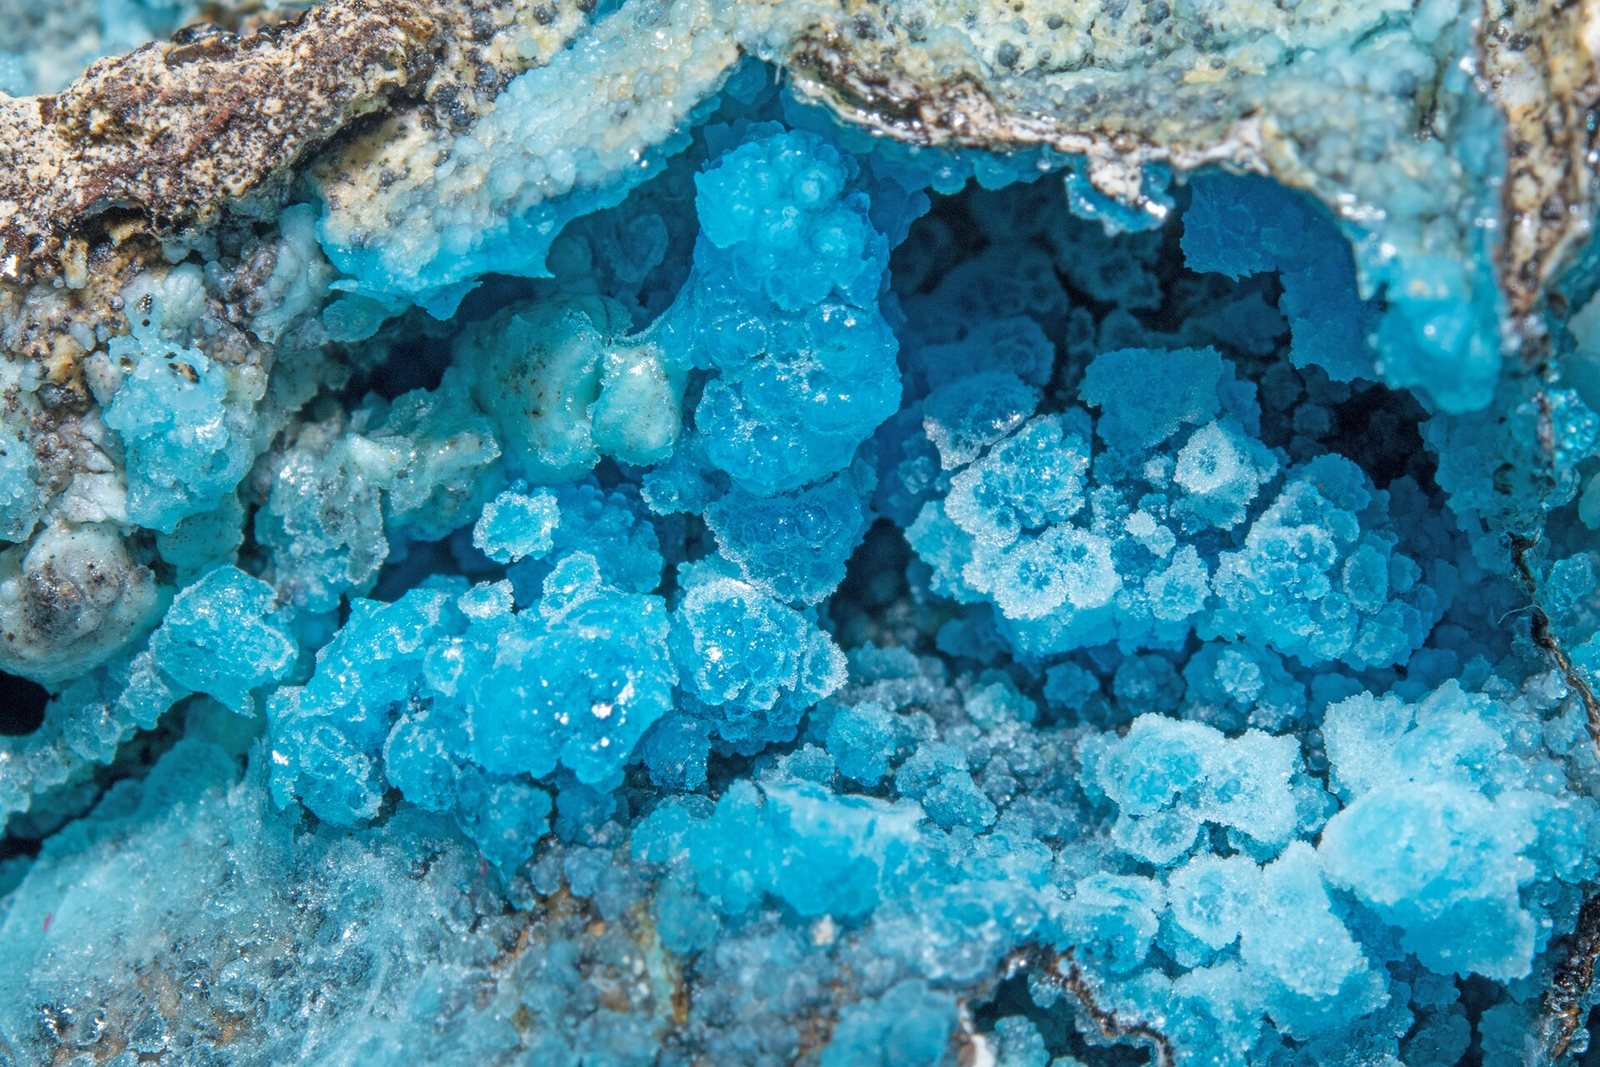
Bauxite (gibbsite/boehmite)
Not one mineral but a rock of aluminium hydroxides left after millions of years of tropical weathering.
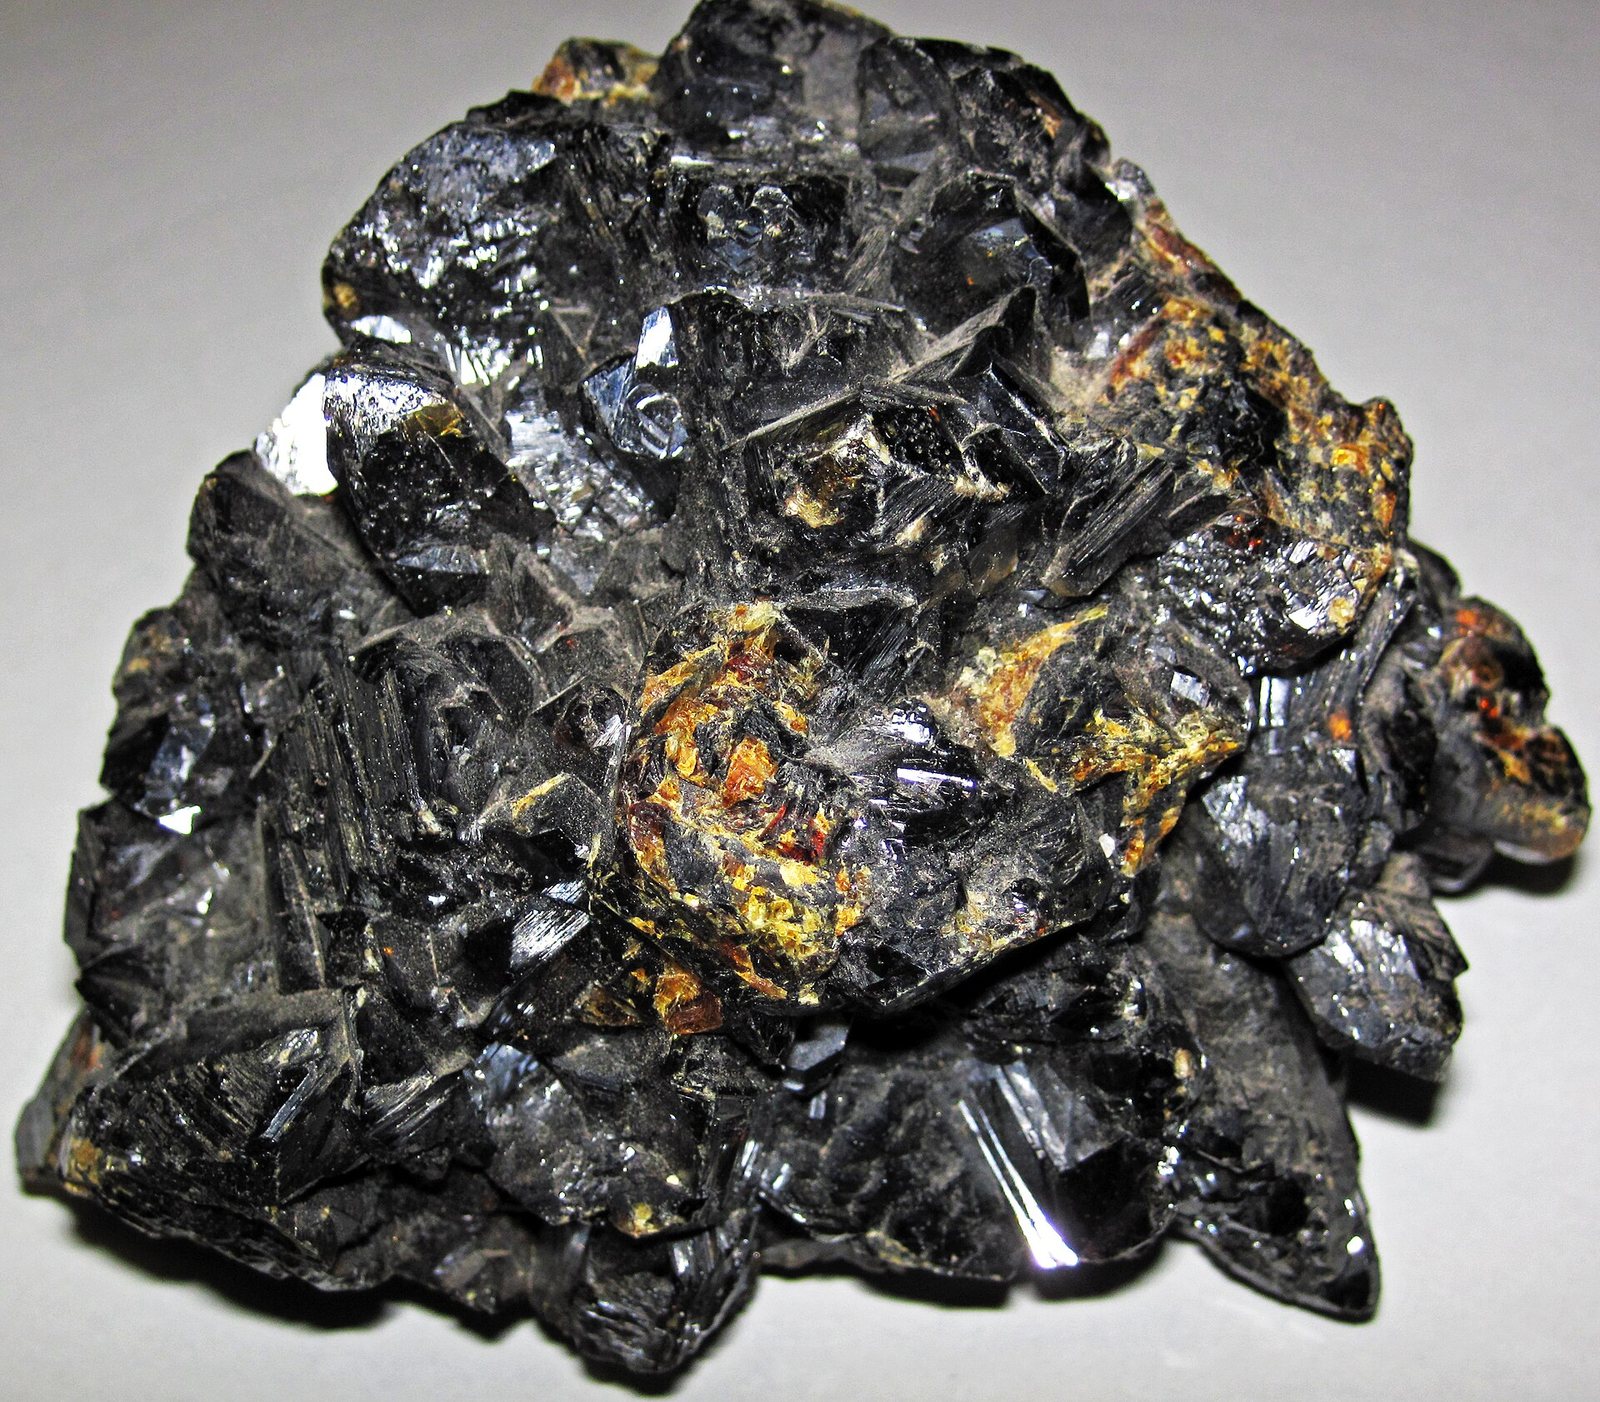
Sphalerite
The main zinc ore, and the world's main source of indium, germanium and gallium as trace substitutions in its lattice.
생산 주체
지도에서 보기 →Primary production
Primary productionkilograms 2025 (추정치) 세계 합계 900,000 kilograms
USGS Mineral Commodity Summaries 2026 · Primary low-grade gallium production; recovered as a by-product of alumina refining and zinc processing. · 출처 ↗
나머지 열을 보려면 표를 옆으로 스크롤하십시오.
| 국가 | 생산 | 세계 비중 |
|---|---|---|
| China | 900,000 | 100.0% |
| Russia | 6,000 | 0.7% |
| Japan | 3,000 | 0.3% |
| Other countries | Zero | — |
| United States | Zero | — |
| 세계 합계 | 900,000 | 100% |
'비공개'는 USGS가 개별 기업의 데이터 노출을 막기 위해 수치를 억제한 것으로, 0을 의미하지 않습니다. 출처가 각 수치를 독립적으로 반올림하고 '기타 국가' 항목을 항상 별도로 구분하지는 않기 때문에, 국가별 합계가 세계 합계와 일치하지 않을 수 있습니다.
가격
average unit value of imports, dollars per kilogram
연간 평균dollars per kilogram
기준: average unit value of imports, dollars per kilogram. 다음 자료에 게재된 연간 평균 USGS Mineral Commodity Summaries 2026 · 출처 ↗. 이 수치는 기준 연간 평균값이며, 실시간 시장 가격이 아니다.
처리·정련 지점
| 시설 | 종류 | 단계 | 국가 | 역할 |
|---|---|---|---|---|
| Bayer-Process Alumina Refineries, Western Australia | 정련소 | 가공 | Australia | 산출물 |
용도
전체 최종 시장 →| 최종 시장 | 거기에서의 기능 | 중요도 |
|---|---|---|
| Aerospace & Defence | Radar transmit-receive modules | 정의 |
| Semiconductors | Compound semiconductors for RF and power | 정의 |
| Data Centres & AI | High-efficiency power conversion | 중요 |
| Consumer Electronics | LED backlighting and RF front end | 중요 |
| Robotics & Automation | Efficient motor drive electronics | 중요 |
| Solar Power | CIGS thin film and cell doping | 현재 |
기술별 소요량
| 기술 | 수량 | 고시 가격 | 기준 |
|---|---|---|---|
| Gallium Nitride Power Device Grams; the constraint is refining capacity, not tonnage. | 미량 | per device | Substrate and epitaxial layer |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. 재료 계산기에서 임의의 규모로 이 수치를 계산하십시오. →
수출 통제
| 국가 | 지배력 | 적용 대상 |
|---|---|---|
| China | Export licensing requirement for materials and technologies | Antimony (2024), bismuth (2025), synthesized diamond (2025), gallium (2023), germanium (2023), graphite (2023), indium (2025), magnesium materials (2024), molybdenum (2025), rare earths (2025), silver (2026), tellurium (2025), tungsten (2025), and items related to lithium batteries and artificial graphite anode materials (2025). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.