これは何か
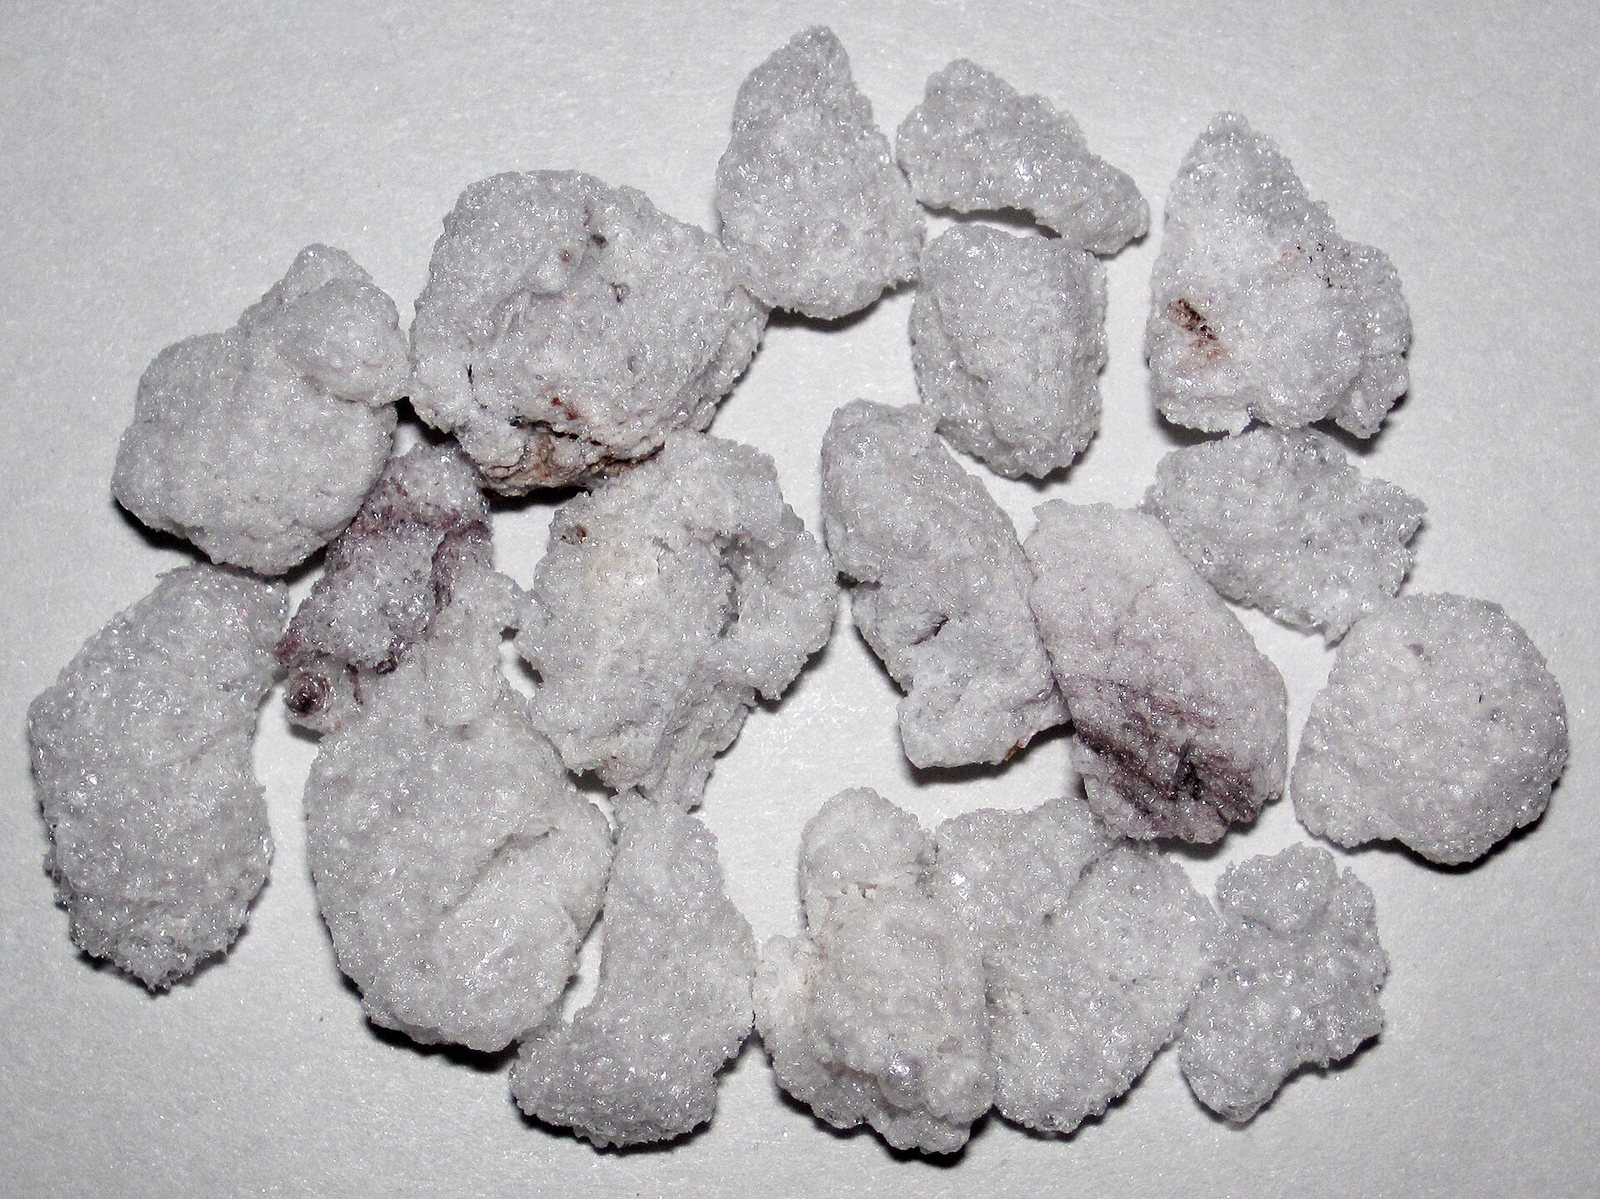
A volcanic glass with water trapped inside it that pops like popcorn when heated, expanding to many times its size.
なぜ重要なのか
Expanded perlite is one of the cheapest ways to make something light and insulating — in plaster, in filters, and in the growing medium under most greenhouse crops.
Where it is in the Earth
Perlite is a form of volcanic glass — rhyolitic in composition, meaning it formed from silica-rich magma. When that magma erupted and cooled rapidly at the surface or near it, the resulting glassy rock trapped a small amount of water within its structure. That water is not liquid; it is chemically bound within the glass matrix, typically at a few per cent by weight. This combination of glassy structure and bound water is what makes perlite behave so differently from ordinary rock when it is heated.
The deposits tend to occur in geologically young volcanic arcs and rift zones, where silicic eruptions have taken place within the last few tens of millions of years. Older deposits are less common because volcanic glass is metastable: over geological time, groundwater and heat convert it into clay minerals and other secondary phases, destroying the glassy texture that gives perlite its commercial character. This is why the world's largest and most reliable deposits cluster around active or recently active tectonic margins — the Aegean region, the western United States, central China, and parts of Central America and the Pacific.
Not all volcanic glass qualifies. The deposit must be thick enough, laterally continuous enough, and close enough to the surface to mine economically. Hydration must be reasonably uniform, because pockets of devitrified or otherwise altered glass within a deposit reduce the expansion ratio of the product and must either be blended away or discarded. Greece's deposits on the island of Milos are among the largest and most homogeneous known, which explains why Greece holds by far the largest reported reserves and exports crude ore worldwide despite being a relatively small country.
Getting it out
Perlite is almost always mined by open-pit methods. The rock is close to the surface, relatively soft for a silicate, and occurs in large tabular or dome-shaped bodies that suit a simple strip-and-bench approach. Heavy equipment removes any overburden — soil, weathered rock, or altered volcanic material that will not expand usefully — and the crude perlite is then drilled, blasted, and loaded into trucks. Because the deposits are generally near-surface and the rock is not exceptionally hard, the ratio of waste moved to ore produced is lower than in many hard-rock mining operations, though it varies considerably with the geometry of each deposit and the thickness of the overburden.
Grade in perlite mining is expressed differently from most metallic ores. What matters is not the concentration of a target element but the expansion ratio — how many times the rock's volume increases when it is rapidly heated. A good crude perlite will expand to many times its original volume; material that expands less may still be mined but commands a lower price or is blended with better material. Moisture content of the crude ore also matters in practice, because excess surface moisture interferes with the furnace process downstream. For this reason, crude ore is often stockpiled and allowed to air-dry before shipment or processing.
Because expanded perlite is largely air by volume, it is uneconomic to ship long distances in its expanded state. The standard commercial logic is therefore to export crude ore and expand it at or near the point of use. This shapes the entire geography of the industry: a country like Greece ships crude ore in bulk across the world, while expansion plants are built close to the construction sites, horticultural operations, and filtration facilities that consume the product.
What pulls on it
Perlite is consumed in three broad areas: construction, horticulture, and industrial filtration. In construction it appears as a lightweight aggregate in plaster and ceiling tiles, and as a loose-fill insulation in cavity walls and around cryogenic tanks. In horticulture it is used as a growing medium component — mixed with peat, coir, or other substrates — because it retains air around plant roots while resisting compaction and biological decay. In filtration it acts as a filter aid, forming a porous cake through which liquids such as beer, wine, edible oils, and pharmaceuticals are clarified. These three markets pull on perlite for quite different reasons, which means demand is spread across sectors with different economic cycles.
Construction demand follows the level of building activity and renovation, particularly in regions where lightweight plaster systems are standard practice. Horticultural demand has been growing as controlled-environment agriculture — greenhouse cultivation in particular — expands to supply urban markets and to extend growing seasons in northern climates. The inert, repeatable character of perlite makes it attractive where growers need a substrate that does not introduce pathogens or variable nutrients. Filtration demand is relatively stable, tied to the production volumes of the food and beverage industries, though it is subject to competition from alternative filter aids.
A sharp change in demand would most likely follow either a major shift in construction methods away from lightweight plaster systems, or a sustained substitution of alternative substrates in horticulture. Neither appears imminent in the near term, but the horticultural sector is actively evaluating materials such as coir and expanded clay aggregate, and any significant cost advantage for those alternatives could erode perlite's position. Demand is also sensitive to energy costs at the expansion plant level: because the crude ore must be expanded near the point of use, a sharp rise in local energy prices can make the expanded product less competitive against substitutes.
Turning ore into product レベル 3
The core processing step is straightforward in principle: crude perlite is crushed and sized to a target particle range, dried to remove surface moisture, and then fed through a vertical furnace where it is exposed to temperatures typically in the range that causes the bound water to flash to steam. That steam cannot escape fast enough to fracture the softened glass, so it expands the particles in place, producing the low-density, cellular product that reaches the customer. The expansion happens extremely rapidly, and the furnace throughput per unit of floor area is high relative to most mineral processing operations. The key process variables are particle size distribution entering the furnace, feed moisture, furnace temperature profile, and residence time; deviations in any of these shift the bulk density of the product away from specification.
Sizing before expansion is important because the end market is sensitive to particle size. Horticultural perlite, plaster aggregate, and filtration-grade perlite each require different size fractions of the expanded product, and it is more efficient to size the dense crude ore than to size the fragile expanded material afterward, though some classification of the expanded product does occur. Fines generated during crushing are a process loss: particles below a certain size do not expand usefully and may report to waste or be used in lower-value applications such as loose-fill insulation. The cost structure of an expansion plant is dominated by energy, because the furnace runs continuously at high temperature; fuel cost is therefore a significant variable in the economics of different production locations.
There is no smelting, leaching, or chemical refining involved. Perlite processing is entirely physical and thermal, which keeps the capital intensity moderate and the environmental footprint relatively contained compared with most mineral processing chains. The main waste stream is crusher fines and oversize reject from the crude ore, neither of which requires chemical treatment. Dust management is the principal occupational and environmental concern, as with most operations handling fine silicate particles.
Substitution and recycling レベル 3
In construction plaster, vermiculite — another thermally expanded mineral, in that case a hydrated phyllosilicate — can substitute for perlite in many applications, though it tends to be denser and more expensive, and its supply chain has been complicated historically by association with asbestiform minerals in some deposits. Expanded clay aggregate (lightweight aggregate produced by rotary kiln) can replace perlite in some structural and insulating applications but requires more energy to produce and is considerably heavier in bulk. In loose-fill cavity insulation, mineral wool and foam materials compete, with performance characteristics that differ mainly in moisture behaviour and installation method.
In horticulture the principal alternatives are expanded clay pebbles, coir fibre, rockwool (mineral wool formed into slabs or blocks), and rice hulls. Each carries trade-offs: rockwool has good air-to-water ratio characteristics but raises questions around end-of-life disposal; coir is renewable but variable in salt content and pH; expanded clay is reusable after sterilisation but heavier to handle and transport. Perlite's position rests on being inert, light, inexpensive, and widely available rather than on any single property that alternatives cannot replicate at all.
In filtration, diatomaceous earth (the siliceous remains of microscopic algae, also called diatomite) is the closest functional substitute and in fact competes directly in the same applications. Synthetic filter aids, membrane filtration systems, and centrifugal clarification can replace both perlite and diatomite in some industrial settings, though often at higher capital cost. Recycling of spent filter cake is limited: once the perlite has been used to clarify a liquid, it is typically contaminated with organic solids and spent immediately to landfill or, in some cases, to agricultural land as a soil amendment. This is a genuine material loss, and it reflects the low unit value of perlite rather than any technical barrier to reuse — washing and re-using spent filter cake is rarely economic at current prices.
Where the chain is fragile レベル 4
The geographic concentration of perlite production is real but should be read carefully. China and Turkey together account for the largest share of world output, and Greece — though a smaller producer by annual tonnage — holds by far the largest reported reserves. Turkey's reserves are reported as withheld by the source, which means the published world reserve total is also withheld and the apparent reserve picture is incomplete. This is a recurring issue in perlite data: several significant producing countries, including Turkey, Mexico, New Zealand, and the Philippines, have no published reserve figure, so comparisons between reserve-to-production ratios across countries are not straightforward. Researchers using these figures should treat the reserve table as a partial picture rather than a comprehensive accounting.
The processing structure introduces a different kind of fragility. Because expansion plants are built close to end markets and fed by crude ore shipped from a relatively small number of mines, a disruption at a major exporting operation — whether from permitting, labour, geological, or political causes — would take time to compensate. New expansion capacity can be brought online in months, but finding a new crude ore supply of consistent quality and arranging bulk shipping logistics takes considerably longer. The United States imports a material portion of its crude ore from Greece and China, as the U.S. facts section shows, meaning domestic expansion plants are partially dependent on international supply continuity.
The statistical basis of published production figures adds a further layer of uncertainty. Production is reported as gross weight of crude ore, not as the volume or weight of expanded product that reaches end users. Because the expansion ratio varies with ore quality and processing conditions, the relationship between reported crude tonnage and actual service capacity in any given market is not fixed. Different national statistical agencies apply different definitions of what constitutes reportable crude perlite — some include lower-grade material, some do not — which is one reason why figures from different published sources for the same country and year frequently disagree. Any analysis that combines figures from multiple sources without reconciling their unit bases and definitions risks compounding these inconsistencies.
生産者
地図で見る →Production
Productionthousand metric tons 2025 (推定値) 世界合計 4,600 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of crude perlite, not the expanded product. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| China | 1,500 | 32.6% |
| Turkey | 1,400 | 30.4% |
| Greece | 840.0 | 18.3% |
| United States | 460.0 | 10.0% |
| Hungary | 80.00 | 1.7% |
| Iran | 70.00 | 1.5% |
| Slovakia | 40.00 | 0.9% |
| Georgia | 40.00 | 0.9% |
| Argentina | 30.00 | 0.7% |
| Mexico | 30.00 | 0.7% |
| Armenia | 30.00 | 0.7% |
| Philippines | 20.00 | 0.4% |
| New Zealand | 20.00 | 0.4% |
| South Africa | 10.00 | 0.2% |
| Other countries | 10.00 | 0.2% |
| 世界合計 | 4,600 | 100% |
「非開示」とは、個別企業のデータが特定されないようUSGSが数値を公表しなかったことを意味し、ゼロを意味するものではありません。出典が各数値を独立して丸め処理しており、「その他の国」の内訳を常に示しているわけではないため、各国の数値の合計が世界合計と一致しないことがあります。
埋蔵量の保有者
Reserves
Reservesthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| Greece | 180,000 | — |
| United States | 50,000 | — |
| China | 32,000 | — |
| Slovakia | 30,000 | — |
| Iran | 15,000 | — |
| New Zealand | Not applicable | — |
| Philippines | Not applicable | — |
| South Africa | Not applicable | — |
| Turkey | Not applicable | — |
| Other countries | Not applicable | — |
| Mexico | Not applicable | — |
| Argentina | Not applicable | — |
| Armenia | Not applicable | — |
| Georgia | Not applicable | — |
| Hungary | Not applicable | — |
| 世界合計 | Not applicable | 100% |
価格
average value, free on board mine, dollars per metric ton
年間平均dollars per metric ton
基準: average value, free on board mine, dollars per metric ton. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。