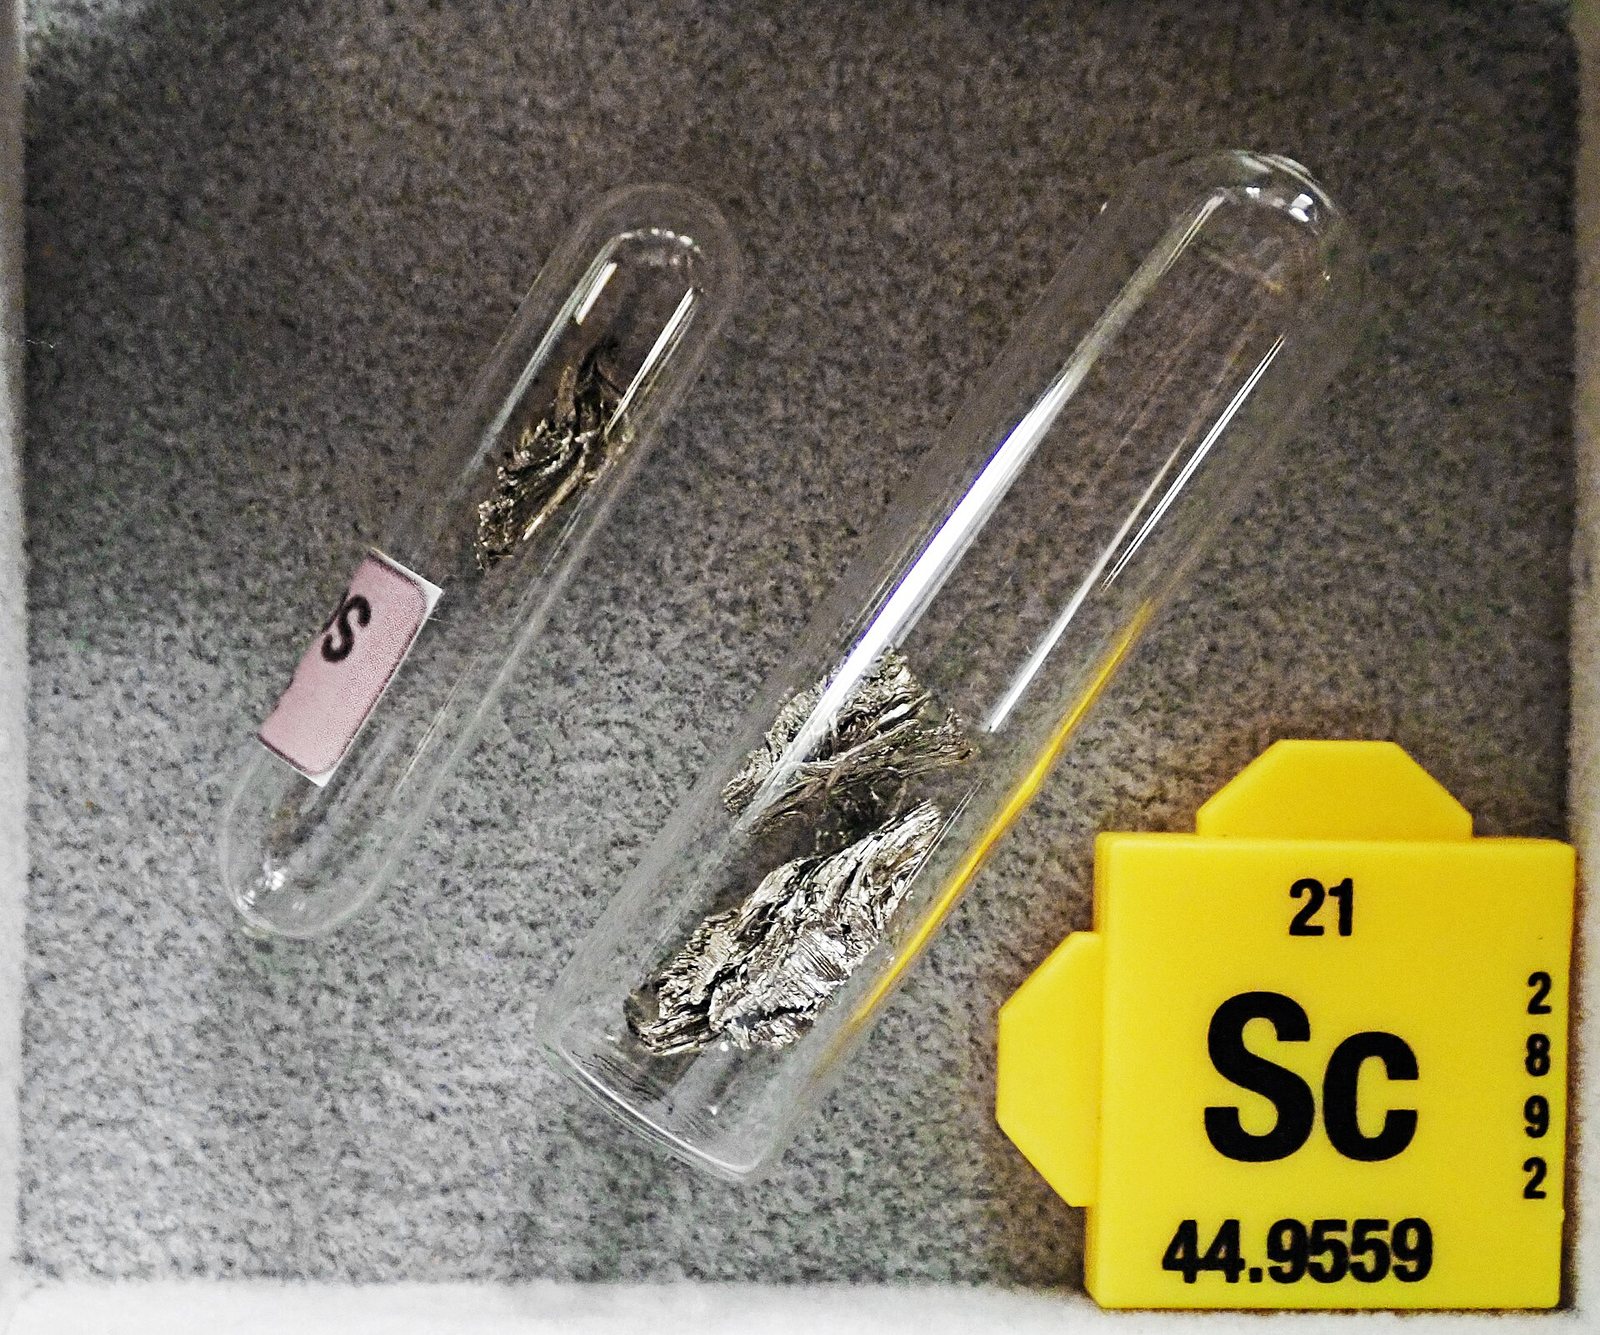
Wat is het?
A light metal that makes aluminium dramatically stronger and weldable — and which is produced in tonnes per year worldwide, not thousands of tonnes.
Waarom is het van belang?
Scandium-aluminium alloy is a genuinely better aerospace material that almost nobody can buy, because supply is a by-product trickle.
Where it is in the Earth
Scandium is one of the more abundant elements in the Earth's crust by weight, yet it is almost never found in a concentrated form. The reason is chemistry: scandium ions are small and carry a charge that allows them to substitute quietly into the crystal lattices of dozens of common rock-forming minerals — pyroxenes, garnets, and micas among them — without ever becoming the dominant ingredient in any of them. There is no common scandium mineral the way there is a copper mineral or an iron mineral. Instead, scandium disperses itself across much of the rock record at low, fairly uniform concentrations, which makes it geochemically common but economically elusive.
The deposits that carry enough scandium to attract attention are those where geological processes have done secondary work to concentrate it above background levels. Laterite profiles — the thick, chemically weathered crusts that develop over ultramafic rocks in tropical and subtropical climates — are the most important setting. When water percolates through these profiles over millions of years, it dissolves and removes many elements while leaving others behind. Scandium, along with nickel and cobalt, tends to be residually enriched in the lower, clay-rich portions of laterite sequences. This is also why scandium almost always appears alongside nickel and, separately, alongside titanium in ilmenite and zircon heavy-mineral sand deposits: it is a passenger in systems defined by other metals. Ion-adsorption clays, the deeply weathered granite profiles of southern China that are mined primarily for rare earth elements, carry scandium as a further minor component, adsorbed onto clay mineral surfaces alongside the rarer lanthanides.
Australia holds the largest reported reserves, and the geology there is consistent with this pattern: the Syerston deposit in New South Wales sits within a lateritised ultramafic intrusion. Most other significant concentrations are similarly tied to laterite nickel or titanium mineral-sand provinces, which explains both the geography of potential supply and the structural difficulty of ever treating scandium as anything other than a minor companion to something else.
Getting it out
Because scandium has no deposit type of its own, it is not mined for its own sake anywhere in the world at commercial scale. It arrives as a by-product — a trace constituent recovered from the processing streams of operations that exist to produce nickel, cobalt, titanium, aluminium, or rare earth elements. The world total production figure in the table above, reported in tonnes of scandium oxide per year, reflects this reality: the number is small enough that the U.S. Geological Survey reports it as a range rather than a single figure.
In practice, scandium reaches a refinery not because a mine was designed around it, but because some processing step — acid leaching of laterite ore, for instance — dissolves scandium along with the target metal, and someone has chosen to install additional circuits to capture it from the pregnant leach solution rather than let it pass into tailings. The grade of scandium in the host material is typically measured in parts per million, meaning that even after all the processing of a large nickel laterite, the total scandium recovered may be a small fraction of the plant's output by mass. The concept of waste-to-product ratio, which in conventional mining describes how many tonnes of rock must be moved per tonne of saleable product, translates here into a question of how much leach solution must be processed and how many additional chemical steps must be run to yield a kilogram of scandium oxide.
The consequence is that scandium supply is not governed by decisions about scandium. It is governed by decisions about nickel, titanium, or rare earths. If those host operations run at high throughput, scandium recovery is possible; if they curtail, scandium output falls regardless of demand or price for scandium itself. This structural dependence is the central fact about scandium supply and the reason the price history shown in the table above does not behave like that of a commodity with elastic supply.
What pulls on it
The uses of scandium divide neatly into two categories at very different scales. The larger potential use — stronger, more weldable aluminium alloys for aerospace structures, fuel systems, and defence applications — has been understood since the Soviet Union incorporated scandium-aluminium alloys into military aircraft frames. Small additions of scandium to aluminium refine the grain structure of the metal during solidification, which improves both strength and resistance to cracking during welding. The resulting alloys are genuinely superior to conventional high-strength aluminium in several respects. The reason this potential has not translated into mass adoption is supply: quantities available are insufficient to support high-volume aerospace manufacturing at acceptable certainty of delivery, and the price per kilogram of scandium oxide remains far above the threshold at which alloy use becomes routine.
The second category of use is as an electrolyte material in solid-oxide fuel cells (SOFCs). Scandia-stabilised zirconia — zirconium oxide doped with scandium oxide — conducts oxygen ions at lower operating temperatures than conventional yttria-stabilised zirconia, which is the dominant electrolyte material. This efficiency advantage is real but comes at the cost of using a scarce and expensive oxide. SOFC manufacturers have consequently remained cautious about committing to scandia-stabilised formulations at scale, and the market remains small. Ceramics and phosphors account for further minor uses.
For demand to shift sharply upward, at least one of two things would need to happen. Either aerospace manufacturers would need to secure long-term, reliable supply contracts at volumes sufficient to qualify scandium-aluminium alloys in certified structures — a process that takes years — or the SOFC industry would need to grow to a scale where scandia-stabilised electrolytes justify dedicated supply chains. Either pathway requires supply to become reliably available first, which creates a circular problem: supply does not scale without demand, and demand does not commit without supply.
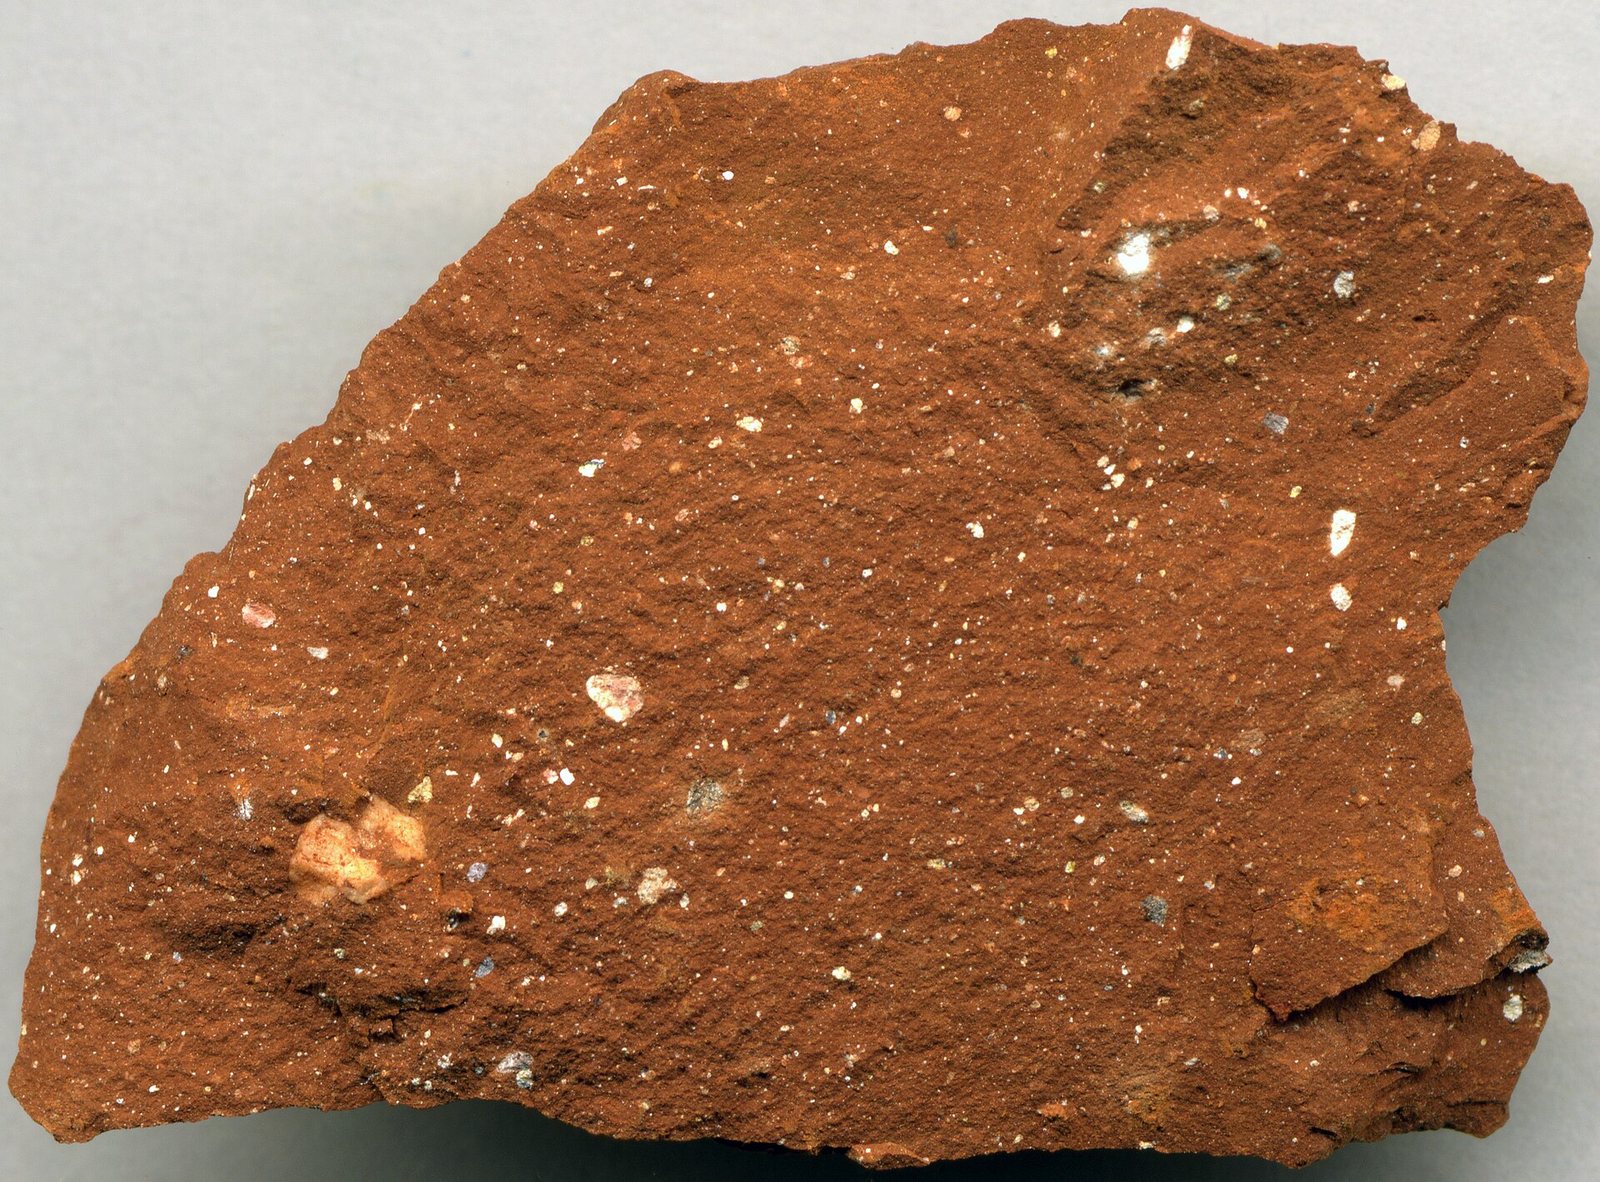
Waar het in het gesteente vandaan komt
Alle ertsmineralen →Dit zijn de mineralen die daadwerkelijk scandium. Een afzetting is alleen een ertslichaam als een van beide voldoende geconcentreerd is om de winning ervan te bekostigen.
Wie het produceert
Bekijk het op een kaart →global production
global productionmetric tons 2025 (geschat) Wereldtotaal 80.00 metric tons
USGS Mineral Commodity Summaries 2026 · World production is reported in tonnes of scandium oxide and is small enough that USGS gives a range. · bron ↗
Schuif de tabel zijwaarts voor de overige kolommen.
| Land | Productie | Aandeel van de wereld |
|---|---|---|
| Wereldtotaal | 80.00 | 100% |
"Ingehouden" betekent dat de USGS het cijfer heeft onderdrukt om gegevens van een individueel bedrijf niet prijs te geven — het betekent niet nul. Landrijen tellen niet altijd op tot het wereldtotaal, omdat de bron elk cijfer afzonderlijk afrondt en niet altijd een regel "overige landen" uitsplitst.
Wie de reserves bezit
Australia’s reserves (accessible Economic Demonstrated Resources)
Australia’s reserves (accessible Economic Demonstrated Resources)metric tons 2023
USGS Mineral Commodity Summaries 2026 · bron ↗
| Land | Reserves | Aandeel van de wereld |
|---|---|---|
| Australia | 34,000 | — |
Prijs
global, dollars per kilogram, range of average values: Scandium-aluminum alloy, ingot,scandium 2%, 1- to 30-kilogram lot size
Jaargemiddeldedollars per kilogram
Grondslag: global, dollars per kilogram, range of average values: Scandium-aluminum alloy, ingot,scandium 2%, 1- to 30-kilogram lot size. Jaargemiddelden zoals gepubliceerd in USGS Mineral Commodity Summaries 2026 · bron ↗. Dit zijn referentiejaargemiddelden, geen live marktkoers.
global, dollars per kilogram, range of average values: Scandium metal, ingot, 99.999% purity, 1- to 10-kilogram lot size
Jaargemiddeldedollars per kilogram
Grondslag: global, dollars per kilogram, range of average values: Scandium metal, ingot, 99.999% purity, 1- to 10-kilogram lot size. Jaargemiddelden zoals gepubliceerd in USGS Mineral Commodity Summaries 2026 · bron ↗. Dit zijn referentiejaargemiddelden, geen live marktkoers.
Waarvoor het wordt gebruikt
Alle eindmarkten →| Eindmarkt | Wat het daar doet | Belang |
|---|---|---|
| Aerospace & Defence | High-strength aluminium alloy | Heden |
| Hydrogen & Electrolysis | Solid-oxide cell electrolyte | Heden |