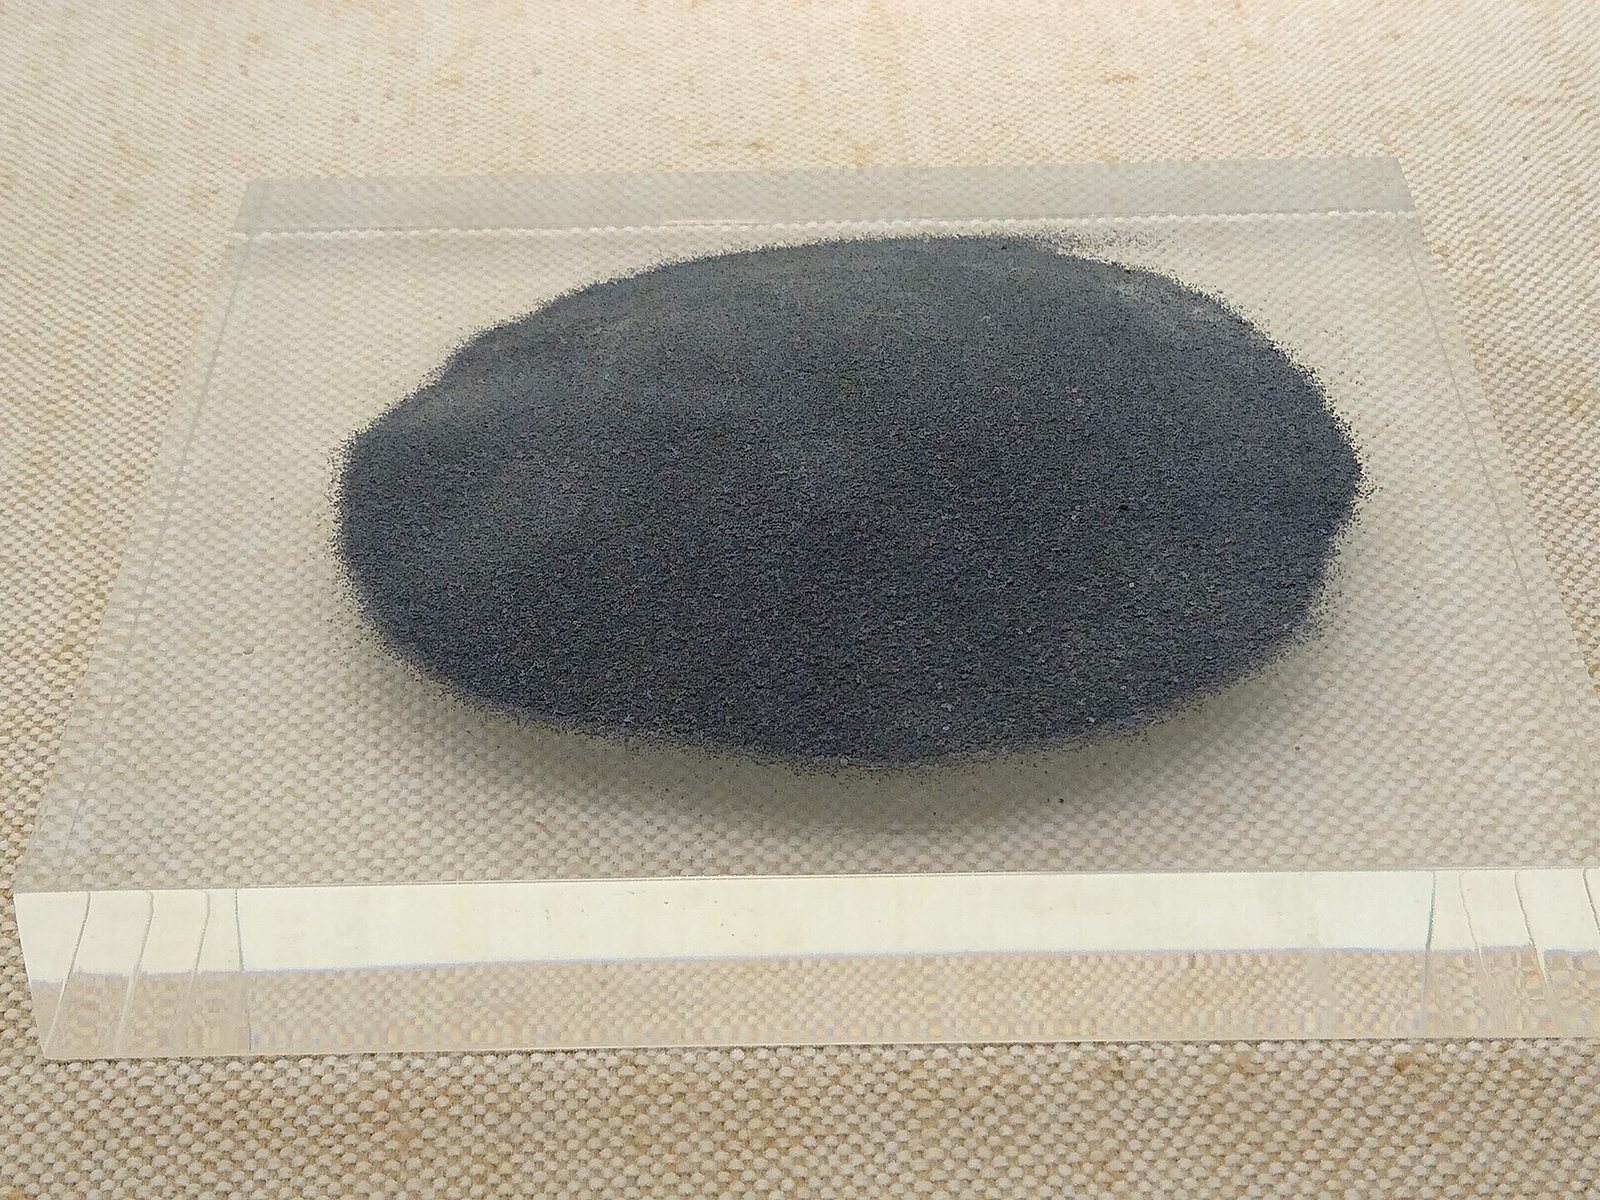
What is it?
Black beach sand — ilmenite and rutile — that is the starting point both for titanium metal and for the white pigment in paint.
Why does it matter?
More than 90% of this ore never becomes metal; it becomes titanium dioxide, the whitest white in industrial use.
Where it is in the Earth
Titanium is the ninth most abundant element in the Earth's crust, yet it rarely occurs in concentrations high enough to mine economically. The two minerals that matter commercially are ilmenite, an iron-titanium oxide, and rutile, which is nearly pure titanium dioxide. Both crystallise at high temperatures within igneous and metamorphic rocks — principally anorthosite (a coarse-grained rock made mostly of feldspar), gabbro, and some granites. In these primary settings the titanium minerals are disseminated through the host rock in proportions that are generally too low and too expensive to process directly.
What makes titanium mineral deposits actually mineable, in most cases, is a secondary process: weathering and erosion. Over geological time, the host rock breaks down, and because ilmenite and rutile are both dense and chemically resistant, they survive the journey that destroys most other minerals. Rivers carry the grains to the coast, where wave action and longshore drift sort them by density, concentrating the heavy minerals in layers within beach sands. These are called heavy mineral sand deposits, or simply mineral sands, and they account for the great majority of world production. The economically important shorelines are ancient ones — sometimes tens of millions of years old and now stranded inland as sea levels have changed — which is why major deposits appear in the coastal plains of eastern Australia, the eastern seaboard of Africa, the Atlantic coast of Senegal, and similar settings elsewhere.
A different and important deposit type occurs in anorthosite bodies, where ilmenite occurs in sufficient concentration to mine the primary rock rather than waiting for erosion to do the work. Norway and parts of Canada host deposits of this kind. China's large ilmenite production comes mainly from titaniferous magnetite — an iron ore that carries titanium as an associated mineral — in the Panzhihua region of Sichuan province, which differs in character from either the mineral sands or the anorthosite deposits and influences both the processing route and the product quality.
Getting it out
The method used to mine a deposit depends almost entirely on its physical form. Mineral sand deposits typically lie at or very near the surface, often beneath a thin layer of soil or dune sand, and they are mined by open-cut methods — essentially stripping away the overburden and excavating the ore sand with earthmoving equipment or, where the ground is wet enough, with a floating dredge. A dredge is a large vessel that excavates sand from beneath a pond of water it creates as it advances, feeds the material through a concentrating plant mounted on the same vessel, and deposits the tailings — the sand that no longer contains useful minerals — behind it. The mined-out land is progressively rehabilitated as the dredge moves forward, which is one reason mineral sand operations have a somewhat different environmental profile from hard-rock mines.
The proportion of heavy minerals in the ore — the heavy mineral content, or HMC — varies considerably between deposits. In the richest zones it can reach several per cent, while in leaner deposits it is a small fraction of one per cent. This means a large volume of barren sand moves through the plant for every tonne of concentrate produced, though because the ore requires no blasting and no crushing, the energy cost per tonne of ore processed tends to be lower than in hard-rock mining. The useful mineral proportion of the heavy mineral fraction matters as much as the HMC itself: a deposit with high HMC but mostly worthless heavy minerals such as staurolite or garnet is less attractive than a lower-HMC deposit rich in ilmenite and rutile.
Primary rock deposits, such as those in Norway and Canada, require conventional hard-rock mining — drilling, blasting, and either open-pit or underground extraction depending on the geometry of the orebody. The ore must then be crushed and ground before concentration can begin, adding both capital cost and energy consumption relative to mineral sand operations. Ukraine's deposits, largely of ilmenite in crystalline basement rocks, also fall into this category. China's titaniferous magnetite is mined as iron ore first; the titanium is recovered as a by-product of iron and steel production, which gives it a different cost structure from dedicated titanium mineral operations.
What pulls on it
The dominant use of titanium mineral concentrates — accounting for well over nine-tenths of all material mined — is the production of titanium dioxide pigment, written TiO2. This is the white pigment used in paint, coatings, plastics, paper, and a wide range of other products. Its commercial attraction is its exceptionally high refractive index, which means it scatters light very efficiently and produces opacity and whiteness at lower loadings than any practical alternative. Paint is by far the largest single end market, and because paint consumption tracks construction activity and consumer goods production, demand for titanium mineral concentrates broadly follows economic cycles in building and manufacturing. Architectural and decorative coatings, industrial coatings for metal, and automotive finishes all draw on TiO2 pigment, though in differing grades and specifications.
Titanium metal, despite its high profile in aerospace and defence, represents a comparatively small share of total mineral consumption, though it commands a disproportionate share of attention given the complexity of the supply chain needed to produce it. The metal's combination of low density, high strength, and corrosion resistance makes it difficult to replace in structural components for aircraft, in medical implants, and in certain chemical processing equipment. Demand for the metal has grown as widebody aircraft production has expanded, but the long lead time from mine to finished metal means the market responds slowly to changes in aircraft build rates.
For demand to change sharply downward in the pigment market, a substitute white pigment of comparable performance would need to become commercially available at competitive cost — which has not happened. A prolonged, broad downturn in construction and manufacturing could compress demand cyclically, as occurred in past recessions, but the underlying structural demand for white coatings in a world producing large volumes of paint is unlikely to shift fundamentally. Growth could accelerate if paper-grade TiO2 consumption recovers, or if new applications in photocatalysis, sunscreen, and food-contact materials expand, though those markets are individually small relative to coatings.
Where it comes from in the rock
All ore minerals →These are the minerals that actually carry titanium mineral concentrates. A deposit is only an orebody if one of them is concentrated enough to pay for digging it up.
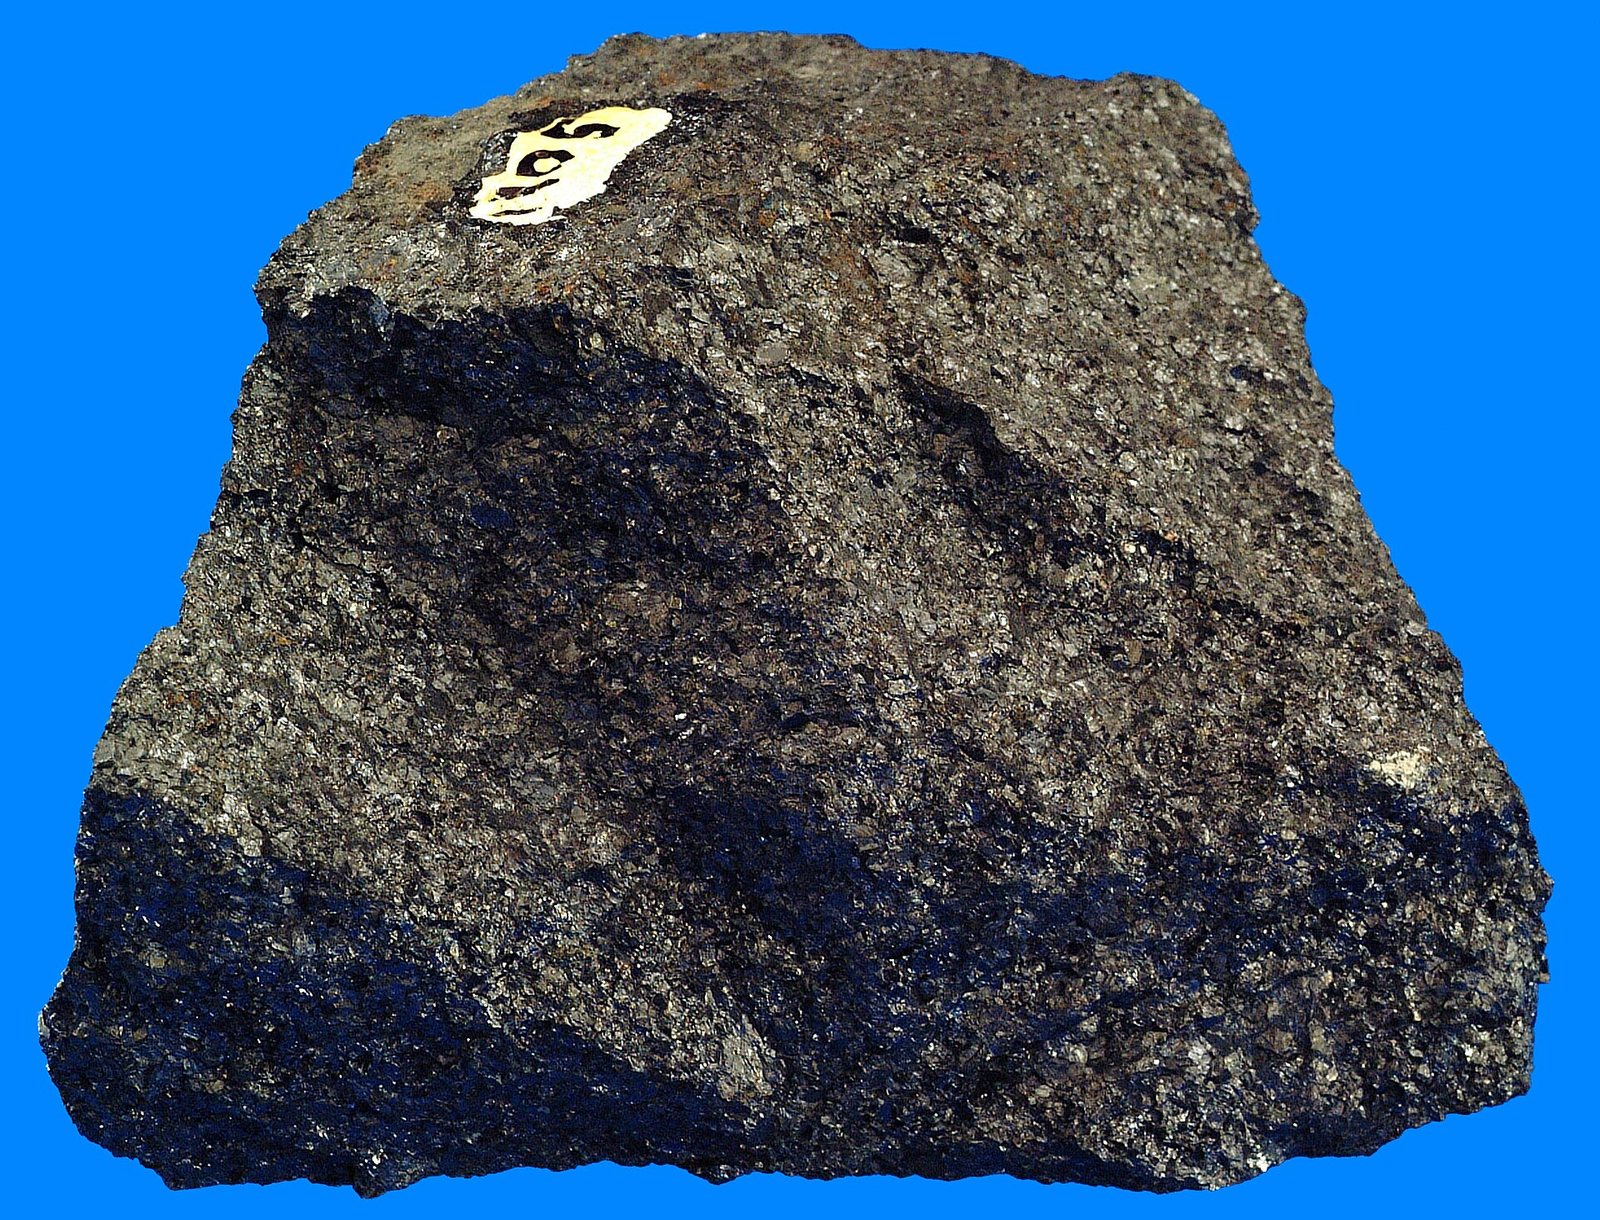
Ilmenite
The dominant titanium mineral, about 45-65% TiO2, mined from heavy mineral sand deposits along ancient shorelines.
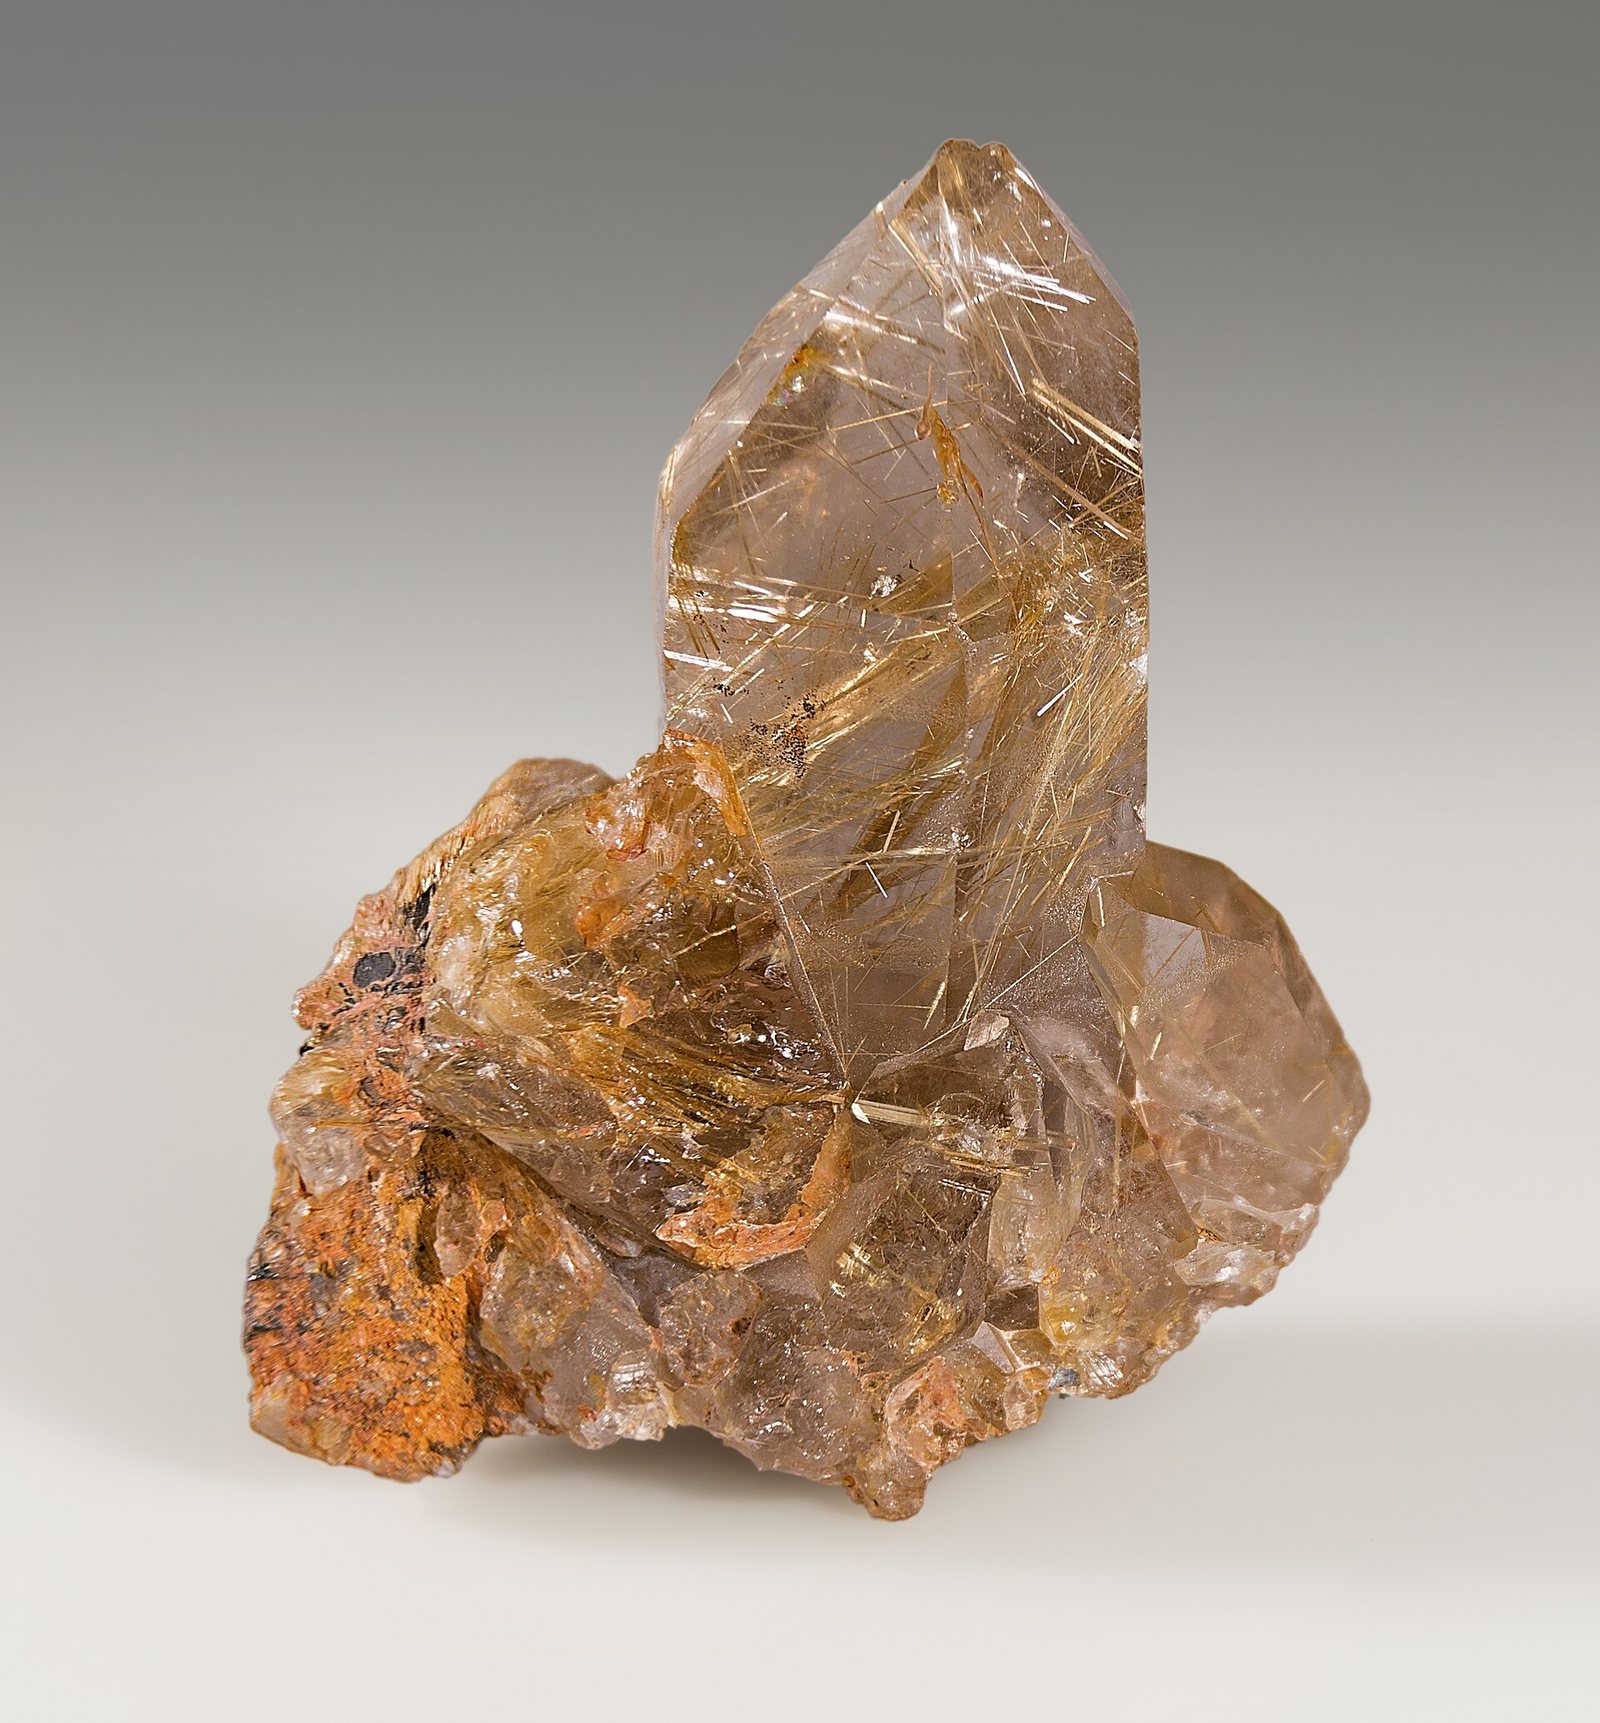
Rutile
Nearly pure titanium dioxide at about 95%. Scarcer and more valuable than ilmenite, and the preferred feed for titanium…
Who produces it
See it on a map →Mine production: Ilmenite
Mine production: Ilmenitethousand metric tons 2025 (estimated)
USGS Mineral Commodity Summaries 2026 · Gross weight of ilmenite plus rutile concentrate, TiO2 content varies by mineral. · source ↗
Scroll the table sideways for the remaining columns.
| Country | Production | Share of world |
|---|---|---|
| China | 3,200 | — |
| Mozambique | 1,900 | — |
| South Africa | 1,300 | — |
| Australia | 780.0 | — |
| Norway | 390.0 | — |
| Senegal | 370.0 | — |
| Canada | 360.0 | — |
| Madagascar | 300.0 | — |
| India | 240.0 | — |
| Other countries | 230.0 | — |
| Ukraine | 200.0 | — |
| United States | 100.0 | — |
Mine production: Rutile
Mine production: Rutilethousand metric tons 2025 (estimated)
USGS Mineral Commodity Summaries 2026 · Gross weight of ilmenite plus rutile concentrate, TiO2 content varies by mineral. · source ↗
Scroll the table sideways for the remaining columns.
| Country | Production | Share of world |
|---|---|---|
| Australia | 200.0 | — |
| Sierra Leone | 110.0 | — |
| South Africa | 100.0 | — |
| India | 13.00 | — |
| Ukraine | 10.00 | — |
| Mozambique | 10.00 | — |
| Other countries | 9.00 | — |
| Kenya | Zero | — |
| United States | s | — |
Mine production: ilmenite and rutile, rounded
Mine production: ilmenite and rutile, roundedthousand metric tons 2025 (estimated) World total 9,800 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of ilmenite plus rutile concentrate, TiO2 content varies by mineral. · source ↗
Scroll the table sideways for the remaining columns.
| Country | Production | Share of world |
|---|---|---|
| World total | 9,800 | 100% |
Mine production: ilmenite, rounded
Mine production: ilmenite, roundedthousand metric tons 2025 (estimated) World total 9,400 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of ilmenite plus rutile concentrate, TiO2 content varies by mineral. · source ↗
Scroll the table sideways for the remaining columns.
| Country | Production | Share of world |
|---|---|---|
| World total | 9,400 | 100% |
Mine production: rutile, rounded
Mine production: rutile, roundedthousand metric tons 2025 (estimated) World total 450.0 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of ilmenite plus rutile concentrate, TiO2 content varies by mineral. · source ↗
Scroll the table sideways for the remaining columns.
| Country | Production | Share of world |
|---|---|---|
| World total | 450.0 | 100% |
“Withheld” means the USGS suppressed the figure to avoid disclosing an individual company's data — it does not mean zero. Country rows do not always sum to the world total because the source rounds each figure independently and does not always break out an “other countries” line.
Who holds the reserves
Reserves: Ilmenite
Reserves: Ilmenitethousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Country | Reserves | Share of world |
|---|---|---|
| Australia | 170,000 | — |
| China | 110,000 | — |
| Canada | 50,000 | — |
| Other countries | 46,000 | — |
| Norway | 37,000 | — |
| Madagascar | 30,000 | — |
| South Africa | 28,000 | — |
| India | 15,000 | — |
| Ukraine | 5,900 | — |
| United States | 2,000 | — |
| Senegal | Not applicable | — |
| Mozambique | Not applicable | — |
Reserves: Rutile
Reserves: Rutilethousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Country | Reserves | Share of world |
|---|---|---|
| Australia | 35,000 | — |
| South Africa | 6,200 | — |
| Sierra Leone | 2,900 | — |
| Ukraine | 2,500 | — |
| Mozambique | 720.0 | — |
| India | 670.0 | — |
| Other countries | >540.0 | — |
| Kenya | Zero | — |
| United States | s | — |
Reserves: ilmenite and rutile, rounded
Reserves: ilmenite and rutile, roundedthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Country | Reserves | Share of world |
|---|---|---|
| World total | >540,000 | 100% |
The source publishes this world total as a bound rather than a point figure, so the shares in the last column are themselves bounds.
Reserves: ilmenite, rounded
Reserves: ilmenite, roundedthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Country | Reserves | Share of world |
|---|---|---|
| World total | >490,000 | 100% |
The source publishes this world total as a bound rather than a point figure, so the shares in the last column are themselves bounds.
Reserves: rutile, rounded
Reserves: rutile, roundedthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Country | Reserves | Share of world |
|---|---|---|
| World total | >49,000 | 100% |
The source publishes this world total as a bound rather than a point figure, so the shares in the last column are themselves bounds.
Price
dollars per metric ton: Ilmenite, average unit value of imports
Annual averagedollars per metric ton
Basis: dollars per metric ton: Ilmenite, average unit value of imports. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
dollars per metric ton: Slag, 80%–95% TiO2, average unit value of imports
Annual averagedollars per metric ton
Basis: dollars per metric ton: Slag, 80%–95% TiO2, average unit value of imports. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
dollars per metric ton
Annual averagedollars per metric ton
Basis: dollars per metric ton. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
dollars per metric ton: Ilmenite and leucoxene, bulk, f.o.b. Australia
Annual averagedollars per metric ton
Basis: dollars per metric ton: Ilmenite and leucoxene, bulk, f.o.b. Australia. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
dollars per metric ton: Rutile, bulk, minimum 95% TiO2, free on board (f.o.b.) Australia
Annual averagedollars per metric ton
Basis: dollars per metric ton: Rutile, bulk, minimum 95% TiO2, free on board (f.o.b.) Australia. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
Export controls
| Country | Control | Applies to |
|---|---|---|
| Vietnam | Export ban | Raw materials of iron, lead-zinc, chromite, manganese, apatite, and rare earths and deeply processed titanium (2012). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.