これは何か
A metal as strong as steel at about half the weight, which does not corrode in seawater or in the human body.
なぜ重要なのか
Landing gear, jet-engine fan blades, submarine hulls and hip replacements all use titanium because nothing else combines that strength, weight and corrosion resistance.
Where it is in the Earth
Titanium is the ninth most abundant element in the Earth's crust, yet it almost never occurs in a form that is straightforward to mine. The reason is chemical: titanium bonds readily with oxygen and iron, which means it is dispersed through many common rock-forming minerals at concentrations too low to be worth processing. Economic deposits form only where geological processes have worked to separate and concentrate the titanium-bearing minerals into a relatively small volume of rock or sediment.
The two minerals that matter commercially are ilmenite and rutile. Both are oxides — that is, titanium combined with oxygen, in ilmenite's case with iron added as well. They form originally in igneous and metamorphic rocks, particularly in anorthosite complexes (bodies of coarse-grained rock rich in calcium feldspar) and in mafic intrusions (rocks that crystallised from magmas relatively rich in iron and magnesium). Because ilmenite and rutile are dense and chemically resistant, they survive the weathering and erosion that break down the surrounding rock, and rivers carry them downstream as heavy mineral grains. Where wave action and longshore drift concentrate these grains against a coastline, they accumulate as heavy mineral sands — often called mineral sands deposits. The same sorting process can happen in ancient, now-buried beaches that were later covered by younger sediments, producing what the industry calls fossil or palaeodune deposits.
This explains the geographical pattern visible in the production table. The largest known concentrations of mineral sands lie around the Indian Ocean rim, in parts of Australia, southern Africa, India and Sri Lanka, as well as along some Atlantic coastlines. Anorthosite-hosted deposits occur in Norway, Canada and parts of China. The location of a country's resource is therefore largely an accident of where ancient coastlines ran and where the right kind of igneous activity took place, not of any policy or industrial decision.
Getting it out
Most titanium-bearing ore is mined as loose sand — or as soft, sandy rock that behaves like loose sand once excavated. This makes open-pit or open-cast methods the natural choice. Heavy machinery strips away overlying material (called overburden) to expose the ore horizon, and the mineral-bearing sand is then dug up and moved to a processing plant nearby. Because the valuable minerals make up only a small fraction of the total sand even in a good deposit, very large volumes of material move for every tonne of titanium mineral recovered. The gangue — the unwanted material, mostly quartz sand — is typically returned to the worked-out pit as a form of land rehabilitation.
Some deposits lie beneath water tables or shallow coastal lagoons, in which case a floating dredge cuts into the ore face and pumps a slurry of sand and water to a floating concentrator on the same pond. This avoids the need to dewater the pit and works continuously as the dredge advances. Dredging tends to suit flat, low-lying coastal plain deposits; open-pit truck-and-shovel operations suit harder or more elevated ore bodies. In either case, the grade of the ore — meaning the proportion of heavy minerals it contains — determines how much total sand must be handled per tonne of ilmenite or rutile produced. A lower-grade deposit requires moving proportionally more material, which increases fuel consumption, equipment wear and waste-handling cost even if the ore itself is cheap to excavate.
Titanium metal is not mined directly. What the mine produces is a mineral concentrate — grains of ilmenite or rutile separated from the quartz sand. This concentrate then travels to chemical plants, sometimes on a different continent, before it becomes anything resembling a metal. The gap between a mine producing mineral sand and a factory producing titanium sponge (the porous, metallic intermediate product) is therefore large, both in distance and in the number of separate industrial steps involved.
What pulls on it
Titanium's commercial life rests on a combination of properties that very few materials share: a strength-to-weight ratio competitive with high-strength steel, near-total resistance to corrosion in both seawater and biological fluids, and biocompatibility that allows it to sit inside the human body without triggering an immune response. These properties define which industries buy it. Aerospace — both commercial aviation and defence — has historically been the largest consumer, using titanium in airframe structures, landing gear, hydraulic tubing and the fan and compressor sections of jet engines where temperatures are moderate enough for titanium alloys to retain their strength.
The medical sector takes a smaller but very consistent share, concentrated in orthopaedic implants (hip and knee replacements, spinal hardware) and dental implants. Demand from this quarter grows broadly in line with ageing populations and expanding access to elective surgery in middle-income countries, and it is less sensitive to economic cycles than aerospace demand. Chemical processing and desalination plants use titanium for heat exchangers and reactor vessels that must handle corrosive media, though this is a smaller share of total consumption.
A newer source of demand appears in the end-markets table: proton exchange membrane (PEM) electrolysers, which use titanium in bipolar plates and porous transport layers because those components must conduct electricity while resisting the highly acidic, oxidising internal environment. The material-intensity table records the titanium requirement for this application as between 200 and 600 kilograms per megawatt of electrolyser capacity — a wide range that reflects design variation across manufacturers. If hydrogen electrolysis capacity grows substantially, the implied titanium requirement could become significant relative to current sponge output, though how quickly that demand materialises depends on factors beyond the metal itself. Demand would change sharply downward if aerospace build rates fell for a sustained period, as they did during the early 2020s, because that sector drives the premium end of the market and any excess sponge capacity depresses prices across the board.
岩石中の産出箇所
全鉱石鉱物 →実際に以下を担う鉱物 titanium. 鉱床が鉱体となるのは、採掘コストを回収できるほど十分な濃度で鉱石が濃集している場合に限られる。
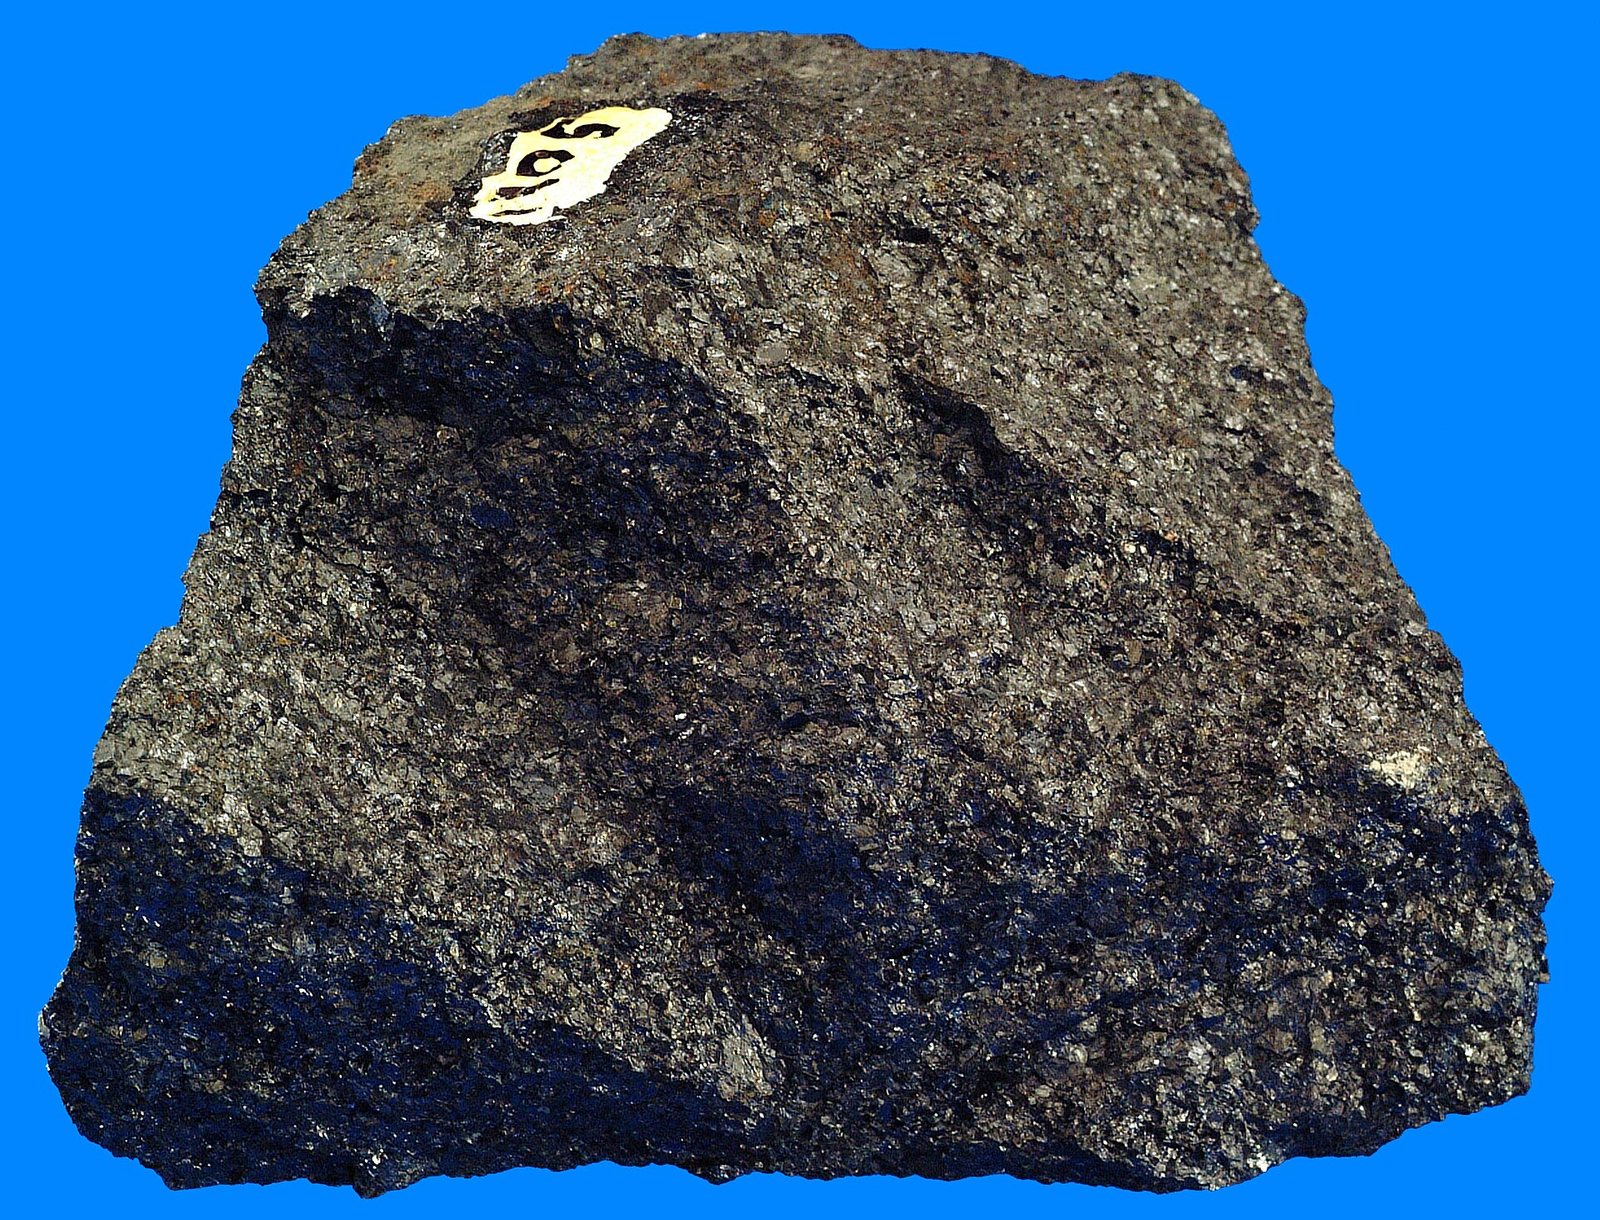
Ilmenite
The dominant titanium mineral, about 45-65% TiO2, mined from heavy mineral sand deposits along ancient shorelines.
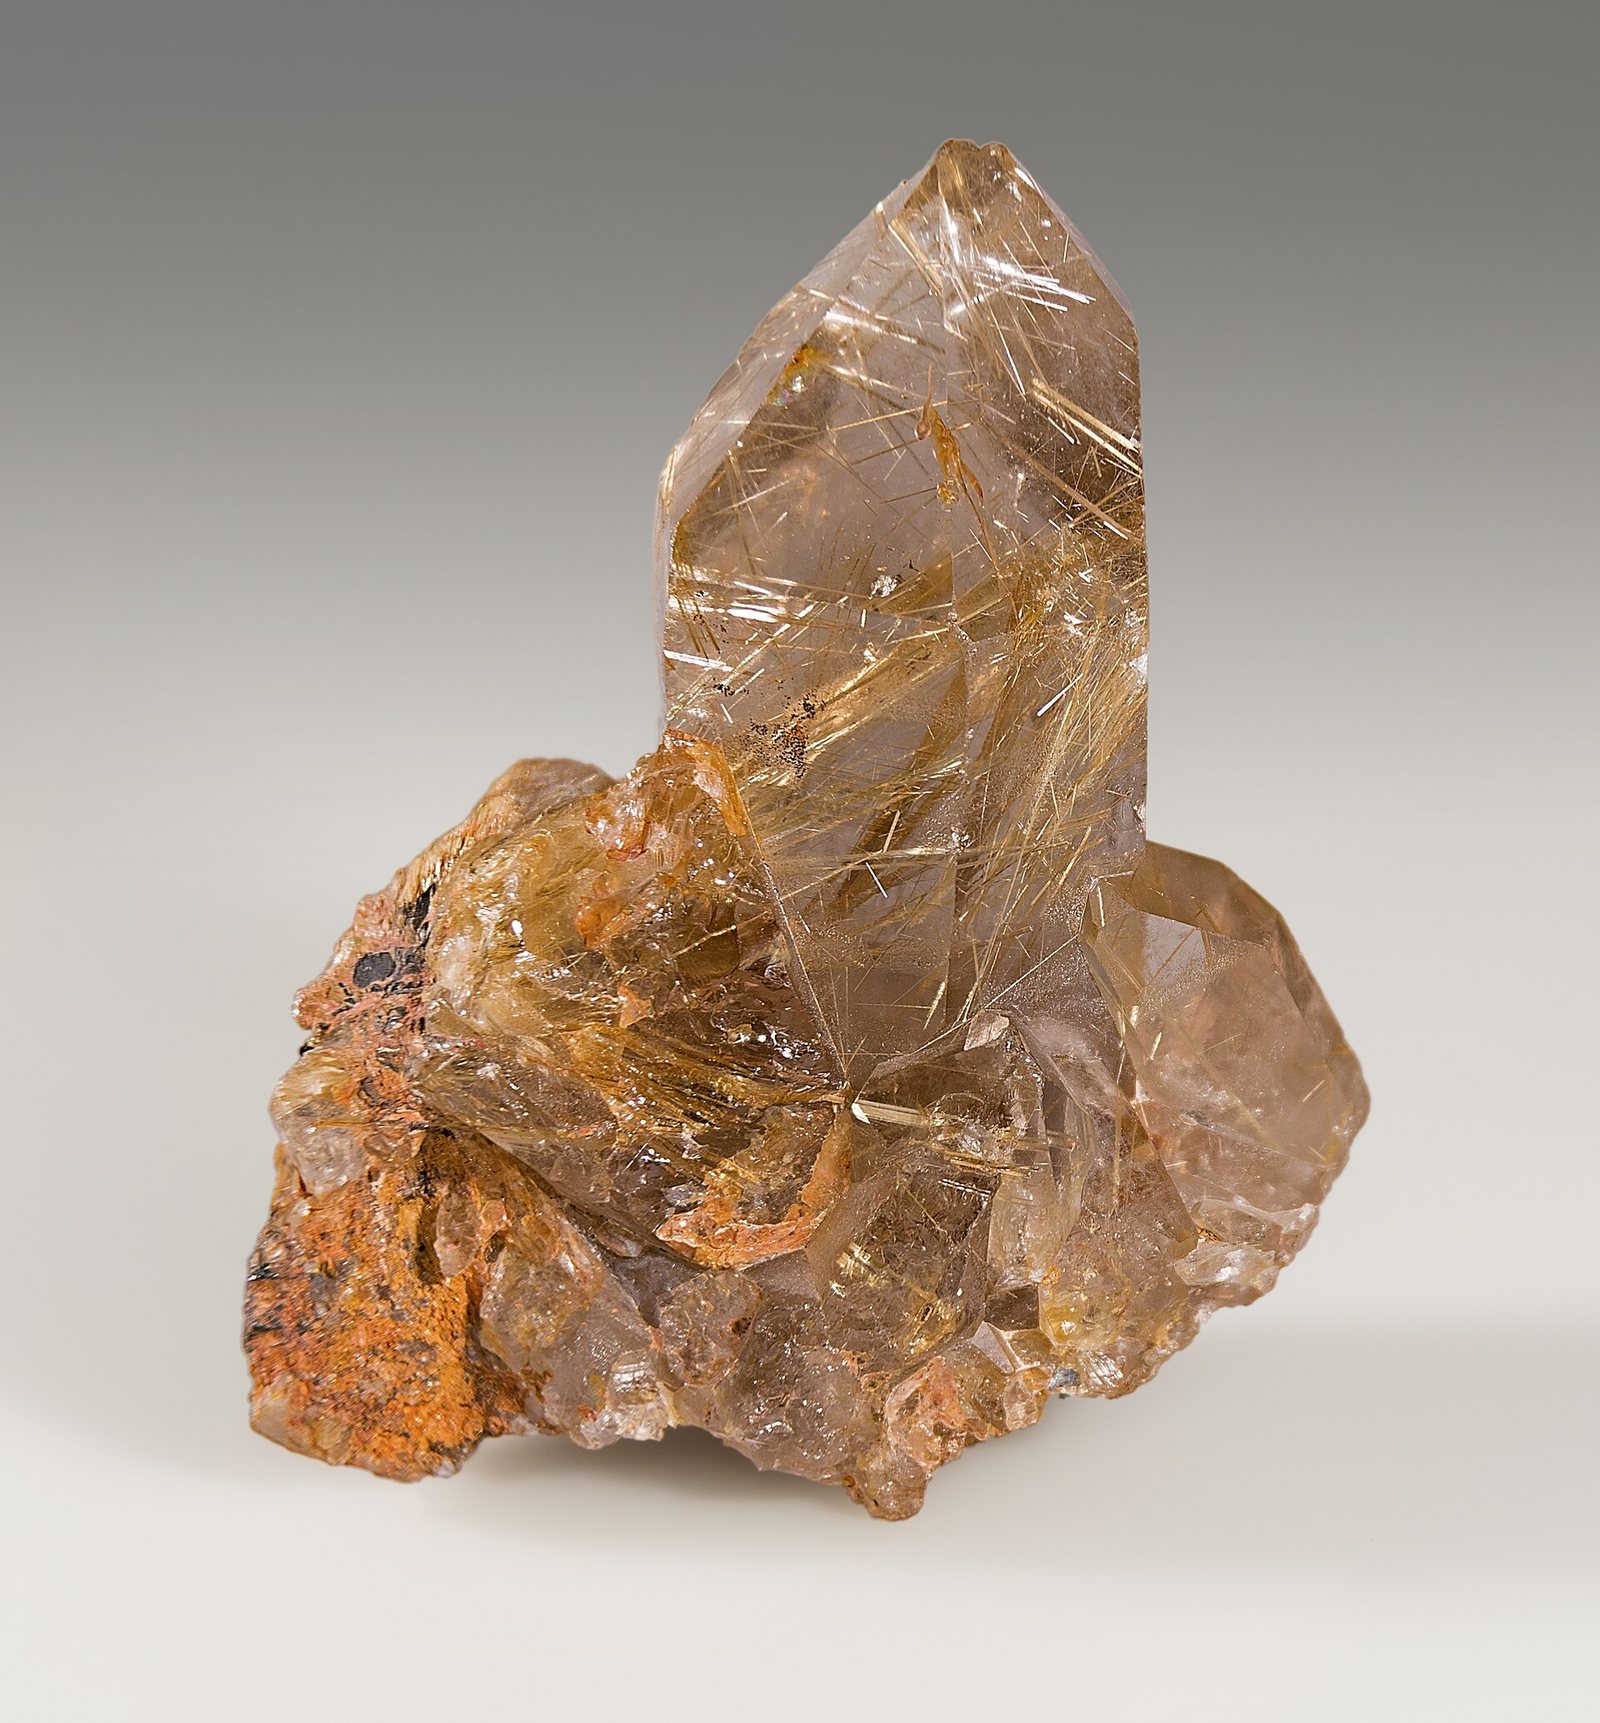
Rutile
Nearly pure titanium dioxide at about 95%. Scarcer and more valuable than ilmenite, and the preferred feed for titanium…
生産者
地図で見る →Titanium sponge metal production
Titanium sponge metal productionmetric tons 2025 (推定値) 世界合計 370,000 metric tons
USGS Mineral Commodity Summaries 2026 · Sponge metal production, not mineral concentrate — the two are different tables and different orders of magnitude. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| China | 260,000 | 70.3% |
| Japan | 53,000 | 14.3% |
| Russia | 25,000 | 6.8% |
| Kazakhstan | 16,000 | 4.3% |
| Saudi Arabia | 12,000 | 3.2% |
| India | 300.0 | 0.1% |
| Germany | Zero | — |
| Mexico | Zero | — |
| Ukraine | Zero | — |
| United Kingdom | Zero | — |
| Other countries | Zero | — |
| United States | Zero | — |
| Australia | Zero | — |
| Canada | Zero | — |
| 世界合計 | 370,000 | 100% |
「非開示」とは、個別企業のデータが特定されないようUSGSが数値を公表しなかったことを意味し、ゼロを意味するものではありません。出典が各数値を独立して丸め処理しており、「その他の国」の内訳を常に示しているわけではないため、各国の数値の合計が世界合計と一致しないことがあります。
価格
dollars per kilogram
年間平均dollars per kilogram
基準: dollars per kilogram. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
処理・精製が行われる場所
| プラント | 種別 | ステージ | 国 | 役割 |
|---|---|---|---|---|
| Aero-Engine Turbine Plant, Derby | 製造プラント | 製品 | United Kingdom | 投入 |
用途
全エンドマーケット →| 最終市場 | そこでの機能 | 重要度 |
|---|---|---|
| Aerospace & Defence | Airframe and engine structure | 定義 |
| Medicine & Health | Implants and instruments | 定義 |
| Hydrogen & Electrolysis | PEM bipolar plates | 重要 |
| Robotics & Automation | Lightweight structural parts | 現在 |
技術が必要とする量
| 技術 | 数量 | 建値 | 基準 |
|---|---|---|---|
| PEM Electrolyser | 200.0–600.0 kg | per MW of capacity | Bipolar plates and porous transport layers |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. 素材計算機で任意の規模に換算して実行 →
輸出規制
| 国 | 支配 | 適用対象 |
|---|---|---|
| Vietnam | Export ban | Raw materials of iron, lead-zinc, chromite, manganese, apatite, and rare earths and deeply processed titanium (2012). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.