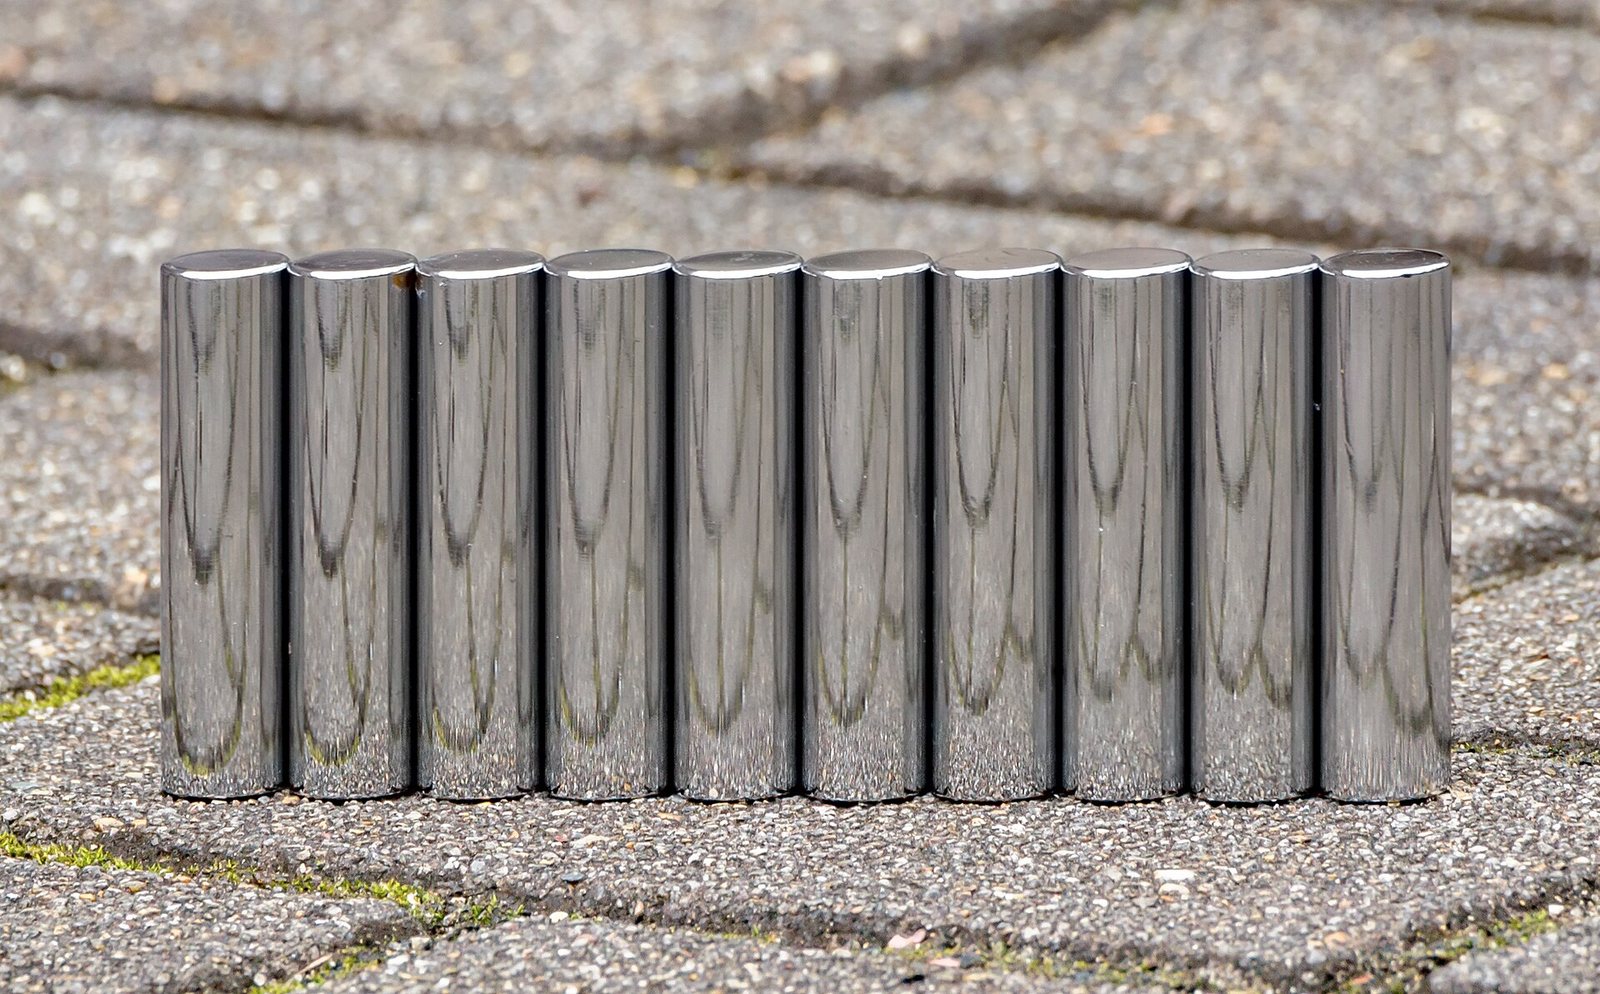
Qu'est-ce que c'est ?
The element that makes stainless steel stainless — at about eleven percent chromium, steel grows an invisible film that stops rust.
Pourquoi est-ce important ?
There is no substitute for chromium in stainless steel, and supply is unusually concentrated in southern Africa.
Where it is in the Earth
Chromium reaches mineable concentrations almost exclusively through one geological process: the crystallisation of magma derived from the Earth's mantle. When ultramafic magma — rock-forming liquid unusually rich in magnesium and iron and poor in silica — cools slowly deep in the crust, the mineral chromite (iron chromium oxide, with the formula FeCr2O4) is among the first solid phases to appear. Being denser than the surrounding melt, chromite crystals sink and accumulate in layers, a process called magmatic segregation. The resulting rock bodies are called layered igneous intrusions, and the chromite-rich bands within them are called seams or reefs. The Bushveld Igneous Complex in South Africa is the largest and most chromite-rich structure of this kind known, and it accounts for the dominant share of both current production and global reserves shown in the tables above.
A second geological setting produces podiform deposits: chromite concentrated in lenses within ophiolites, which are fragments of ancient ocean floor that have been thrust onto continental margins. These bodies are smaller and less regular than layered intrusion reefs, but they can be high in grade and are the source of much of Turkey's production. The Kempirsai massif in Kazakhstan represents a very large podiform system, giving that country the second-largest reserve base after South Africa. The geographical concentration of reserves that the tables show is therefore not an accident of exploration history but a reflection of where the right geology exists: southern Africa and central Asia sit atop the largest surviving layered and podiform chromite systems on the planet.
Because chromite forms in the mantle-derived part of the geological cycle, it is rarely found in the sedimentary or granitic rocks that make up most of the continental crust. There are no chromium-bearing brines, no evaporite deposits, no hydrothermal vein systems worth mining. The ore mineral is chromite, and only chromite. This geological narrowness has direct consequences for the supply chain: new deposits can only be found in the specific rock types and tectonic settings described above, and those settings are unevenly distributed across the globe.
Getting it out
Most large chromite deposits are mined by open-pit methods, at least in their early stages, because the reef geometry and the relatively shallow depth of many economically attractive seams make surface excavation the lowest-cost option. In open-pit mining, the overlying rock — called overburden or waste — is stripped away to expose the ore beneath. The ratio of waste moved to ore recovered, called the strip ratio, matters greatly to the economics of a mine: a high strip ratio means more diesel, more trucks and more time per tonne of chromite delivered to the processing plant. As a pit deepens, strip ratios rise and at some point underground methods become more attractive. The Bushveld mines in South Africa include both large open pits and underground bord-and-pillar or room-and-pillar operations, where horizontal chambers are cut and columns of rock left standing to support the roof.
The grade of chromite ore — typically expressed as the percentage of Cr2O3 (chromium sesquioxide) in the rock — determines how much raw material must be dug, crushed and transported to yield a given amount of usable chromium. Higher-grade ores reduce the cost of every subsequent step in the chain. Another number that matters in the chromite trade is the chromium-to-iron ratio, or Cr:Fe ratio, because different end uses — metallurgical, chemical, refractory — require different ratios. A metallurgical-grade ore destined for ferrochrome smelting has different specification requirements than a chemical-grade ore destined for chromium chemicals production. These distinctions explain why ore from different deposits commands different prices even at the same Cr2O3 content.
The United States produces no chromite ore from domestic mines — the USGS reports this figure as withheld, reflecting the absence of active primary production rather than suppressed data — which is why the U.S. import reliance figure in the statistics table is as high as it is. Domestic resources exist, as the reserves table shows, but they are not currently being worked at commercial scale. Turkey's production comes largely from smaller podiform deposits, which are typically mined by smaller operations with shorter mine lives than the large South African reef mines. This variety of deposit type and mine scale across producer countries means the global supply picture is not monolithic: a disruption in one country does not automatically mean another can fill the gap quickly.
What pulls on it
The dominant use of chromium is in stainless steel, and the relationship is chemically non-negotiable: below roughly eleven percent chromium by weight, the protective passive oxide film that gives stainless steel its corrosion resistance does not reliably form. This threshold effect means that chromium cannot simply be used sparingly or diluted away when its price rises; a stainless steel grade either meets its chromium specification or it is not stainless steel. Beyond stainless, chromium is alloyed into a wide range of engineering steels — high-speed tool steels, bearing steels, chromium-molybdenum pressure-vessel steels — and into the nickel-based superalloys used in jet engines and gas turbines, where it contributes to oxidation resistance at high temperatures.
Demand for stainless steel tracks industrial activity broadly, and particularly the growth of construction, consumer goods, food processing and chemical plant in industrialising economies. The expansion of stainless steel production in China over the past two decades was the single largest change in the global chromium demand picture of that period, and China's trajectory continues to shape the market. A meaningful share of demand also comes from the chemical industry — chromium compounds in leather tanning and surface treatment — though regulatory pressure on hexavalent chromium in many jurisdictions has pushed some of this demand toward alternative finishing processes, causing a gradual erosion in those specific applications. Nuclear power, listed in the end-markets section, represents a relatively specialised but stable demand for chromium-containing reactor steels, where the corrosion resistance requirements are particularly stringent.
A sharp change in chromium demand would most plausibly follow from a large-scale shift in stainless steel consumption — either a sustained contraction in the construction and industrial sectors that drive stainless demand, or an unlikely but theoretically possible displacement of stainless by another corrosion-resistant material. Neither appears imminent based on the structural drivers of industrial development, though the efficiency of chromium use in steel — how many tonnes of chromite ore are required per tonne of stainless produced — is a variable that improves incrementally as steelmakers reduce process losses and recycle scrap more effectively.
Turning ore into product Niveau 3
Run-of-mine chromite ore — the material as it comes from the pit or underground workings — goes first through comminution: crushing and then grinding to break the rock down until chromite grains are liberated from the surrounding silicate minerals. Because chromite is significantly denser than most gangue (the unwanted host rock), concentration is achieved mainly by gravity separation, using spirals, shaking tables or dense-media vessels. Magnetic and flotation circuits may supplement gravity steps depending on the ore character. The product of this beneficiation stage is a chromite concentrate, reporting a higher Cr2O3 grade than the run-of-mine feed. Fine-grained ores, particularly those from some South African deposits, can be difficult to concentrate efficiently and may require sintering or pelletising before they can be fed to a furnace.
For metallurgical use, chromite concentrate is smelted with coke and a flux (typically quartz) in a submerged arc furnace — a large electric furnace in which the electrodes are buried in the charge. The product is ferrochrome, an alloy of chromium and iron. Charge chrome, the dominant traded form, typically contains roughly half chromium and the remainder iron and carbon; high-carbon ferrochrome and refined low-carbon grades also exist for specific applications. The electricity consumption of submerged arc smelting is substantial, which is why ferrochrome production has historically clustered where electricity is cheap — South Africa and Kazakhstan — or where integrated operations reduce logistics costs. South Africa has progressively moved more smelting capacity in-country rather than exporting raw ore, capturing more of the value chain domestically. The price tables show ferrochrome and chromite ore quoted separately, reflecting the real commercial distinction between selling ore and selling the smelted intermediate.
Chromium metal, as distinct from ferrochrome, is produced by aluminothermic reduction — reacting chromium oxide with aluminium powder — or by electrolytic refining. The metal commands a substantially higher price per pound than ferrochrome, as the price series in the tables illustrate, because the additional processing steps add cost and the market is smaller. Chemical uses of chromium — leather tanning, surface finishing, pigments — require yet another processing route: ore is roasted with sodium carbonate to produce sodium chromate, from which a range of hexavalent chromium (Cr6+) compounds are derived. Hexavalent chromium is toxic, and the handling and disposal requirements this creates add cost and regulatory complexity to chemical-grade processing.
Substitution and recycling Niveau 3
In stainless steel, there is no substitute for chromium. The passive film that resists corrosion is a chromium oxide layer; no other alloying element replicates it at comparable cost and in comparable steel compositions. Nickel and molybdenum are added to stainless grades to enhance specific properties, but they complement rather than replace chromium. Where customers have moved away from stainless steel — toward coated carbon steel, aluminium, polymers or composites — they have accepted trade-offs in temperature resistance, mechanical properties, longevity or recyclability. In many corrosive environments, those trade-offs are unacceptable, which constrains substitution in practice far more than price alone would suggest.
In superalloys and high-temperature coatings, aluminium and silicon can provide some oxidation resistance, and coating technologies have advanced considerably. However, these alternatives perform differently across different temperature ranges and corrosive environments, and superalloy designers generally treat chromium as one component of a complex balance rather than a variable they wish to eliminate. In surface finishing, trivalent chromium (Cr3+) processes have partially displaced traditional hexavalent chromium electroplating in response to environmental regulation, representing a genuine substitution within the chromium system rather than away from it — the metal is still used, just in a different oxidation state and process chemistry.
Recycling is a significant secondary source of chromium, though it moves through the steel scrap stream rather than as recovered chromium metal. Stainless steel scrap is highly sought after precisely because of its chromium content, and steelmakers actively seek it for its alloy value. The recycling rate for chromium embedded in stainless steel at end of life is relatively high compared to many other technology metals, because the scrap has clear economic value and the collection infrastructure for steel is well established. What limits the recycled fraction is dilution: stainless scrap mixed with carbon steel scrap loses its chromium value, and separation at the point of collection or sorting is imperfect. The availability of high-quality stainless scrap also depends on the age profile of installed stainless steel stock — material put into service during periods of rapid growth only becomes available for recycling decades later.
Where the chain is fragile Niveau 4
The concentration of both production and reserves in a small number of countries is the most straightforward feature of the chromium supply risk picture, and the tables make it plain. South Africa alone accounts for 45 percent of world production and holds the largest reserve base. Kazakhstan holds the second-largest reserve position. Zimbabwe's reserves are substantial relative to its current production, suggesting latent capacity, but realising it depends on infrastructure, capital and regulatory conditions that are not guaranteed. The figures for reserves in the tables carry their own uncertainty: reserve estimates are sensitive to the chromium price assumed, the Cr2O3 cut-off grade applied, and whether the compiling agency uses national government data, company disclosures or independent estimates. The USGS notes that its figures are drawn from varied national sources and that reporting conventions differ across countries, which means the apparent precision of the reserve numbers should not be mistaken for precision in the underlying knowledge.
A further structural feature is the two-stage geography of the supply chain. Mining is concentrated in southern Africa, but a meaningful share of smelting capacity — converting chromite ore to ferrochrome — also sits in South Africa and Kazakhstan. Countries that import chromite for domestic smelting, such as China and some European producers, are exposed both to ore supply and to the logistical and political conditions affecting export from producer countries. South Africa in particular has experienced periods of electricity supply constraint that affected ferrochrome smelting output, illustrating the dependency of this energy-intensive process on stable power infrastructure. The price data show considerable year-to-year movement in ferrochrome values, which reflects both demand cycles and these supply-side irregularities.
The United States' position — no domestic mine production and a net import reliance of 79 percent as reported by USGS — places it among the more exposed consuming nations. Domestic reserves exist, but the gap between a resource in the ground and a producing mine involves permitting timelines, infrastructure development and sustained economic justification that typically spans many years. The lead time from discovery or project initiation to first production for a new hard-rock mine is rarely less than a decade. This lag means that a policy decision to develop domestic chromite capacity cannot quickly translate into supply security, which is why chromium appears on critical mineral lists in multiple jurisdictions. The secondary supply — chromium recycled through stainless scrap — provides some buffer, but the quantity available at any given time is determined by the vintage of installed stainless stock and scrap collection efficiency, neither of which responds quickly to a supply shock in primary ore.
D'où cela vient dans la roche
Tous les minéraux de minerai →Ce sont les minéraux qui portent réellement chromium. Un gisement n'est un corps minéralisé que si l'un d'eux est suffisamment concentré pour rentabiliser son extraction.
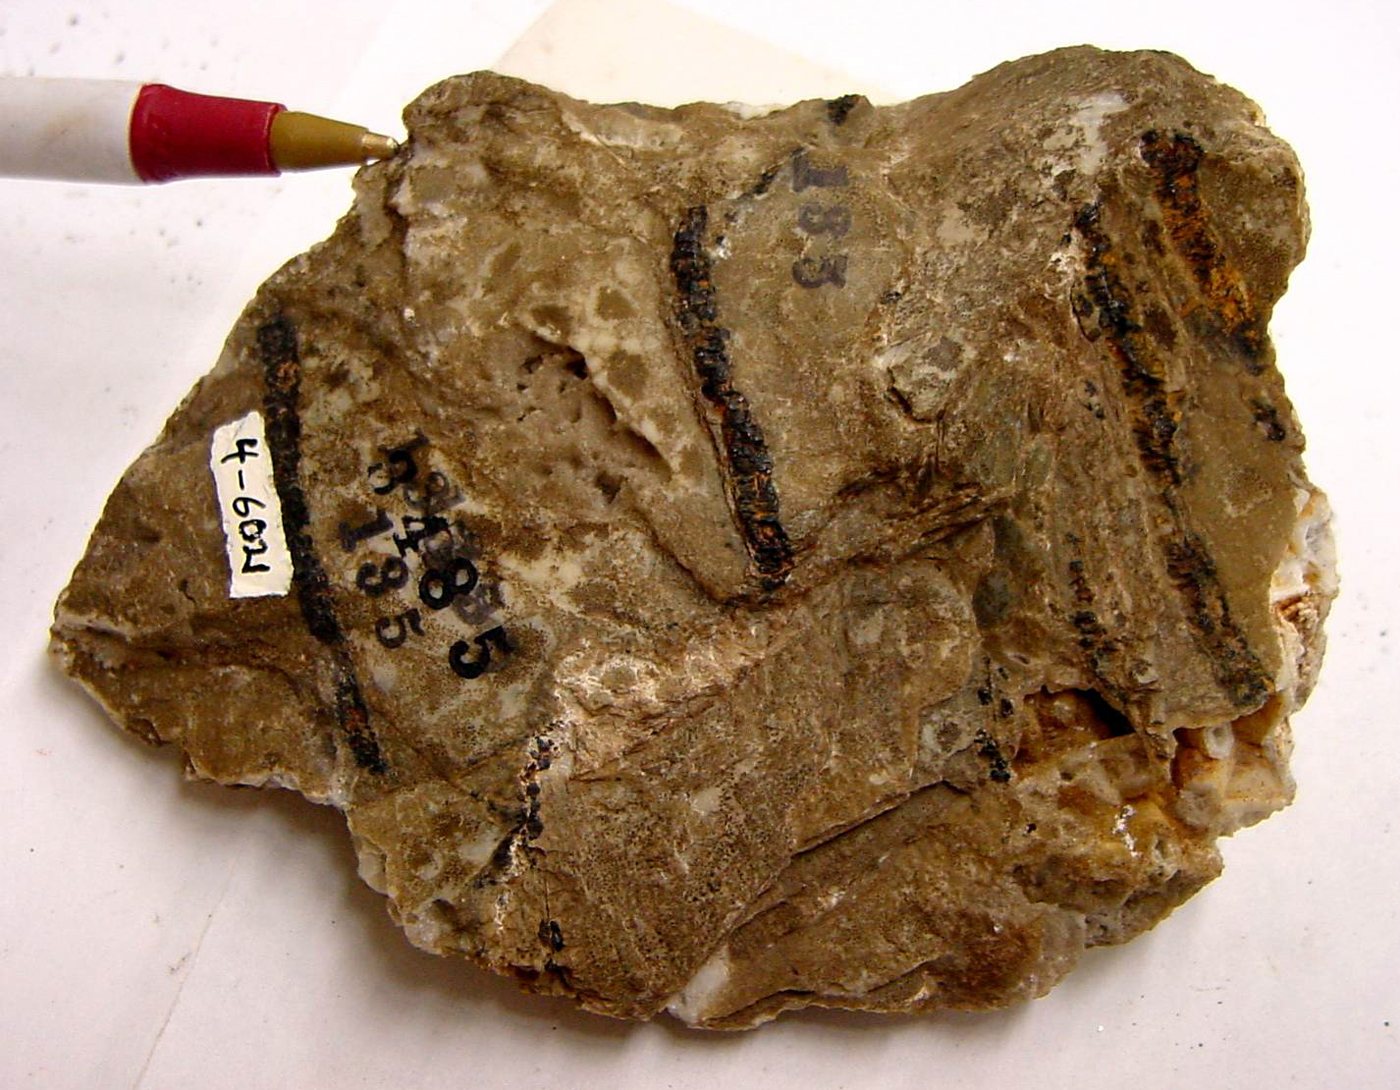
Chromite
The only ore of chromium, formed in layered mafic intrusions where it settles out in bands.
Qui le produit
Voir sur une carte →Mine production
Mine productionthousand metric tons 2025 (estimé) Total mondial 51,000 thousand metric tons
USGS Mineral Commodity Summaries 2026 · USGS reports chromite ore gross weight, not contained chromium. · source ↗
Faire défiler le tableau latéralement pour afficher les colonnes restantes.
| Pays | Production | Part mondiale |
|---|---|---|
| South Africa | 23,000 | 45.1% |
| Turkey | 9,000 | 17.6% |
| Kazakhstan | 7,000 | 13.7% |
| Other countries | 3,000 | 5.9% |
| India | 3,000 | 5.9% |
| Zimbabwe | 2,000 | 3.9% |
| Brazil | 2,000 | 3.9% |
| Finland | 1,900 | 3.7% |
| United States | Zero | — |
| Total mondial | 51,000 | 100% |
« Withheld » signifie que l'USGS a supprimé le chiffre afin de ne pas divulguer les données d'une entreprise individuelle — cela ne signifie pas zéro. La somme des lignes par pays ne correspond pas toujours au total mondial, car la source arrondit chaque chiffre de manière indépendante et ne détaille pas toujours une ligne « autres pays ».
Qui détient les réserves
Reserves: Cr2O3 content
Reserves: Cr2O3 contentthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Pays | Réserves | Part mondiale |
|---|---|---|
| South Africa | 110,000 | 20.4% |
| Kazakhstan | 100,000 | 18.5% |
| Zimbabwe | 78,000 | 14.4% |
| India | 27,000 | 5.0% |
| Finland | 16,000 | 3.0% |
| Turkey | 5,700 | 1.1% |
| Brazil | 1,000 | 0.2% |
| United States | 630.0 | 0.1% |
| Other countries | Not applicable | — |
| Total mondial | >540,000 | 100% |
La source publie ce total mondial comme une valeur encadrée plutôt que comme un chiffre précis ; les parts figurant dans la dernière colonne sont donc elles-mêmes des bornes.
Reserves: Ore
Reserves: Orethousand metric tons 2024
USGS Mineral Commodity Summaries 2026 · source ↗
| Pays | Réserves | Part mondiale |
|---|---|---|
| South Africa | 350,000 | 29.2% |
| Kazakhstan | 230,000 | 19.2% |
| Zimbabwe | 140,000 | 11.7% |
| India | 79,000 | 6.6% |
| Finland | 63,000 | 5.2% |
| Turkey | 27,000 | 2.2% |
| United States | 8,500 | 0.7% |
| Brazil | 3,900 | 0.3% |
| Other countries | Not applicable | — |
| Total mondial | >1,200,000 | 100% |
La source publie ce total mondial comme une valeur encadrée plutôt que comme un chiffre précis ; les parts figurant dans la dernière colonne sont donc elles-mêmes des bornes.
Prix
Price: Chromium metal (gross weight), dollars per pound
Moyenne annuelledollars per pound
Base: Price: Chromium metal (gross weight), dollars per pound. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
Price: Chromite ore (gross weight), dollars per metric ton
Moyenne annuelledollars per metric ton
Base: Price: Chromite ore (gross weight), dollars per metric ton. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
Price: Ferrochromium (chromium content), dollars per pound
Moyenne annuelledollars per pound
Base: Price: Ferrochromium (chromium content), dollars per pound. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
À quoi cela sert
Tous les marchés finaux →| Marché final | Ce qu'il fait là-bas | Importance |
|---|---|---|
| Nuclear Power | Corrosion resistance in reactor steels | Important |
Suivez-le au fil des frontières
Tous les parcours →Où va réellement un lot de ce matériau — chaque pays, chaque dépositaire, et ce qui est perdu à chaque étape.
New Caledonian laterite to stainless steel An island that smelts its own ore, and pays for it with the most expensive electricity in the industry.