What is it?
The element that makes stainless steel stainless — at about eleven percent chromium, steel grows an invisible film that stops rust.
Why does it matter?
There is no substitute for chromium in stainless steel, and supply is unusually concentrated in southern Africa.
Where it is in the Earth
Chromium reaches mineable concentrations almost exclusively through one geological process: the crystallisation of magma derived from the Earth's mantle. When ultramafic magma — rock-forming liquid unusually rich in magnesium and iron and poor in silica — cools slowly deep in the crust, the mineral chromite (iron chromium oxide, with the formula FeCr2O4) is among the first solid phases to appear. Being denser than the surrounding melt, chromite crystals sink and accumulate in layers, a process called magmatic segregation. The resulting rock bodies are called layered igneous intrusions, and the chromite-rich bands within them are called seams or reefs. The Bushveld Igneous Complex in South Africa is the largest and most chromite-rich structure of this kind known, and it accounts for the dominant share of both current production and global reserves shown in the tables above.
A second geological setting produces podiform deposits: chromite concentrated in lenses within ophiolites, which are fragments of ancient ocean floor that have been thrust onto continental margins. These bodies are smaller and less regular than layered intrusion reefs, but they can be high in grade and are the source of much of Turkey's production. The Kempirsai massif in Kazakhstan represents a very large podiform system, giving that country the second-largest reserve base after South Africa. The geographical concentration of reserves that the tables show is therefore not an accident of exploration history but a reflection of where the right geology exists: southern Africa and central Asia sit atop the largest surviving layered and podiform chromite systems on the planet.
Because chromite forms in the mantle-derived part of the geological cycle, it is rarely found in the sedimentary or granitic rocks that make up most of the continental crust. There are no chromium-bearing brines, no evaporite deposits, no hydrothermal vein systems worth mining. The ore mineral is chromite, and only chromite. This geological narrowness has direct consequences for the supply chain: new deposits can only be found in the specific rock types and tectonic settings described above, and those settings are unevenly distributed across the globe.
Getting it out
Most large chromite deposits are mined by open-pit methods, at least in their early stages, because the reef geometry and the relatively shallow depth of many economically attractive seams make surface excavation the lowest-cost option. In open-pit mining, the overlying rock — called overburden or waste — is stripped away to expose the ore beneath. The ratio of waste moved to ore recovered, called the strip ratio, matters greatly to the economics of a mine: a high strip ratio means more diesel, more trucks and more time per tonne of chromite delivered to the processing plant. As a pit deepens, strip ratios rise and at some point underground methods become more attractive. The Bushveld mines in South Africa include both large open pits and underground bord-and-pillar or room-and-pillar operations, where horizontal chambers are cut and columns of rock left standing to support the roof.
The grade of chromite ore — typically expressed as the percentage of Cr2O3 (chromium sesquioxide) in the rock — determines how much raw material must be dug, crushed and transported to yield a given amount of usable chromium. Higher-grade ores reduce the cost of every subsequent step in the chain. Another number that matters in the chromite trade is the chromium-to-iron ratio, or Cr:Fe ratio, because different end uses — metallurgical, chemical, refractory — require different ratios. A metallurgical-grade ore destined for ferrochrome smelting has different specification requirements than a chemical-grade ore destined for chromium chemicals production. These distinctions explain why ore from different deposits commands different prices even at the same Cr2O3 content.
The United States produces no chromite ore from domestic mines — the USGS reports this figure as withheld, reflecting the absence of active primary production rather than suppressed data — which is why the U.S. import reliance figure in the statistics table is as high as it is. Domestic resources exist, as the reserves table shows, but they are not currently being worked at commercial scale. Turkey's production comes largely from smaller podiform deposits, which are typically mined by smaller operations with shorter mine lives than the large South African reef mines. This variety of deposit type and mine scale across producer countries means the global supply picture is not monolithic: a disruption in one country does not automatically mean another can fill the gap quickly.
What pulls on it
The dominant use of chromium is in stainless steel, and the relationship is chemically non-negotiable: below roughly eleven percent chromium by weight, the protective passive oxide film that gives stainless steel its corrosion resistance does not reliably form. This threshold effect means that chromium cannot simply be used sparingly or diluted away when its price rises; a stainless steel grade either meets its chromium specification or it is not stainless steel. Beyond stainless, chromium is alloyed into a wide range of engineering steels — high-speed tool steels, bearing steels, chromium-molybdenum pressure-vessel steels — and into the nickel-based superalloys used in jet engines and gas turbines, where it contributes to oxidation resistance at high temperatures.
Demand for stainless steel tracks industrial activity broadly, and particularly the growth of construction, consumer goods, food processing and chemical plant in industrialising economies. The expansion of stainless steel production in China over the past two decades was the single largest change in the global chromium demand picture of that period, and China's trajectory continues to shape the market. A meaningful share of demand also comes from the chemical industry — chromium compounds in leather tanning and surface treatment — though regulatory pressure on hexavalent chromium in many jurisdictions has pushed some of this demand toward alternative finishing processes, causing a gradual erosion in those specific applications. Nuclear power, listed in the end-markets section, represents a relatively specialised but stable demand for chromium-containing reactor steels, where the corrosion resistance requirements are particularly stringent.
A sharp change in chromium demand would most plausibly follow from a large-scale shift in stainless steel consumption — either a sustained contraction in the construction and industrial sectors that drive stainless demand, or an unlikely but theoretically possible displacement of stainless by another corrosion-resistant material. Neither appears imminent based on the structural drivers of industrial development, though the efficiency of chromium use in steel — how many tonnes of chromite ore are required per tonne of stainless produced — is a variable that improves incrementally as steelmakers reduce process losses and recycle scrap more effectively.
Where it comes from in the rock
All ore minerals →These are the minerals that actually carry chromium. A deposit is only an orebody if one of them is concentrated enough to pay for digging it up.
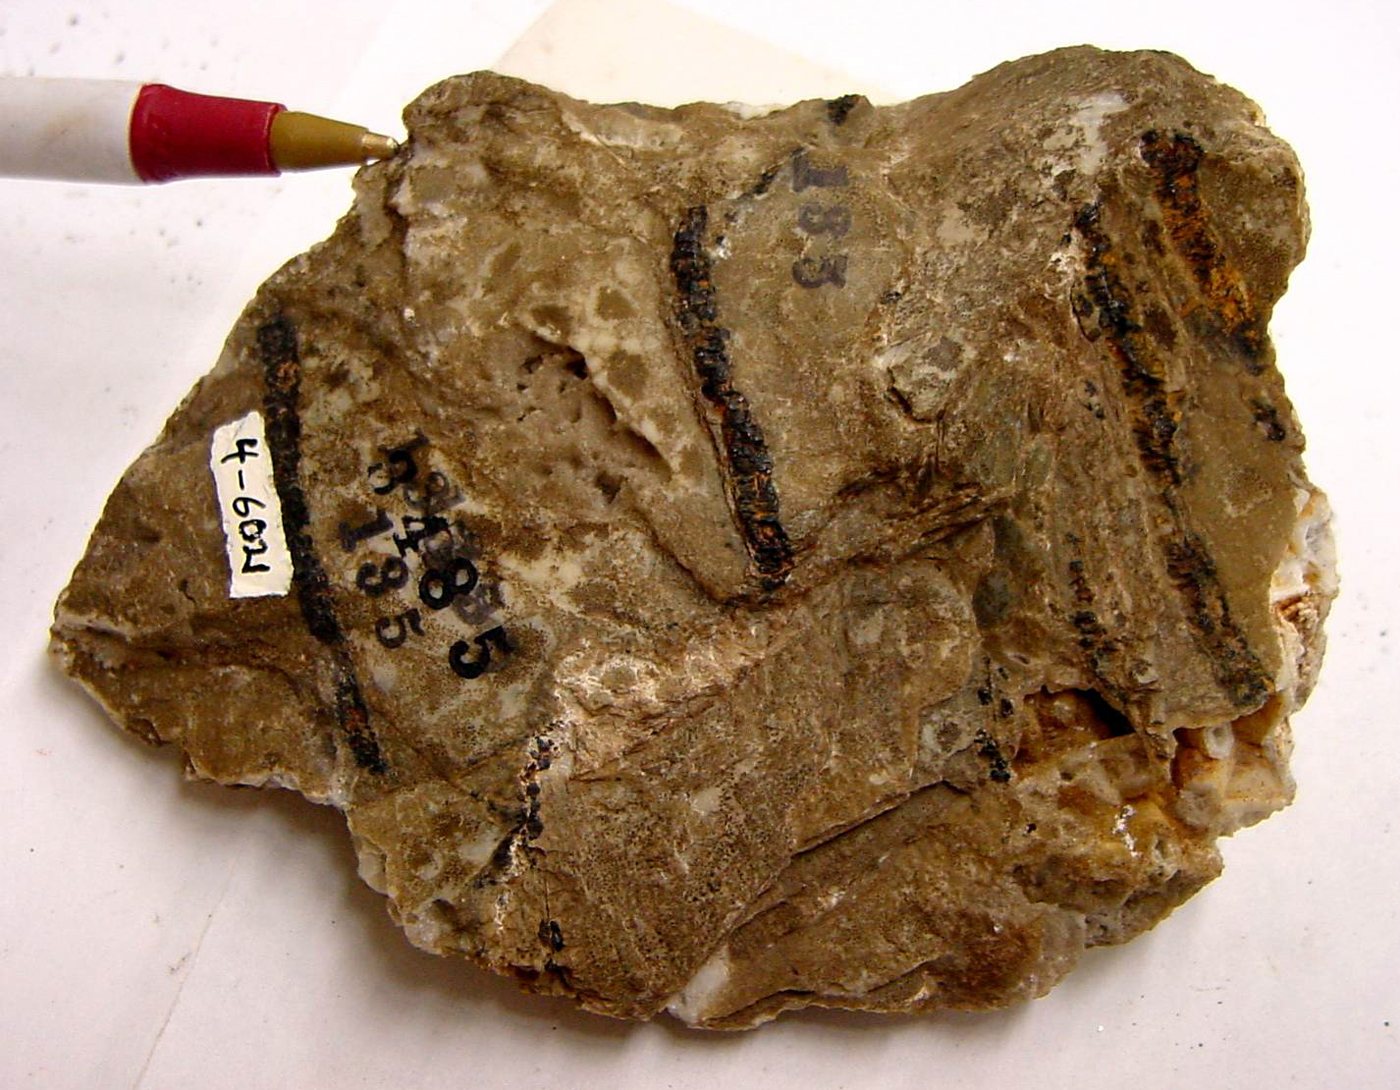
Chromite
The only ore of chromium, formed in layered mafic intrusions where it settles out in bands.
Who produces it
See it on a map →Mine production
Mine productionthousand metric tons 2025 (estimated) World total 51,000 thousand metric tons
USGS Mineral Commodity Summaries 2026 · USGS reports chromite ore gross weight, not contained chromium. · source ↗
Scroll the table sideways for the remaining columns.
| Country | Production | Share of world |
|---|---|---|
| South Africa | 23,000 | 45.1% |
| Turkey | 9,000 | 17.6% |
| Kazakhstan | 7,000 | 13.7% |
| Other countries | 3,000 | 5.9% |
| India | 3,000 | 5.9% |
| Zimbabwe | 2,000 | 3.9% |
| Brazil | 2,000 | 3.9% |
| Finland | 1,900 | 3.7% |
| United States | Zero | — |
| World total | 51,000 | 100% |
“Withheld” means the USGS suppressed the figure to avoid disclosing an individual company's data — it does not mean zero. Country rows do not always sum to the world total because the source rounds each figure independently and does not always break out an “other countries” line.
Who holds the reserves
Reserves: Cr2O3 content
Reserves: Cr2O3 contentthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · source ↗
| Country | Reserves | Share of world |
|---|---|---|
| South Africa | 110,000 | 20.4% |
| Kazakhstan | 100,000 | 18.5% |
| Zimbabwe | 78,000 | 14.4% |
| India | 27,000 | 5.0% |
| Finland | 16,000 | 3.0% |
| Turkey | 5,700 | 1.1% |
| Brazil | 1,000 | 0.2% |
| United States | 630.0 | 0.1% |
| Other countries | Not applicable | — |
| World total | >540,000 | 100% |
The source publishes this world total as a bound rather than a point figure, so the shares in the last column are themselves bounds.
Reserves: Ore
Reserves: Orethousand metric tons 2024
USGS Mineral Commodity Summaries 2026 · source ↗
| Country | Reserves | Share of world |
|---|---|---|
| South Africa | 350,000 | 29.2% |
| Kazakhstan | 230,000 | 19.2% |
| Zimbabwe | 140,000 | 11.7% |
| India | 79,000 | 6.6% |
| Finland | 63,000 | 5.2% |
| Turkey | 27,000 | 2.2% |
| United States | 8,500 | 0.7% |
| Brazil | 3,900 | 0.3% |
| Other countries | Not applicable | — |
| World total | >1,200,000 | 100% |
The source publishes this world total as a bound rather than a point figure, so the shares in the last column are themselves bounds.
Price
Price: Chromium metal (gross weight), dollars per pound
Annual averagedollars per pound
Basis: Price: Chromium metal (gross weight), dollars per pound. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
Price: Chromite ore (gross weight), dollars per metric ton
Annual averagedollars per metric ton
Basis: Price: Chromite ore (gross weight), dollars per metric ton. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
Price: Ferrochromium (chromium content), dollars per pound
Annual averagedollars per pound
Basis: Price: Ferrochromium (chromium content), dollars per pound. Annual averages as published in USGS Mineral Commodity Summaries 2026 · source ↗. These are reference annual averages, not a live market quote.
What it is used for
All end markets →| End market | What it does there | Importance |
|---|---|---|
| Nuclear Power | Corrosion resistance in reactor steels | Important |
Follow it across the borders
All journeys →Where a consignment of this material actually goes — every country, every custodian, and what is left behind at each step.
New Caledonian laterite to stainless steel An island that smelts its own ore, and pays for it with the most expensive electricity in the industry.