Bu nedir?
Minerals people want because of how they look — hardness, clarity and colour, priced on rarity rather than on tonnage.
Neden önemli?
Gem mining is unusual in the sector: much of it is artisanal, values per tonne are extreme, and provenance rather than assay determines price.
Where it is in the Earth
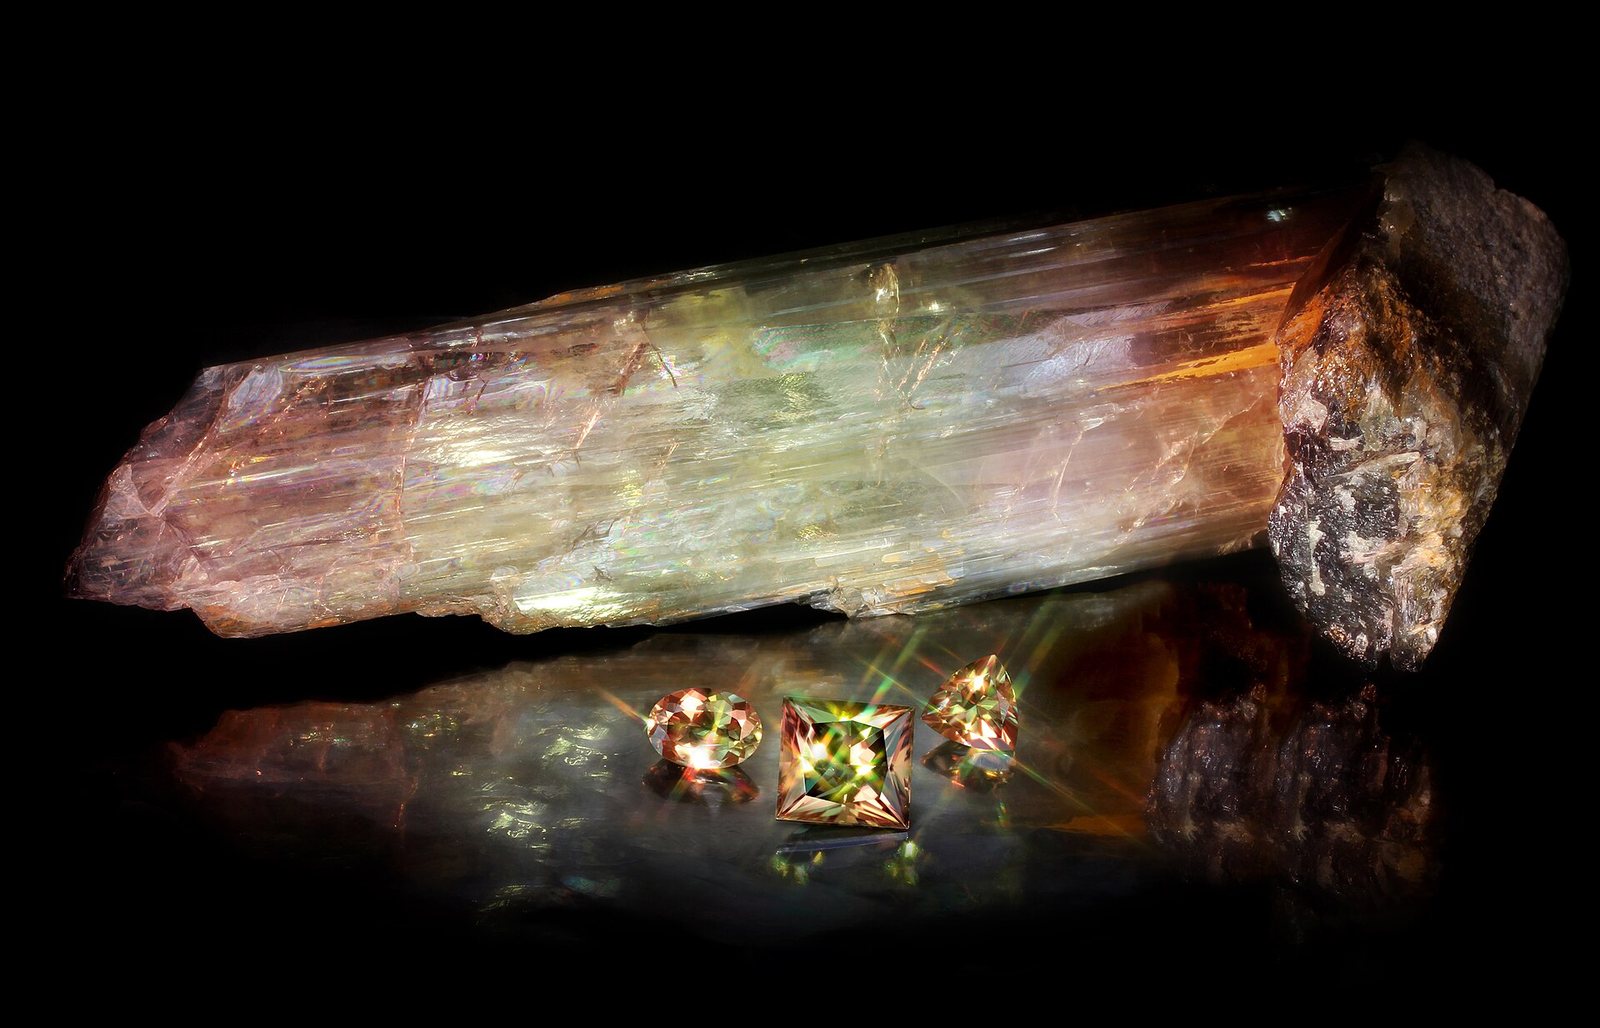
A gemstone is a mineral — or occasionally an organic material such as amber or pearl — that combines optical appeal with sufficient hardness to survive cutting and wear. Hardness here has a precise meaning: mineralogists measure it on the Mohs scale, where diamond sits at the top and materials below a certain point scratch too easily to hold a polish in daily use. Colour, transparency and the way a stone bends and splits light (its refractive index and dispersion) determine whether a mineral is worth the lapidary's attention. Rarity then determines whether it is worth the buyer's money.
Most gem minerals form under conditions that are uncommon in the crust. Diamond, for example, crystallises at extreme pressure and temperature deep in ancient, stable continental cores called cratons. It reaches the surface only when a rare, fast-moving magma called kimberlite or lamproite punches upward from depth without giving the diamond time to convert to graphite. The pipe-shaped bodies of kimberlite that remain at the surface — found in Russia, Botswana, Angola, Canada and southern Africa — are therefore the primary targets for diamond exploration. Rubies and sapphires (both varieties of the mineral corundum) form in metamorphic rocks — rocks recrystallised by heat and pressure — or in alkaline igneous intrusions, and tend to concentrate in the alluvial gravels that accumulate as those rocks weather and erode over geological time. Emeralds form in a different setting again, typically where hydrothermal fluids rich in beryllium interact with chromium-bearing schists.
Secondary, or alluvial, deposits matter enormously in gem mining. Weathering liberates hard, chemically resistant stones from their host rock, and rivers and ocean currents sort and concentrate them by density. Namibia's marine diamond deposits, where wave action has winnowed stones along the Atlantic coastline, are a well-known example. These placer deposits are often worked by small operators or individual artisanal miners, because the capital requirement for shallow alluvial digging is far lower than for underground hard-rock mining. The geographic spread of production shown in the table — stretching from Siberia to West Africa to northern Canada — reflects the equally wide spread of the cratons, metamorphic belts and ancient drainage systems that concentrate gem minerals.
Getting it out
Diamond mining, which dominates production by carat volume as the tables show, uses two broad approaches depending on where the stones sit. Open-pit mining — removing rock in a widening, stepped excavation from the surface downward — works well in the early life of a kimberlite pipe, when the orebody is shallow. As the pit deepens, the economics shift, and mines transition to underground methods, driving tunnels to reach ore blocks below. In both cases the proportion of waste rock moved per carat recovered is very large, because even a rich diamond deposit contains only a small weight of diamond per tonne of host rock. The grade — the number of carats found in each tonne of ore — is the single most watched number in diamond mine economics, and grades vary considerably between deposits and even within a single pipe.
Alluvial and marine deposits use different methods. On land, alluvial miners may work river gravels with little more than hand tools and a sieve; this is the characteristic mode of artisanal and small-scale mining that accounts for a meaningful fraction of gem production worldwide, particularly in West and Central Africa. Marine mining off Namibia uses purpose-built vessels that either vacuum sediment from the seafloor or deploy divers with suction hoses in shallow water — an unusual and capital-intensive method justified by the exceptional quality of the stones recovered there. For coloured gemstones — rubies, sapphires, emeralds, tanzanite — underground and artisanal pit methods dominate, often at very small scale in countries such as Tanzania, Zimbabwe and Sierra Leone.
The concept of grade in gem mining carries a complication that does not arise in base-metal or even gold mining. Two deposits with identical carat grades can have vastly different economic values if one produces large, clear, well-coloured stones and the other produces small, included or off-colour material. This is why the tables on this page report production by value rather than by weight alone, and why any carat-weight figure must be read with caution. Moving waste to reach a kimberlite pipe is expensive; moving waste to reach an alluvial deposit that then yields low-quality material can make an operation unviable even if the carat count looks adequate.
What pulls on it
The demand for gemstones is driven by jewellery, which accounts for the overwhelming majority of consumption by value. Unlike most industrial materials, the purchase decision rests on perceived beauty, cultural meaning and social signalling rather than technical specification. Diamonds have historically been associated with engagement rings in Western markets, a pattern that was deliberately cultivated in the twentieth century and became genuinely embedded in consumer expectations. Coloured gemstones — rubies, emeralds, sapphires and a long tail of others — serve similar functions in jewellery but are also prized by collectors who treat fine stones as portable, concentrated stores of aesthetic and monetary value.
Consumer markets in China and India have grown in importance as a share of global demand, and the tastes of buyers in those markets — which have their own long traditions of gem use, often favouring jade, rubies and pearls — influence what qualities and types of stone command premiums. The United States remains a very large consuming market, and the import reliance figure in the data confirms that virtually all gem material consumed in the United States arrives from abroad. Demand is sensitive to general economic confidence, since jewellery is a discretionary purchase, and it is also sensitive to fashion: a stone that falls out of favour in bridal jewellery faces a structural reduction in demand regardless of its intrinsic qualities.
The growth of laboratory-grown diamonds represents a genuine structural shift in one segment of demand. Synthetic stones are chemically and physically identical to mined ones, and as their price has declined they have captured a growing share of the market for smaller, commercial-quality diamonds used in jewellery. Whether this displaces mined diamond demand depends partly on whether consumers come to regard origin — mined versus grown — as a meaningful distinction, and partly on how far prices diverge. For very large, rare, naturally coloured diamonds, the provenance and uniqueness of the stone is itself part of the value, and laboratory production is unlikely to substitute there.
Kim üretiyor
Haritada gör →Mine production
Mine production thousands of carats 2025 (tahmini) Dünya toplamı 69,000 thousands of carats
USGS Mineral Commodity Summaries 2026 · Reported by value, not weight, because carat totals say nothing about worth. · kaynak ↗
Kalan sütunlar için tabloyu yatay kaydırın.
| Ülke | Üretim | Dünya payı |
|---|---|---|
| Russia | 21,000 | 30.4% |
| Angola | 13,000 | 18.8% |
| Canada | 13,000 | 18.8% |
| Botswana | 13,000 | 18.8% |
| Namibia | 2,300 | 3.3% |
| South Africa | 2,100 | 3.0% |
| Congo (Kinshasa) | 2,000 | 2.9% |
| Lesotho | 700.0 | 1.0% |
| Zimbabwe | 530.0 | 0.8% |
| Sierra Leone | 460.0 | 0.7% |
| Ghana | 330.0 | 0.5% |
| Tanzania | 320.0 | 0.5% |
| Other countries | 320.0 | 0.5% |
| United States | Zero | — |
| Dünya toplamı | 69,000 | 100% |
"Gizli tutulmuş", USGS'nin tek bir şirketin verisini ifşa etmekten kaçınmak amacıyla rakamı yayımlamadığı anlamına gelir; sıfır anlamına gelmez. Kaynak her rakamı bağımsız olarak yuvarladığı ve her zaman "diğer ülkeler" satırını ayrıştırmadığı için ülke satırları her zaman dünya toplamına eşit olmayabilir.
Rezervleri kim elinde bulunduruyor
Reserves
Reserves thousands of carats 2025
USGS Mineral Commodity Summaries 2026 · kaynak ↗
| Ülke | Rezervler | Dünya payı |
|---|---|---|
| Russia | 750,000 | 37.5% |
| Botswana | 250,000 | 12.5% |
| Congo (Kinshasa) | 150,000 | 7.5% |
| Angola | 150,000 | 7.5% |
| Other countries | 120,000 | 6.0% |
| Canada | 110,000 | 5.5% |
| South Africa | 87,000 | 4.3% |
| Zimbabwe | 56,000 | 2.8% |
| United States | Not applicable | — |
| Ghana | Not applicable | — |
| Lesotho | Not applicable | — |
| Namibia | Not applicable | — |
| Sierra Leone | Not applicable | — |
| Tanzania | Not applicable | — |
| Dünya toplamı | >2,000,000 | 100% |
Kaynak bu dünya toplamını bir nokta değer olarak değil, bir aralık olarak yayımlamaktadır; dolayısıyla son sütundaki paylar da birer aralıktır.