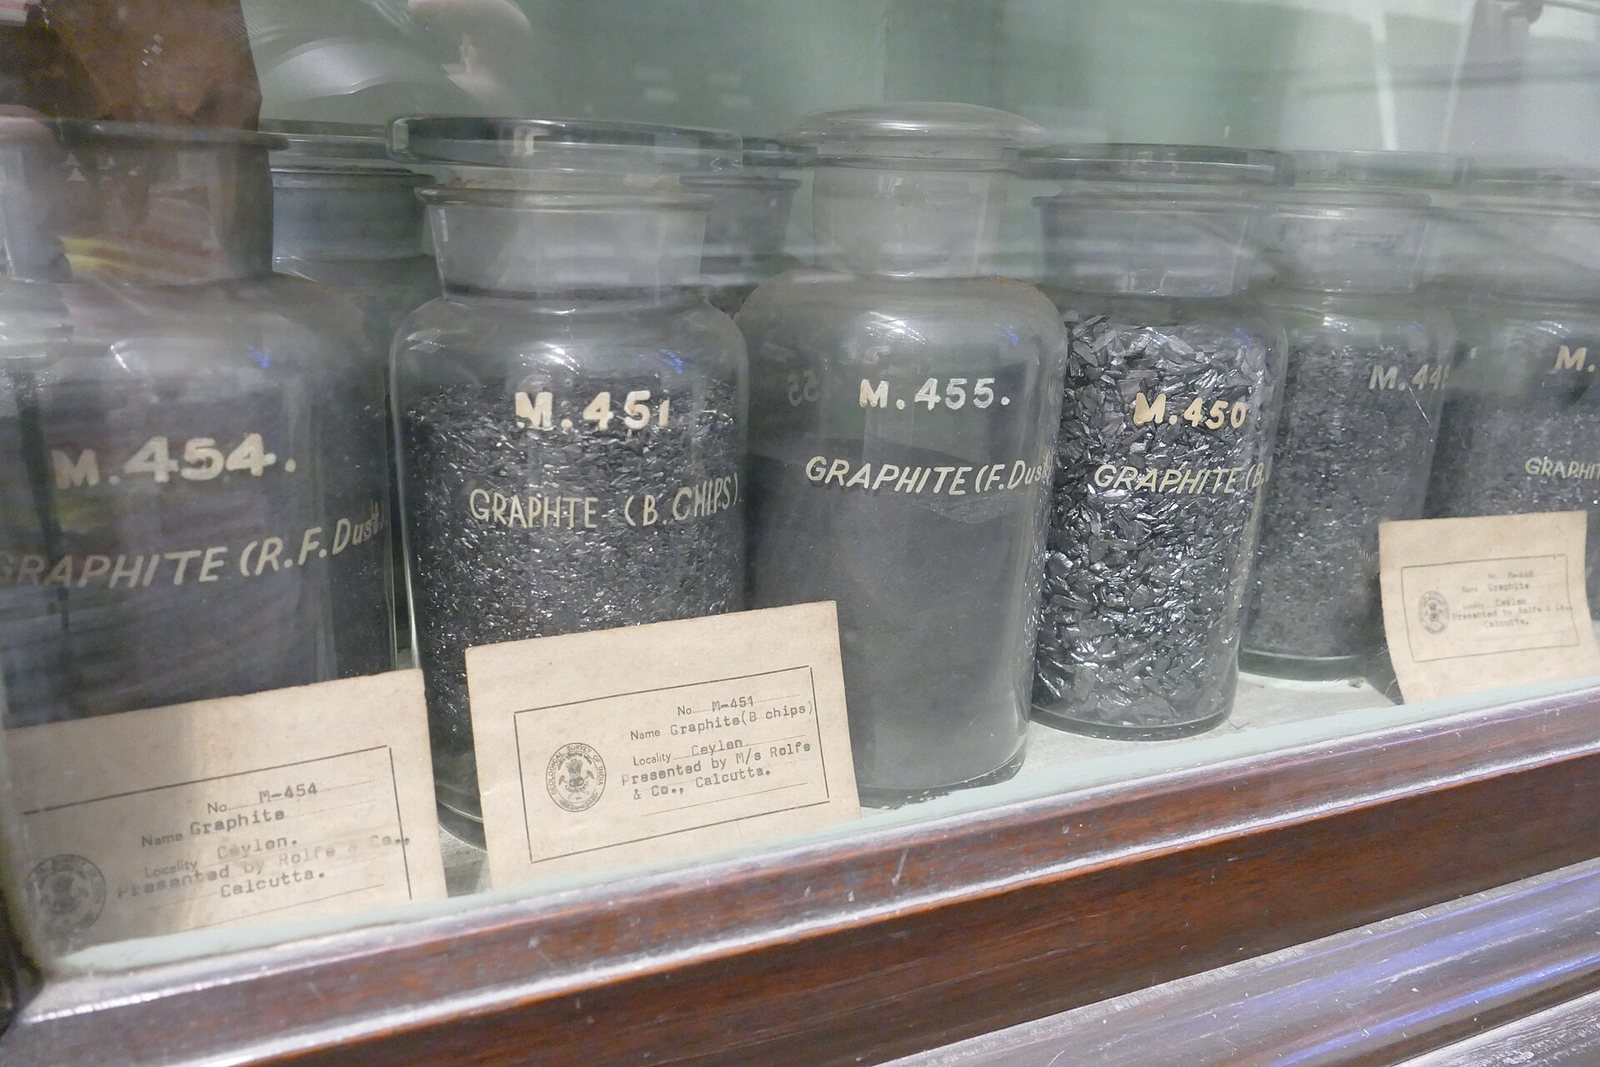
Đây là gì?
Pure carbon in soft, slippery sheets — the same stuff as pencil lead — and the material that holds the lithium when a battery is charged.
Tại sao điều này quan trọng?
Every lithium-ion cell has a graphite anode, and by weight there is more graphite in a battery than lithium. It is also the electrode that makes electric-arc steelmaking possible.
Where it is in the Earth
Graphite is a crystalline form of carbon, meaning its atoms are arranged in flat, parallel sheets held loosely together — which is why it feels slippery and leaves marks on paper. It reaches mineable concentrations through two quite different geological routes, and which route produced a deposit largely determines what the graphite looks like and what it is good for.
The more common route is metamorphic: ancient organic matter, buried deeply and subjected to intense heat and pressure over millions of years, loses its hydrogen, oxygen and other elements and recombines as pure carbon in a crystalline lattice. The result is flake graphite, found in metamorphic rocks such as schists, gneisses and marbles. These deposits tend to be large and geographically widespread; they account for the great majority of what is mined. The other route is igneous: carbon-bearing fluids moving through fractures in rock can precipitate graphite directly, producing vein or lump deposits. Sri Lanka is the world's principal source of this rarer, higher-purity vein type, which commands a notably higher price than flake, as the import value data on this page shows. A third variety, amorphous graphite, is not truly amorphous in the strict chemical sense — it is microcrystalline flake graphite so finely divided that individual crystals are invisible. It forms from coal seams that have been baked by igneous intrusions.
The reason deposits cluster where they do follows from these origins. The great metamorphic belts of eastern China, the East African coast, Brazil's ancient basement rocks, and parts of India and Russia all host the kind of deeply buried, carbon-rich sediments that metamorphism converts into flake graphite. China's concentration reflects the sheer scale of its Precambrian metamorphic terranes — the very old rock formations that cover large parts of the country's interior and north-east. East African deposits in Madagascar, Tanzania and Mozambique have attracted considerable attention because they lie within similar ancient geological provinces and carry flake sizes that suit battery applications.
Getting it out
Most graphite is mined by open-pit methods, which means removing the soil and rock sitting above the ore body in a series of descending steps called benches, then extracting the ore itself. Open-pit mining is preferred when the deposit lies close to the surface and extends broadly in area, because the economics of moving large volumes of material are far more manageable in the open air than underground. Underground mining is used where the ore body is narrow, deep, or where surface conditions make open-pit impractical; some older Chinese and Indian operations follow this pattern.
Ore grade is the single most important number governing whether a deposit can be mined at all. For flake graphite, the tables on this page note that typical run-of-mine ore contains between five and fifteen percent graphitic carbon. That means for every tonne of ore dug up, somewhere between 850 and 950 kilograms is waste rock that must be moved, crushed and disposed of. The ratio of waste to ore — called the strip ratio in open-pit mining — determines a great deal of the cost. A deposit with a higher grade moves less waste per tonne of graphite recovered, which directly affects whether it can survive periods of lower prices. Vein graphite in Sri Lanka is an exception: grades are substantially higher, which is part of why it has been mined continuously from underground workings for well over a century despite the labour-intensive nature of the method.
Unlike metals such as copper or lithium, graphite is not extracted from a chemical compound but recovered as the mineral itself. There is no smelting step required to liberate the metal from its ore; the challenge instead is separating intact graphite flakes from the surrounding rock without breaking them. Flake size matters enormously to buyers, particularly for battery applications, so mining practice is shaped as much by the need to preserve crystal integrity as by the need to move tonnes efficiently.
What pulls on it
Graphite has two distinct demand bases that operate largely independently of each other. The older and still very large use is in steel and foundry applications, principally as electrodes in electric-arc furnaces — the vessels that melt scrap steel using enormous electrical currents — and as refractory linings and lubricants in metallurgical processes. This segment has been relatively stable over decades, tied to the rate of steel production from scrap rather than from iron ore, and it consumes a different product from the battery sector: primarily synthetic graphite made from petroleum coke, or large-flake natural graphite in specific refractory applications.
The newer and faster-growing use is as the anode material in lithium-ion batteries. Every lithium-ion cell, regardless of the cathode chemistry used, requires a graphite anode, and by weight graphite is the largest single active material in the cell. The material-intensity figures on this page give concrete meaning to this: a single battery pack of the kind used in an electric vehicle requires tens of kilograms of graphite anode material. As electric vehicle production has grown, battery demand for graphite has grown with it. Consumer electronics and grid-scale energy storage add further to this pull, though the per-unit quantities involved are smaller than in vehicle applications.
For demand to shift sharply, one of two things would need to happen: either the lithium-ion battery chemistry itself would have to change — replacing graphite anodes with a material such as silicon or lithium metal — or steelmaking patterns would have to shift away from electric-arc furnace routes. Silicon anodes are an active area of research precisely because silicon holds more lithium per unit volume than graphite, but replacing graphite entirely is a different matter from blending small amounts of silicon into a graphite anode, which is already done. Battery chemistries that store energy without a graphite anode do exist — sodium-ion batteries use alternative anode materials — but their penetration into the market remains, as of the data period covered here, modest. The more immediate question for flake graphite is not whether demand will fall but whether supply can be built outside China quickly enough to track growth in battery manufacturing in other regions.
Turning ore into product Cấp độ 3
The processing route for flake graphite begins with comminution — the staged crushing and grinding of ore to break apart the rock matrix and free individual graphite flakes. This is where the tension between liberation and preservation is most acute. Grinding too coarsely leaves graphite locked inside rock particles; grinding too finely destroys the large flakes that attract a premium and are required for spherical anode material. Operators typically use rod mills or carefully controlled ball-mill circuits, and may run multiple passes at progressively finer settings, screening out liberated flake at each stage to protect it from further size reduction.
The freed flake is then concentrated by froth flotation, a process that exploits graphite's natural tendency to repel water. Air is bubbled through a slurry of ground ore mixed with reagents; graphite particles attach to the bubbles and float to the surface as a froth, while silicate and other gangue minerals sink. Multiple flotation stages — roughing, cleaning, recleaning — are needed to raise carbon purity from the five-to-fifteen percent range in raw ore to the ninety-four to ninety-seven percent range that industrial buyers require. Losses occur at each stage, both through fine graphite that escapes with the tailings and through flakes degraded to a smaller size class than their original specification. Recovery rates and the proportions of large, medium and small flake in the final product are the two critical measures of a processing plant's performance.
For battery anode material, the processing chain extends considerably further. Concentrate is spheronised — shaped into roughly spherical particles by mechanical milling — which generates a substantial quantity of fine graphite as a by-product. The spheres are then coated, typically with a thin layer of carbon deposited by chemical vapour or pitch-based treatment, to control how lithium ions enter and exit the particle during charge and discharge. Finally, for the highest-purity specifications, graphite undergoes thermal purification at temperatures approaching 3,000 degrees Celsius, which volatilises remaining mineral impurities. Each of these downstream steps adds cost and is, for now, overwhelmingly concentrated in China. Separating mining from this downstream processing chain is the central challenge facing producers outside China who want to supply battery manufacturers directly.
Substitution and recycling Cấp độ 3
In its steelmaking electrode role, the main substitute for natural graphite is synthetic graphite — manufactured by baking petroleum coke or coal-tar pitch at very high temperatures until the carbon reorganises into a graphitic structure. Synthetic graphite generally outperforms natural graphite in electrode applications because its properties are more uniform and controllable, which is why it dominates that market. The constraint on substitution runs in the other direction: synthetic graphite is energy-intensive to make and depends on petroleum coke as a feedstock, so it carries its own supply chain exposure. In battery anodes, natural flake graphite and synthetic graphite have competed directly, with the choice between them depending on the required electrochemical performance, cost targets and the buyer's supply-chain preferences. Some cell manufacturers blend the two. Fully displacing graphite in the anode with silicon is constrained by silicon's tendency to expand and contract dramatically during charge and discharge, which degrades the cell over repeated cycles; this remains an engineering problem that has not been resolved at commercial scale for pure-silicon anodes.
Recycling of battery graphite is technically possible but remains at an early stage of commercial deployment. Most lithium-ion battery recycling processes today prioritise recovering cobalt, nickel and lithium from the cathode, because those metals carry higher unit values. The graphite anode material — often called black mass once the cell is shredded — tends to be treated as a lower-value residue or lost during processing. Recovering it in a form suitable for reuse in new anodes requires additional purification steps, and the economics have not yet driven widespread recovery. As battery recycling volumes increase with the first large waves of end-of-life electric vehicle batteries, this picture may evolve, but the data available now do not support a quantitative estimate of return flows.
Nguồn gốc của nó trong đá
Tất cả khoáng vật quặng →Đây là các khoáng sản thực sự mang lại graphite. Một mỏ khoáng chỉ là thân quặng khi một trong số chúng có hàm lượng đủ cao để bù đắp chi phí khai thác.
Ai sản xuất nó
Xem trên bản đồ →Mine production
Mine productionmetric tons 2025 (ước tính) Tổng toàn cầu 1,800,000 metric tons
USGS Mineral Commodity Summaries 2026 · USGS reports natural graphite only. Synthetic graphite, made by baking petroleum coke at ~3,000 C, is a separate and larger industry. · nguồn ↗
Cuộn bảng sang ngang để xem các cột còn lại.
| Quốc gia | Sản lượng | Tỷ phần thế giới |
|---|---|---|
| China | 1,400,000 | 77.8% |
| Madagascar | 80,000 | 4.4% |
| Tanzania | 75,000 | 4.2% |
| Brazil | 65,000 | 3.6% |
| Mozambique | 60,000 | 3.3% |
| Russia | 25,000 | 1.4% |
| India | 17,000 | 0.9% |
| Korea, North | 8,000 | 0.4% |
| Canada | 8,000 | 0.4% |
| Norway | 6,600 | 0.4% |
| Sri Lanka | 3,200 | 0.2% |
| Turkey | 2,200 | 0.1% |
| Ukraine | 800.0 | 0.0% |
| Mexico | 740.0 | 0.0% |
| Vietnam | 500.0 | 0.0% |
| Korea, Republic of | 500.0 | 0.0% |
| Austria | 200.0 | 0.0% |
| Germany | 140.0 | 0.0% |
| United States | Zero | — |
| Tổng toàn cầu | 1,800,000 | 100% |
"Withheld" có nghĩa là USGS đã ẩn số liệu để tránh tiết lộ dữ liệu của một công ty riêng lẻ — không có nghĩa là bằng không. Tổng các hàng theo quốc gia không phải lúc nào cũng bằng tổng toàn cầu vì nguồn làm tròn từng số liệu một cách độc lập và không phải lúc nào cũng tách riêng dòng "các quốc gia khác".
Ai nắm giữ trữ lượng
Reserves
Reservesmetric tons 2025
USGS Mineral Commodity Summaries 2026 · nguồn ↗
| Quốc gia | Trữ lượng | Tỷ phần thế giới |
|---|---|---|
| China | 100,000,000 | 32.3% |
| Brazil | 74,000,000 | 23.9% |
| Madagascar | 27,000,000 | 8.7% |
| Mozambique | 25,000,000 | 8.1% |
| Tanzania | 18,000,000 | 5.8% |
| Russia | 14,000,000 | 4.5% |
| Vietnam | 9,700,000 | 3.1% |
| India | 8,600,000 | 2.8% |
| Turkey | 6,900,000 | 2.2% |
| Canada | 5,900,000 | 1.9% |
| Mexico | 3,100,000 | 1.0% |
| Korea, North | 2,000,000 | 0.6% |
| Korea, Republic of | 1,800,000 | 0.6% |
| Sri Lanka | 1,500,000 | 0.5% |
| Norway | 600,000 | 0.2% |
| United States | s | — |
| Austria | s | — |
| Germany | s | — |
| Ukraine | s | — |
| Tổng toàn cầu | 310,000,000 | 100% |
Giá
average unit value of imports, dollars per metric ton at foreign ports: Amorphous
Trung bình nămdollars per metric ton
Cơ sở: average unit value of imports, dollars per metric ton at foreign ports: Amorphous. Trung bình năm theo công bố trong USGS Mineral Commodity Summaries 2026 · nguồn ↗. Đây là mức trung bình hàng năm tham khảo, không phải báo giá thị trường trực tiếp.
average unit value of imports, dollars per metric ton at foreign ports: Lump and chip (Sri Lanka)
Trung bình nămdollars per metric ton
Cơ sở: average unit value of imports, dollars per metric ton at foreign ports: Lump and chip (Sri Lanka). Trung bình năm theo công bố trong USGS Mineral Commodity Summaries 2026 · nguồn ↗. Đây là mức trung bình hàng năm tham khảo, không phải báo giá thị trường trực tiếp.
average unit value of imports, dollars per metric ton at foreign ports: Flake
Trung bình nămdollars per metric ton
Cơ sở: average unit value of imports, dollars per metric ton at foreign ports: Flake. Trung bình năm theo công bố trong USGS Mineral Commodity Summaries 2026 · nguồn ↗. Đây là mức trung bình hàng năm tham khảo, không phải báo giá thị trường trực tiếp.
Nơi nó được chế biến và tinh luyện
| Nhà máy | Loại | Giai đoạn | Quốc gia | Vai trò |
|---|---|---|---|---|
| CATL Ningde Plants | Gigafactory | Thành phần | China | Đầu vào |
| Gigafactory Nevada | Gigafactory | Thành phần | United States | Đầu vào |
Công dụng của nó
Tất cả thị trường đầu ra →| Thị trường đầu ra | Chức năng của nó ở đó | Tầm quan trọng |
|---|---|---|
| Electric Vehicles | The anode — the heaviest active material in the cell | Định nghĩa |
| Consumer Electronics | Battery anode | Định nghĩa |
| Grid Storage | Anode | Định nghĩa |
Một công nghệ cần bao nhiêu
| Công nghệ | Đại lượng | Báo giá | Cơ sở |
|---|---|---|---|
| LFP Lithium-Ion Battery | 55.00–85.00 kg | per 75 kWh pack | Anode active material |
| NMC Lithium-Ion Battery Roughly 1 kg of anode material per kWh. | 50.00–80.00 kg | per 75 kWh pack | Anode active material |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. Chạy các con số này ở bất kỳ quy mô nào trong máy tính vật liệu →
Kiểm soát xuất khẩu
| Quốc gia | Kiểm soát | Áp dụng cho |
|---|---|---|
| China | Export licensing requirement for materials and technologies | Antimony (2024), bismuth (2025), synthesized diamond (2025), gallium (2023), germanium (2023), graphite (2023), indium (2025), magnesium materials (2024), molybdenum (2025), rare earths (2025), silver (2026), tellurium (2025), tungsten (2025), and items related to lithium batteries and artificial graphite anode materials (2025). ↗ |
| Namibia | Export ban | Ores and concentrates of cobalt, graphite, lithium, manganese, and rare earths (2023). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.