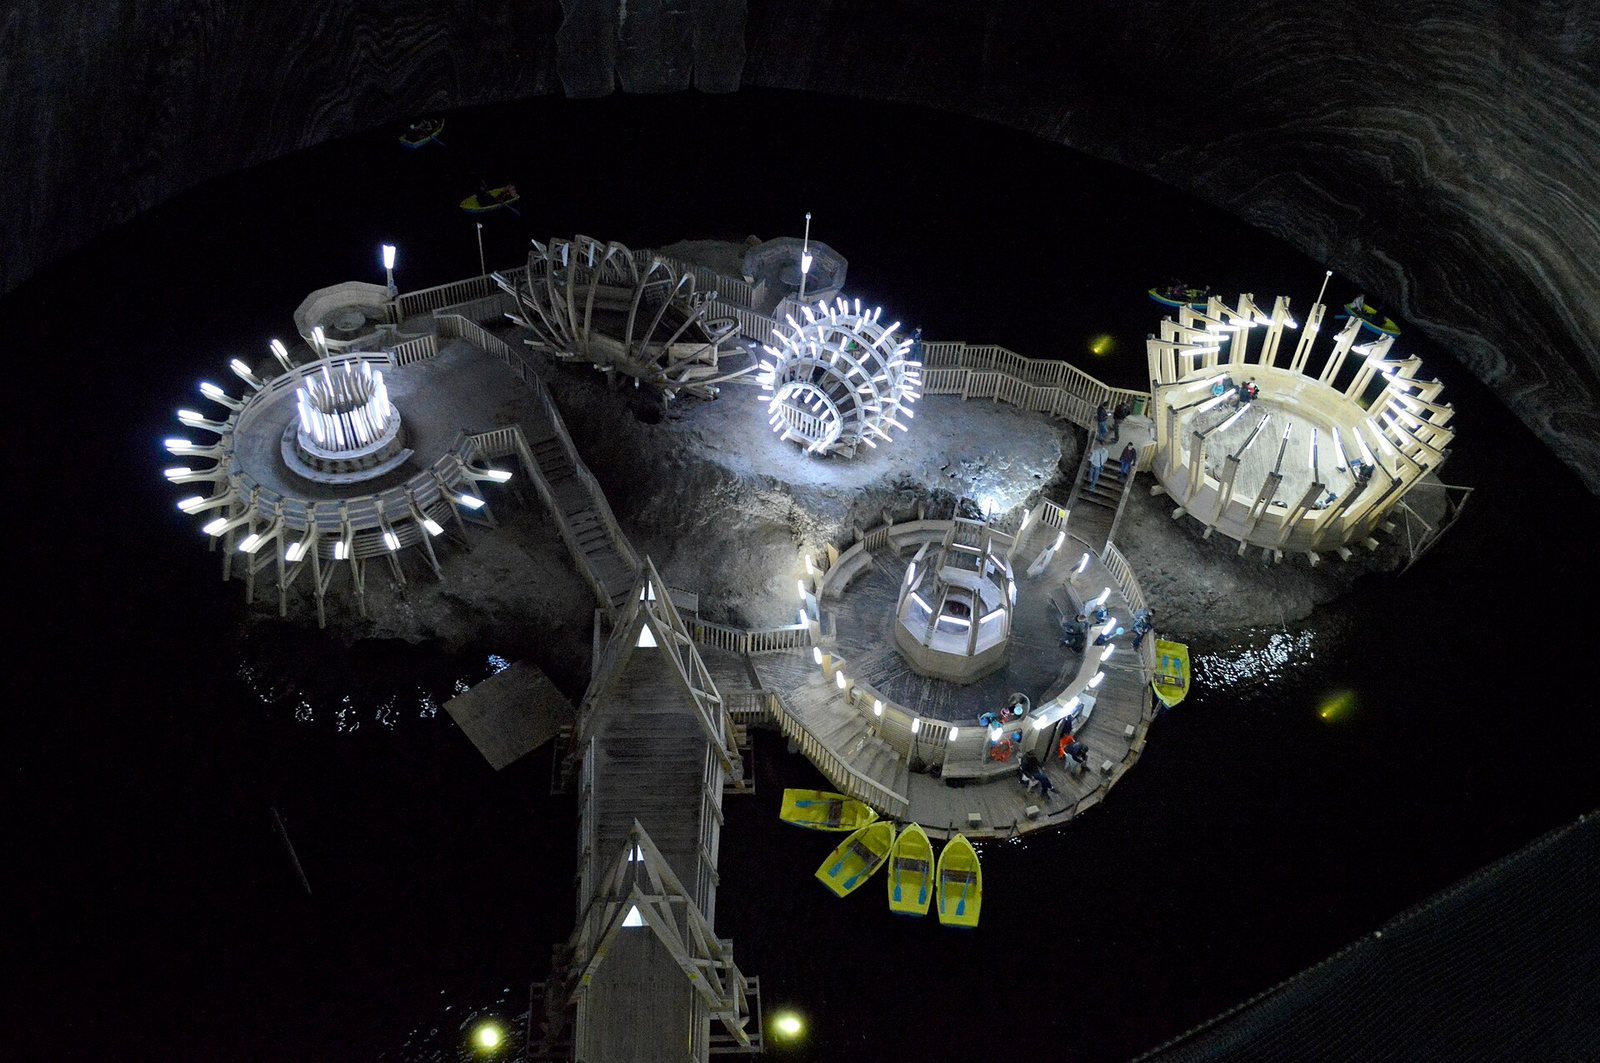
Qu'est-ce que c'est ?
Sodium chloride — the seasoning on a table, and the feedstock for the chlorine and caustic soda that most of the chemical industry begins with.
Pourquoi est-ce important ?
Chlor-alkali chemistry from salt underpins PVC, water treatment, paper and pharmaceuticals. Food use is a small fraction of it.
Where it is in the Earth
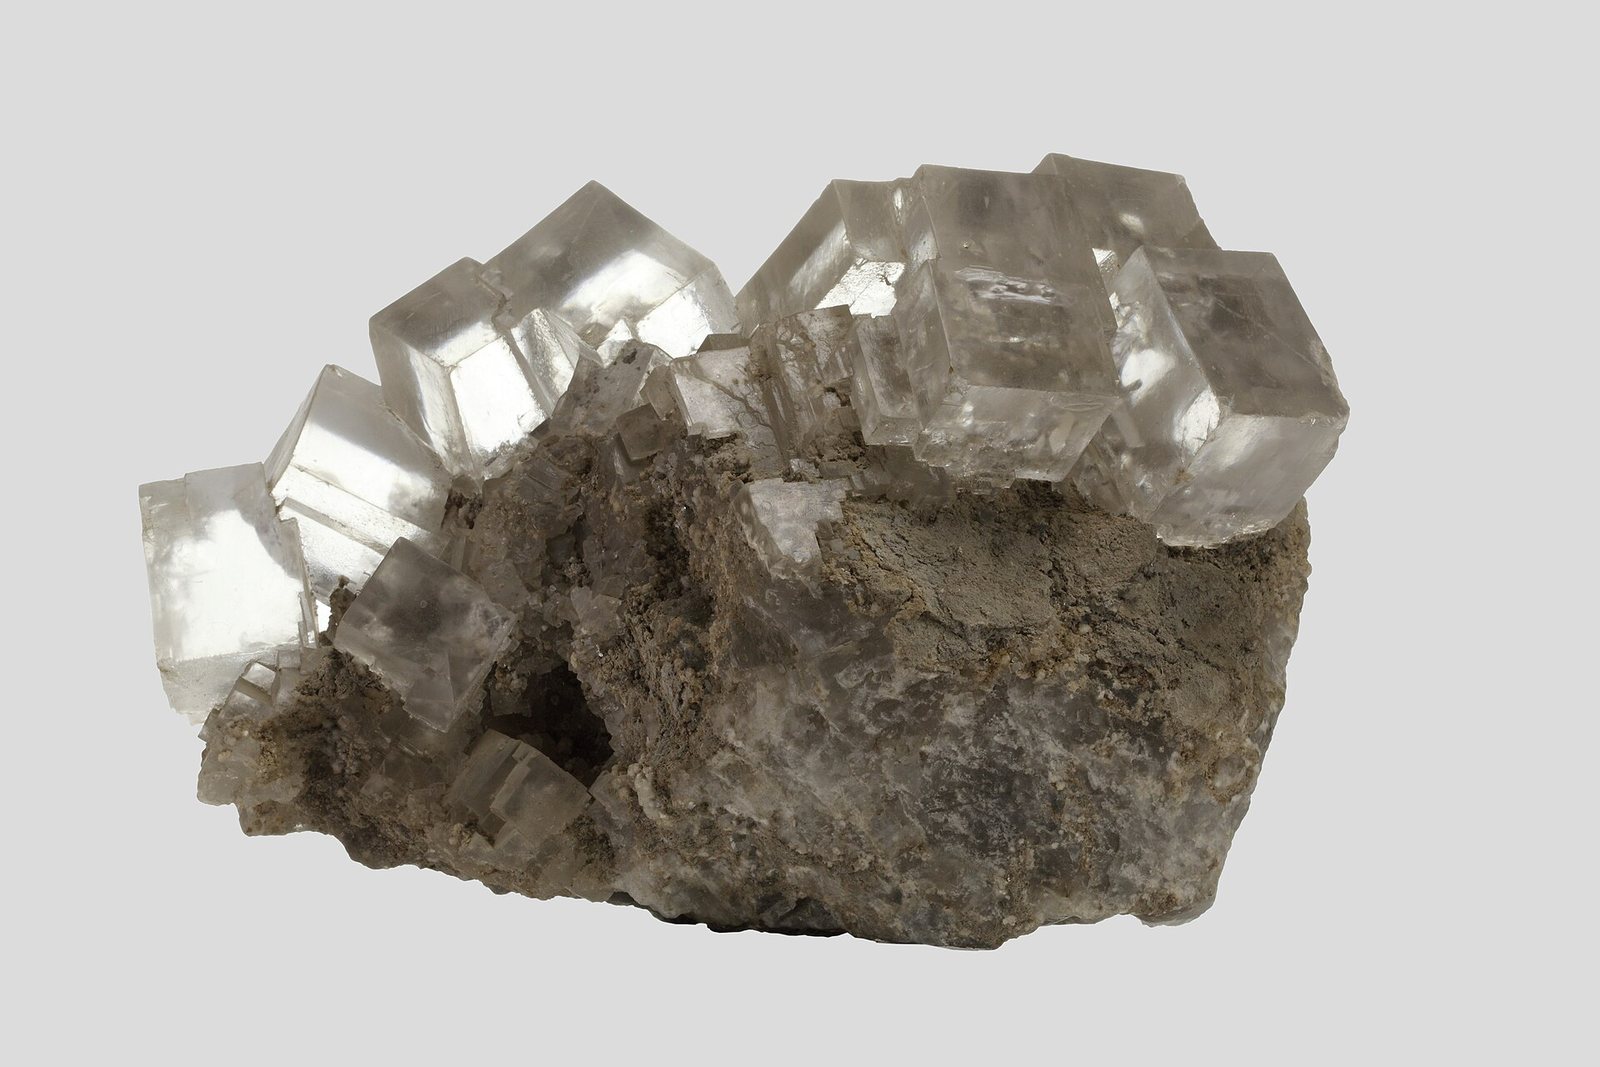
Salt — mineralogically halite, a simple compound of sodium and chlorine — forms wherever a body of seawater or a saline lake becomes enclosed and then evaporates. As the water column drops, minerals precipitate in a broadly predictable sequence: carbonates first, then sulfates, and finally chlorides including halite. Because this process has operated repeatedly across geological time, thick halite beds are found on every continent, buried beneath younger sediments at depths ranging from near the surface to several kilometres down. The deposits sit where they sit because ancient seas once sat there: the great salt basins of North America, Europe and China all trace back to enclosed marine embayments of Permian, Triassic or Devonian age.
Once buried, halite behaves unusually for a rock. It flows slowly under pressure, a property called plasticity, and because it is less dense than most overlying sediments it tends to rise through them over millions of years, forming diapirs — dome-shaped intrusions that push upward like slow columns of rising dough. These salt domes are geologically important for two reasons: they can trap oil and gas in the surrounding rocks, and they are themselves minable either by conventional underground methods or by dissolving the salt in place with injected water. Where evaporite sequences reach the surface or shallow depths in arid regions, surface expressions such as salt flats and playas also become economically exploitable.
A separate but equally significant source is present-day evaporation of seawater or brine from saline lakes. Coastal solar salt works and inland brine fields are not geological deposits in the conventional sense — they are ongoing industrial processes that replicate the original geological mechanism. Australia, India, Chile and Mexico all draw heavily on this route, using large shallow ponds and solar energy to do what ancient basins once did over geological time.
Getting it out
Salt reaches the surface through three distinct methods, and the choice between them is dictated almost entirely by the physical form of the deposit. Where halite beds are thick and pure enough to justify underground access, conventional room-and-pillar mining is used: galleries are cut through the solid rock salt, leaving substantial pillars standing to support the roof. Because halite is the product itself rather than a host rock carrying some minor constituent, the concept of ore grade as normally understood — a percentage of wanted material in unwanted host — barely applies. A good rock salt mine is extracting material that is already close to pure sodium chloride. What matters instead is the thickness and lateral continuity of the bed, the depth of cover, and the absence of insoluble impurities such as anhydrite or clay that would require separation downstream.
Where deposits are accessible from surface in arid environments, open excavation or solar evaporation ponds are preferred. Solar salt operations flood shallow basins with seawater or natural brine, allow evaporation over months, and harvest the crystallised salt mechanically. The capital cost of the solar resource — land and ponds — is high, but the energy cost is essentially zero, which makes this route competitive for bulk, lower-purity salt. Waste movement in the traditional mining sense is minimal: the salt is the landscape being worked, not something extracted from it.
The third route is solution mining, also called brine production. Fresh water is injected through a borehole into an underground halite deposit, dissolves the salt, and the resulting saturated brine is pumped back to surface. The brine may be sold directly to chemical plants — chlor-alkali producers in particular are often co-located with or piped from brine fields — or evaporated to recover dry salt. Solution mining leaves a void underground, and the geometry of that void requires careful management to prevent surface subsidence, which is the sinking of ground above the worked-out cavern. For chemical-grade applications demanding high purity, solution mining followed by vacuum evaporation is the dominant route because it allows impurities to be removed before crystallisation.
What pulls on it
The tables on this page show salt's end markets, and the pattern they reveal is one that surprises most readers encountering it for the first time: the food industry, which most people associate instinctively with salt, accounts for a relatively small share of total consumption. The dominant use globally is chemical feedstock, specifically the production of chlorine and sodium hydroxide through the electrolysis of brine, a process known as chlor-alkali. These two co-produced chemicals are foundational to an enormous range of industrial processes: PVC and other chlorinated plastics, water treatment, paper bleaching, aluminium production, soap manufacture and the synthesis of a large proportion of pharmaceutical intermediates all depend on one or both of them. Demand for salt in this channel therefore moves with the fortunes of the broader chemical industry rather than with population or food trends.
The second large pull on salt is road de-icing, a use that is almost entirely a function of winter severity and road network density in cold-climate countries. Because snowfall is variable from year to year, de-icing demand fluctuates considerably, and salt producers in North America and northern Europe plan and hold inventory accordingly. This is a price-sensitive, logistics-intensive market where transport cost often exceeds the cost of the salt itself, which is why production tends to cluster close to consuming regions rather than following the lowest-cost deposit.
An emerging and genuinely new demand signal comes from sodium-ion battery technology, where sodium chloride figures as a source of the sodium used in cathode materials and electrolytes. The material intensity figures shown on this page indicate the quantity of salt required per unit of battery capacity in this application. Whether this channel grows to significance in the overall salt balance depends on how widely sodium-ion technology is adopted relative to lithium-ion chemistry in energy storage. At present it is a small fraction of total demand, but it represents a qualitatively different kind of customer — one whose requirements for purity and traceability differ substantially from those of a highway authority buying bulk rock salt.
Turning ore into product Niveau 3
The processing route for salt depends almost entirely on the end use and the grade demanded by the customer. Rock salt mined underground typically requires only crushing and screening: the halite is already the product, and the processing objective is to achieve a consistent particle size rather than to separate a wanted mineral from gangue (the unwanted material surrounding it in conventional ore). Insoluble impurities present in the raw rock salt — clay partings, anhydrite bands — may be removed by wet washing, but for road de-icing, which accepts lower purity, the material may go to market with minimal treatment. The price differential between rock salt and vacuum-evaporated salt, visible in the unit value data, reflects this difference in processing intensity rather than any fundamental scarcity of the underlying resource.
Solar salt harvested from evaporation ponds carries impurities picked up during crystallisation — residual sulfates, magnesium and calcium salts, biological material — and typically undergoes washing with saturated brine solution. Washing with saturated brine rather than fresh water is essential: fresh water would simply dissolve the product. The washed salt is then dried and screened. For food or pharmaceutical use, further purification by vacuum pan evaporation is standard, a process in which brine is boiled under reduced pressure to force rapid, controlled crystallisation of high-purity sodium chloride while impurities remain in solution and are drawn off. The energy cost of vacuum evaporation is substantial and is the main reason evaporated salt commands a considerably higher unit value than rock or solar salt.
Brine sold directly to chlor-alkali plants undergoes purification before electrolysis. The electrolytic cells that split brine into chlorine gas, hydrogen gas and sodium hydroxide (caustic soda) are sensitive to specific ionic contaminants — calcium, magnesium, sulfate — which would degrade cell membranes or electrodes. Brine purification therefore involves precipitation of these impurities using soda ash and lime, followed by filtration, and in membrane-cell technology a further polishing stage through ion-exchange resins. The losses in this sequence are small relative to the bulk throughput, but the quality control requirements are tight, and the cost of maintaining purification plant is a meaningful fraction of chlor-alkali operating costs. Salt sold into this market is effectively a feedstock specification as much as a commodity.
Substitution and recycling Niveau 3
For its dominant industrial application — chlor-alkali feedstock — salt has no practical substitute. The electrolytic route from brine is how essentially all commodity chlorine and sodium hydroxide is made, and no alternative starting material approaches halite in cost, abundance or established infrastructure. If a chlor-alkali plant cannot source adequate brine, it cannot operate; there is no workaround. This makes the chemical segment of salt demand essentially price-inelastic over any normal operating horizon, though a prolonged shutdown of chlor-alkali capacity for other reasons would obviously reduce brine consumption.
For road de-icing, alternatives exist and are used in specific circumstances. Calcium chloride and magnesium chloride both depress the freezing point of water at lower temperatures than sodium chloride and are preferred where temperatures fall well below the effective range of rock salt. Sand and grit provide traction without melting ice and are used where environmental runoff of chlorides into watercourses is a concern. However, neither grit nor the alternative chloride salts have displaced rock salt at volume in any major market, primarily because sodium chloride remains considerably cheaper per tonne applied and the logistics infrastructure — mine, road, spreading equipment — is already in place. The constraint on substitution is economic rather than technical.
Recycling of salt does not occur in the way recycling is understood for metals. Salt that has been consumed in chemical synthesis becomes other compounds; it cannot economically be returned to halite. De-icing salt disperses into the environment. In chlor-alkali plants, spent brine is typically re-saturated and recirculated within the plant, which is a form of process efficiency rather than recycling in the supply-chain sense. The net result is that essentially all salt entering commerce must be freshly produced — there is no secondary supply stream of any significance. This is not an accident of infrastructure or economics but a consequence of what salt becomes when it is used.
D'où cela vient dans la roche
Tous les minéraux de minerai →Ce sont les minéraux qui portent réellement salt. Un gisement n'est un corps minéralisé que si l'un d'eux est suffisamment concentré pour rentabiliser son extraction.
Qui le produit
Voir sur une carte →Mine production
Mine productionthousand metric tons 2025 (estimé) Total mondial 270,000 thousand metric tons
USGS Mineral Commodity Summaries 2026 · Gross weight of all grades including rock salt, solar salt and brine. · source ↗
Faire défiler le tableau latéralement pour afficher les colonnes restantes.
| Pays | Production | Part mondiale |
|---|---|---|
| China | 56,000 | 20.7% |
| United States | 40,000 | 14.8% |
| India | 30,000 | 11.1% |
| Other countries | 28,000 | 10.4% |
| Germany | 15,000 | 5.6% |
| Canada | 13,000 | 4.8% |
| Australia | 12,000 | 4.4% |
| Chile | 9,000 | 3.3% |
| Turkey | 8,300 | 3.1% |
| Mexico | 7,000 | 2.6% |
| Russia | 7,000 | 2.6% |
| Brazil | 6,600 | 2.4% |
| Netherlands | 5,400 | 2.0% |
| France | 4,500 | 1.7% |
| Iran | 4,200 | 1.6% |
| Poland | 4,100 | 1.5% |
| Spain | 4,000 | 1.5% |
| Pakistan | 3,100 | 1.1% |
| Bulgaria | 2,700 | 1.0% |
| United Kingdom | 2,600 | 1.0% |
| Saudi Arabia | 2,400 | 0.9% |
| Egypt | 2,300 | 0.9% |
| Belarus | 2,000 | 0.7% |
| Italy | 1,900 | 0.7% |
| Total mondial | 270,000 | 100% |
« Withheld » signifie que l'USGS a supprimé le chiffre afin de ne pas divulguer les données d'une entreprise individuelle — cela ne signifie pas zéro. La somme des lignes par pays ne correspond pas toujours au total mondial, car la source arrondit chaque chiffre de manière indépendante et ne détaille pas toujours une ligne « autres pays ».
Prix
average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Vacuum and open pan salt
Moyenne annuelledollars per metric ton
Base: average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Vacuum and open pan salt. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Solar salt
Moyenne annuelledollars per metric ton
Base: average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Solar salt. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Salt in brine
Moyenne annuelledollars per metric ton
Base: average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Salt in brine. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Rock salt
Moyenne annuelledollars per metric ton
Base: average unit value of bulk, pellets and packaged salt, free on board (f.o.b.) mine and plant, dollars per metric ton: Rock salt. Moyennes annuelles telles que publiées dans USGS Mineral Commodity Summaries 2026 · source ↗. Il s'agit de moyennes annuelles de référence, et non de cotations de marché en temps réel.
À quoi cela sert
Tous les marchés finaux →| Marché final | Ce qu'il fait là-bas | Importance |
|---|---|---|
| Grid Storage | Sodium-ion cathode and electrolyte | Important |
Quelle quantité en nécessite une technologie
| Technologie | Quantité | Coté | Base |
|---|---|---|---|
| Sodium-Ion Battery | 30.00–60.00 kg | per 75 kWh equivalent | Sodium source |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. Appliquer ces chiffres à n'importe quelle échelle dans le calculateur de matériaux →