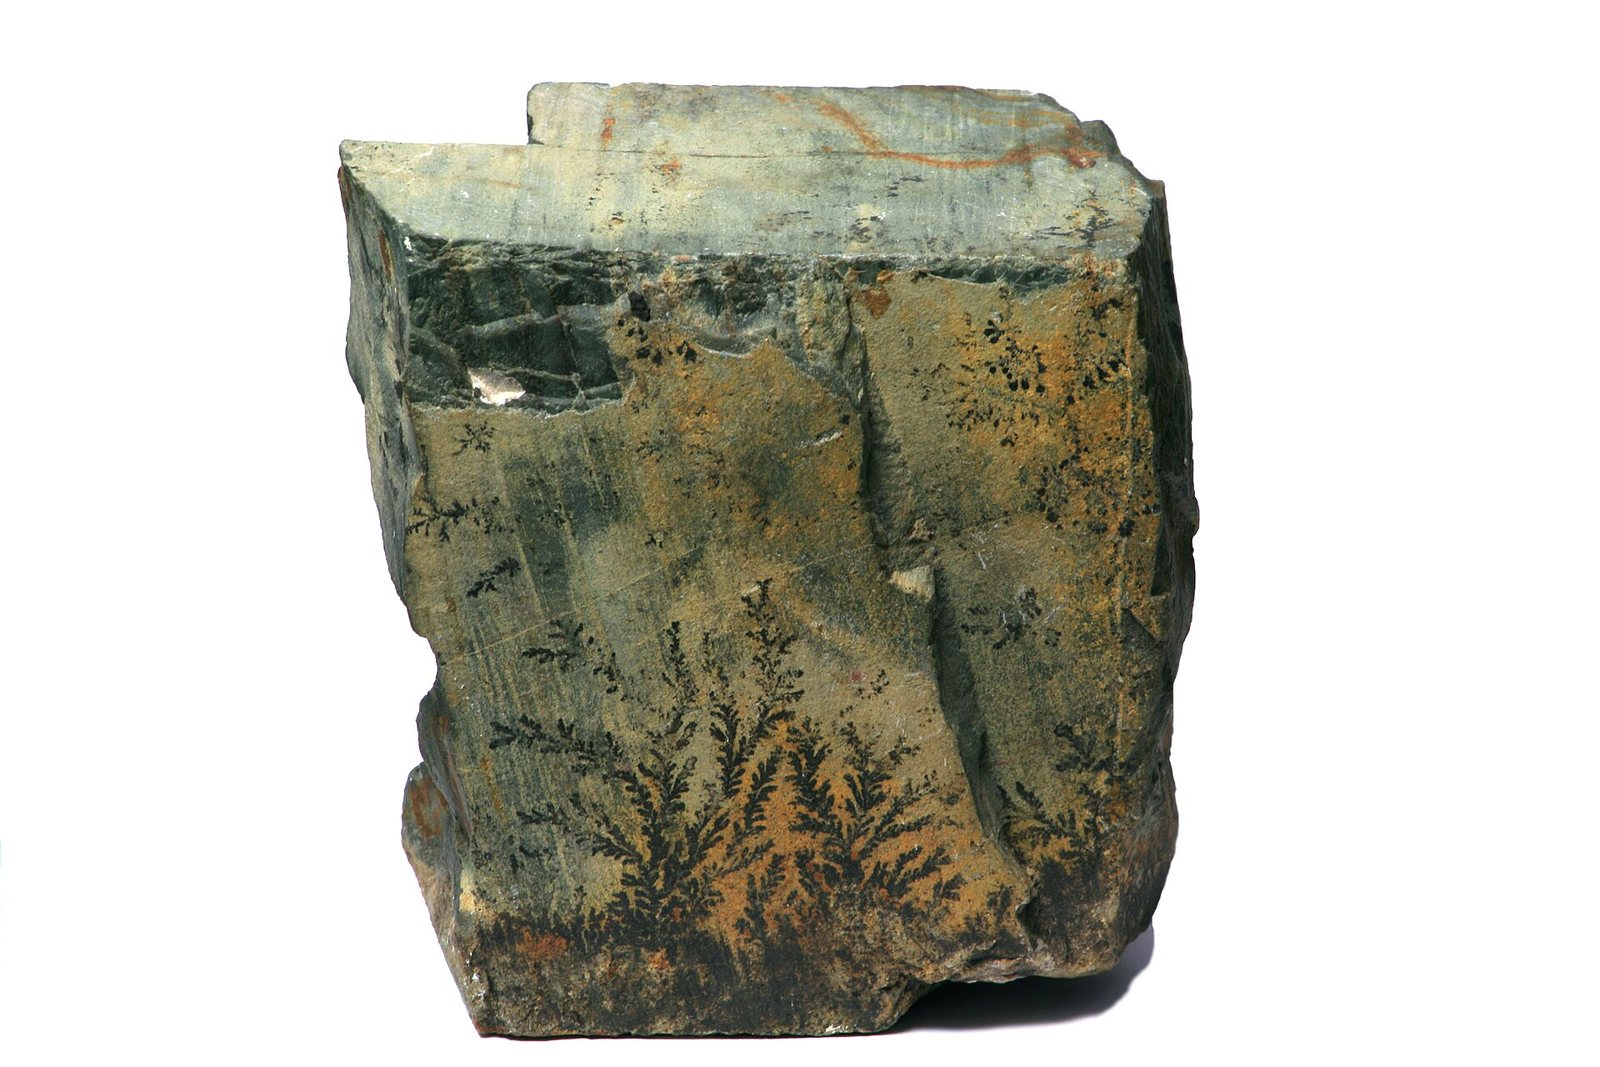
これは何か
A brittle grey metal that steel cannot be made without, and that is now being used to stretch scarce nickel and cobalt further in batteries.
なぜ重要なのか
Around 90% of manganese goes into steel — it removes sulfur and oxygen and adds toughness. There is no substitute in steelmaking at any price.
Where it is in the Earth
Manganese is the twelfth most abundant element in the Earth's crust, but that abundance is deceptive: the metal is spread so thinly through common rocks that only a handful of geological processes have ever concentrated it enough to be worth mining. The most economically important deposits are sedimentary manganese deposits, formed in ancient shallow seas where dissolved manganese, carried by river water or hydrothermal vents, precipitated out of the water column as oxygen levels changed. Over millions of years these chemical sediments built up into layered beds interbedded with other seafloor material. The great deposits of South Africa's Kalahari basin, Gabon's Moanda plateau, and Australia's Groote Eylandt island all belong to this family, and they account for the overwhelming share of what the world mines today.
A second important geological setting is the banded iron formation, a very ancient rock type in which iron and silica-rich layers alternate in fine bands. In some banded iron formations, later weathering and groundwater movement have leached away much of the iron and silica while leaving manganese behind in enriched concentrations near the surface. The Carajás district of Brazil, operated by Vale, is the most prominent example. A third, much smaller source is deep-sea manganese nodules — potato-sized concretions that grow extremely slowly on the ocean floor, incorporating manganese, nickel, copper and cobalt from seawater. No commercial deep-sea mining operation exists yet, so these remain a geological curiosity with uncertain future relevance.
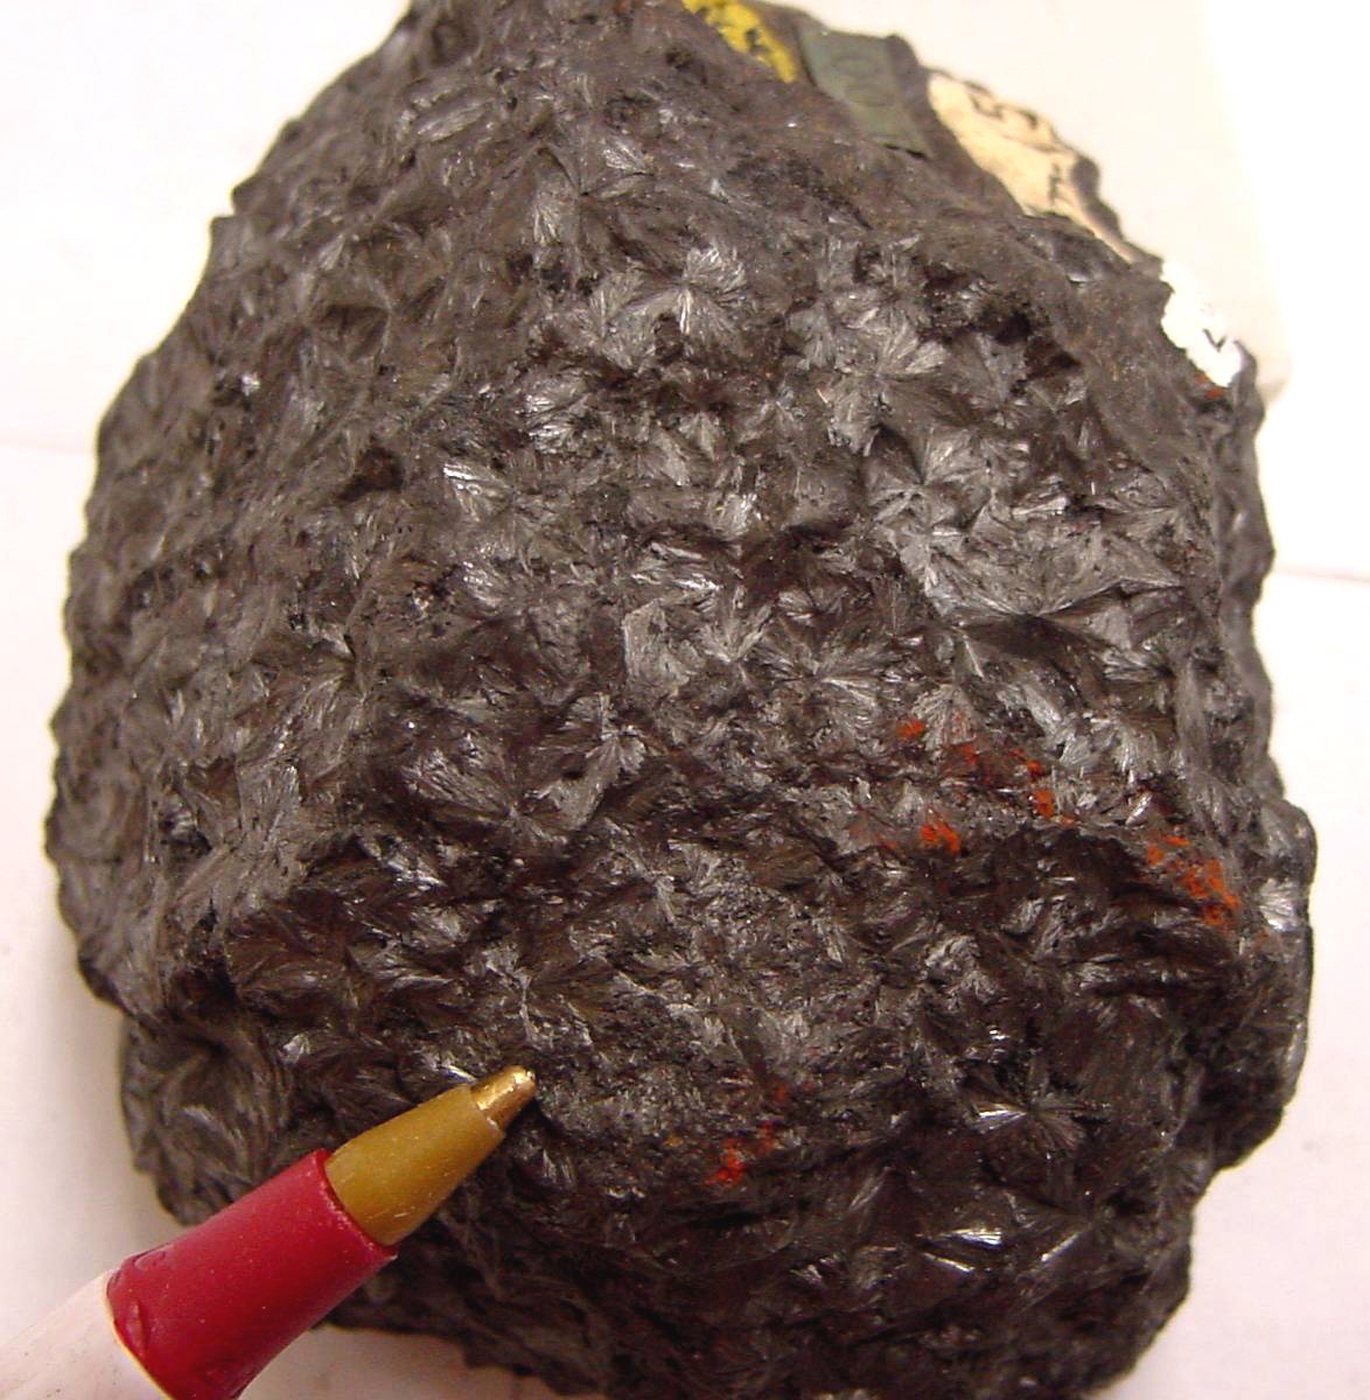
The dominant ore mineral is pyrolusite, a manganese dioxide (MnO₂) mineral with a distinctive black to steel-grey colour. Other oxide minerals — romanèchite, manganite, hausmannite — appear in the same deposits, often alongside one another. Because the best sedimentary deposits formed under specific ocean-chemistry conditions that existed during a relatively narrow window of geological time, the world's high-grade reserves are concentrated in a small number of countries, a pattern that has direct consequences for how the supply chain works.
Getting it out
Almost all primary manganese is extracted by open-pit mining, a method in which overlying rock and soil — called overburden — is stripped away in benches to expose the ore beneath. The geometry suits manganese geology well: sedimentary manganese deposits tend to be broad, relatively flat-lying bodies close to the surface, meaning the ratio of overburden to ore is manageable and the ore can be reached with large excavators and haul trucks rather than the more expensive infrastructure of an underground mine. Groote Eylandt and Moanda are both classic open-pit operations of this kind. The Carajás deposit in Brazil, formed by weathering of banded iron formation, is likewise mined as a large open pit.
The ore grade — the concentration of manganese in the rock being dug — matters enormously to the economics. Grade is typically expressed as a percentage of manganese content by weight. A higher grade means less rock must be moved and processed to produce a given amount of saleable manganese, so it directly affects the cost of every tonne shipped. The USGS, the United States Geological Survey, reports world production figures on a manganese-content basis rather than on a gross ore basis, which is worth remembering when comparing figures across sources, since a low-grade operation produces far more gross ore tonnes for the same content figure. The practical consequence is that mines with naturally higher grades, like those in Gabon and South Africa's Kalahari, can compete on cost even when located far from their customers.
Because the deposits are sedimentary and broadly distributed, the mines are large in areal extent but relatively shallow. This means the volume of waste rock moved is lower than in many hard-rock metal mines, though the softer, sometimes clay-rich overburden at places like Groote Eylandt creates its own handling challenges, particularly in wet seasons. There is no significant manganese production from brine or in-situ leaching methods, which dissolve metals underground before pumping the resulting solution to surface — the chemistry of manganese mineralisation does not lend itself to those approaches.
What pulls on it
Steel is where manganese demand begins and ends for most of the metal that is mined. Roughly 90 percent of manganese consumption goes into steel in one form or another, added as ferromanganese or silicomanganese alloys during steelmaking. The function is partly chemical and partly metallurgical: manganese combines with sulfur in the molten steel, preventing the formation of iron sulfide, which would make the steel brittle along its grain boundaries. It also scavenges dissolved oxygen. Beyond those cleaning functions, manganese adds hardness and toughness to the finished steel, and high-manganese steels are used in applications that face severe abrasion, such as rail crossings, rock-crushing equipment and ground-engaging tools for mining and construction. Because every tonne of steel contains some manganese, demand broadly tracks global steel production, which in turn tracks construction activity and industrial output, particularly in the economies that build the most infrastructure.
The second and faster-growing stream of demand is in batteries. Manganese appears in the cathodes of NMC batteries (lithium nickel manganese cobalt oxide), which are widely used in electric vehicles, and its role is partly to dilute the more expensive and less abundant nickel and cobalt while maintaining acceptable energy density and cycle life. A 75 kWh NMC battery pack contains between 5.0 and 9.0 kg of manganese, according to the data available. More recently, LMFP cathodes (lithium manganese iron phosphate) have attracted attention as a way to use considerably more manganese and less of the metals with more constrained supply. Sodium-ion batteries, which use a layered-oxide cathode that can contain substantial manganese, are estimated to require between 10.0 and 30.0 kg per 75 kWh-equivalent depending on the specific chemistry — a meaningfully higher intensity than current lithium-ion designs. If sodium-ion technology scales significantly, manganese demand from batteries could grow faster than most current expectations assume.
For demand to shift sharply downward from its steel anchor, either global steel production would need to fall or a substitute for manganese in steelmaking would need to emerge. Neither is imminent: steel output has grown steadily with urbanisation and industrialisation across the developing world, and the chemistry of steel desulfurisation and deoxidation genuinely has no cost-competitive alternative. The battery sector, by contrast, is still settling on its preferred chemistries, and a shift toward higher-manganese or manganese-dominant cathodes would represent a meaningful upward demand signal, while a shift toward lithium iron phosphate without manganese would leave battery demand relatively flat.
岩石中の産出箇所
全鉱石鉱物 →実際に以下を担う鉱物 manganese. 鉱床が鉱体となるのは、採掘コストを回収できるほど十分な濃度で鉱石が濃集している場合に限られる。
生産者
地図で見る →Mine production
Mine productionthousand metric tons 2025 (推定値) 世界合計 20,000 thousand metric tons
USGS Mineral Commodity Summaries 2026 · USGS world figures are manganese CONTENT of ore, not gross ore tonnes. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| South Africa | 7,600 | 38.0% |
| Gabon | 5,000 | 25.0% |
| Ghana | 2,000 | 10.0% |
| Australia | 1,600 | 8.0% |
| Other countries | 1,300 | 6.5% |
| Brazil | 800.0 | 4.0% |
| India | 790.0 | 4.0% |
| China | 700.0 | 3.5% |
| Côte d’Ivoire | 350.0 | 1.8% |
| United States | Zero | — |
| 世界合計 | 20,000 | 100% |
「非開示」とは、個別企業のデータが特定されないようUSGSが数値を公表しなかったことを意味し、ゼロを意味するものではありません。出典が各数値を独立して丸め処理しており、「その他の国」の内訳を常に示しているわけではないため、各国の数値の合計が世界合計と一致しないことがあります。
埋蔵量の保有者
Reserves
Reservesthousand metric tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| Australia | 580,000 | 34.1% |
| South Africa | 550,000 | 32.4% |
| Brazil | 300,000 | 17.6% |
| China | 260,000 | 15.3% |
| Gabon | 61,000 | 3.6% |
| India | 34,000 | 2.0% |
| Ghana | 13,000 | 0.8% |
| United States | Zero | — |
| Côte d’Ivoire | Not applicable | — |
| Other countries | Small | — |
| 世界合計 | 1,700,000 | 100% |
価格
average, manganese content, cost, insurance, and freight, China, dollars per metric ton unit
年間平均dollars per metric ton
基準: average, manganese content, cost, insurance, and freight, China, dollars per metric ton unit. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
産出鉱山
全鉱山 →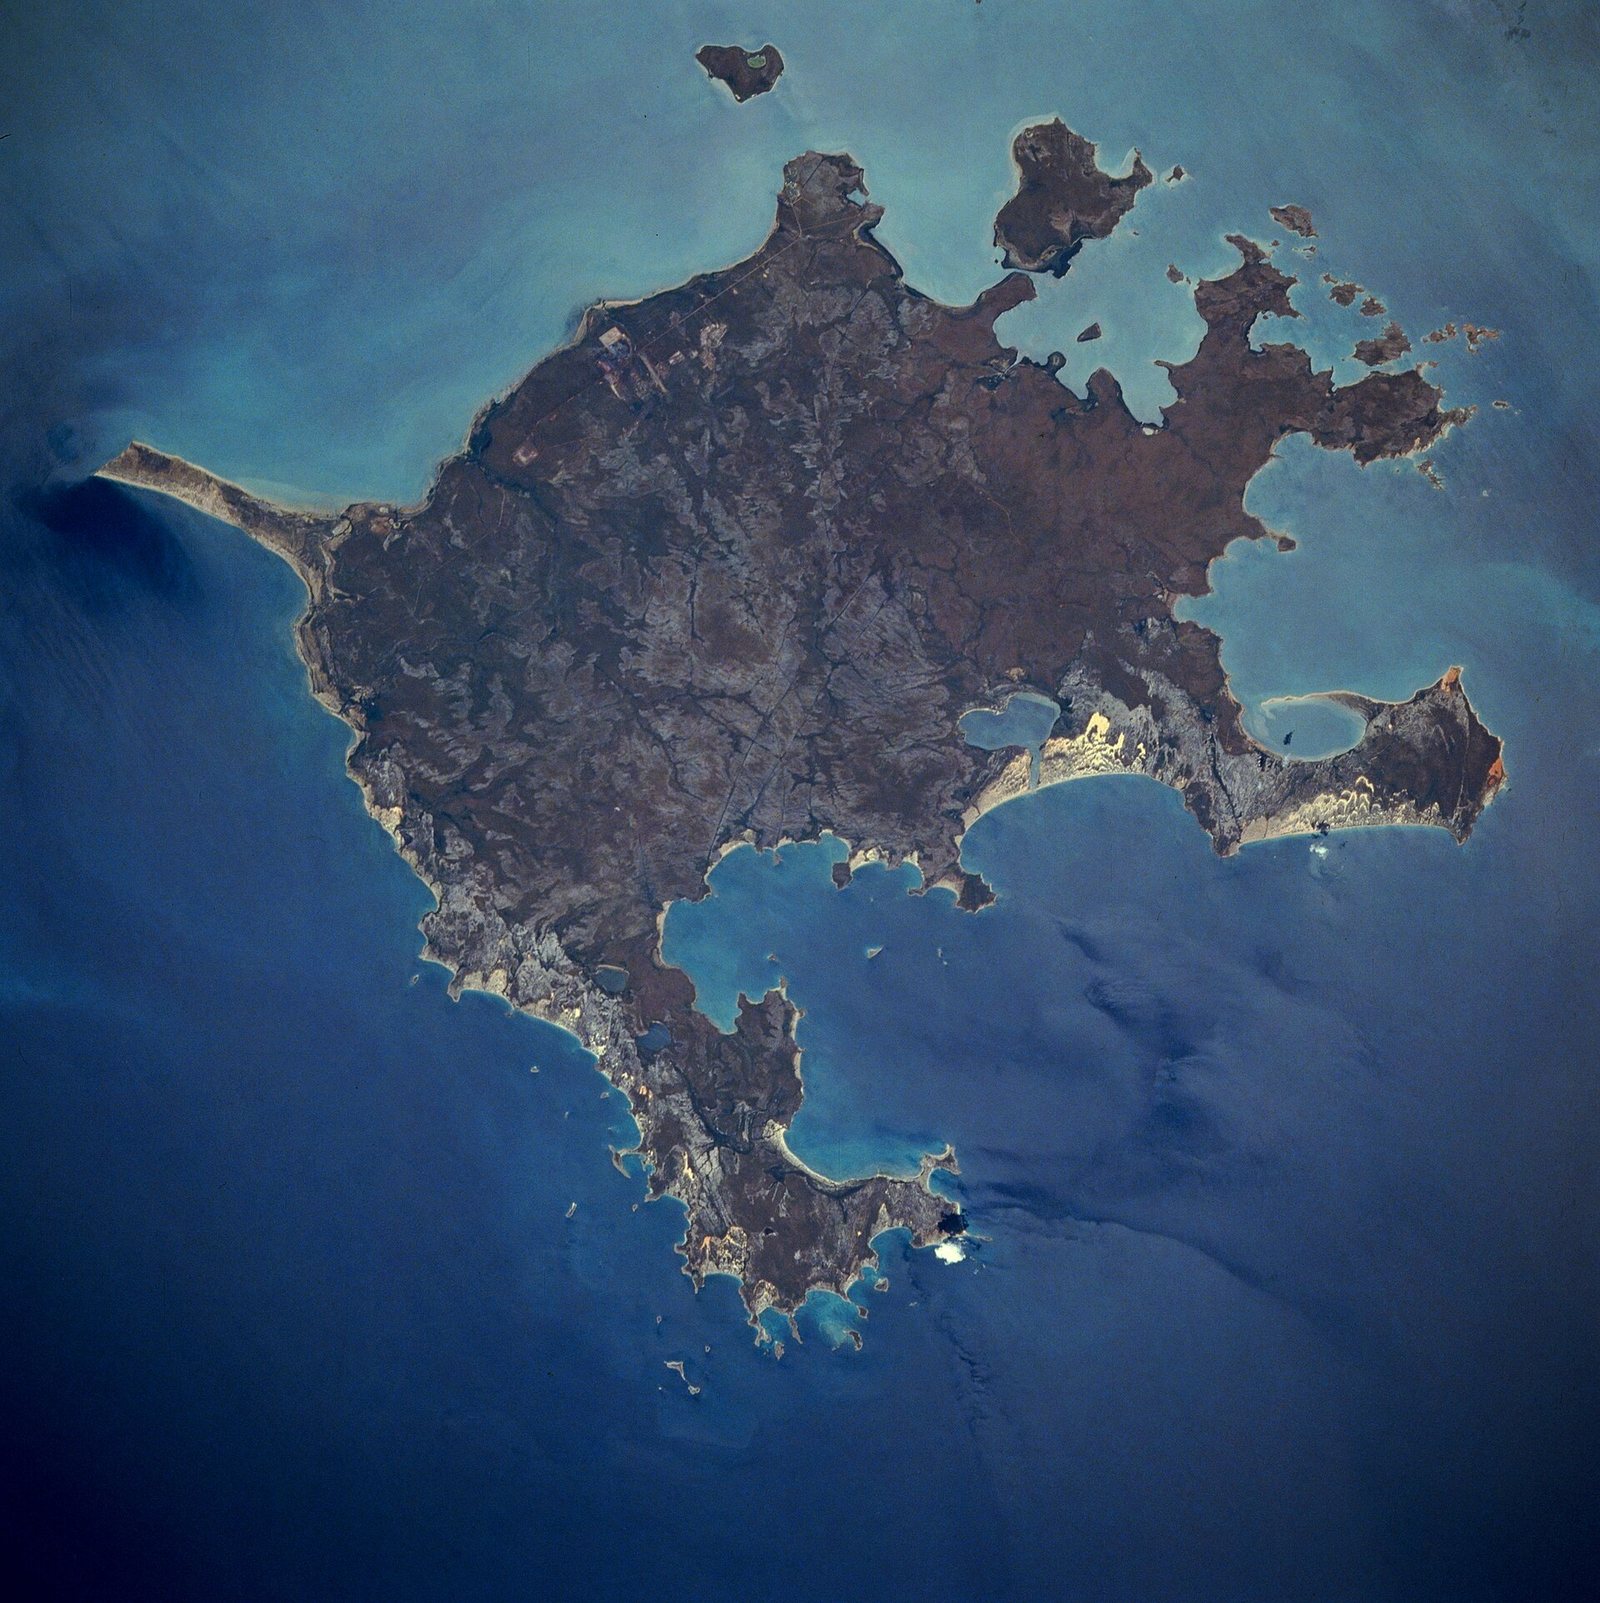
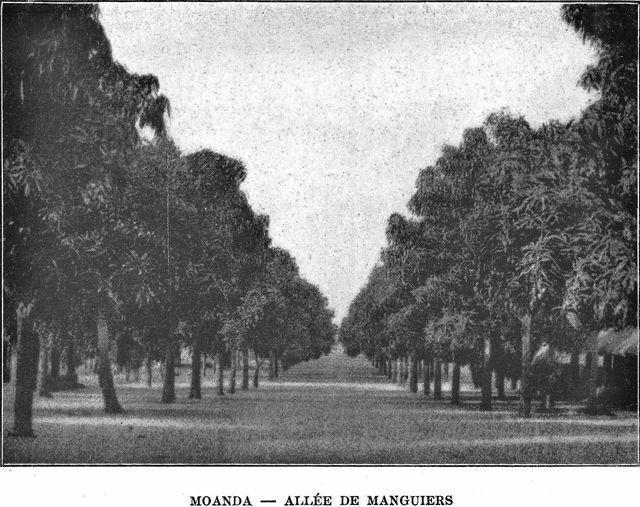
Moanda
One of the world's largest manganese deposits.
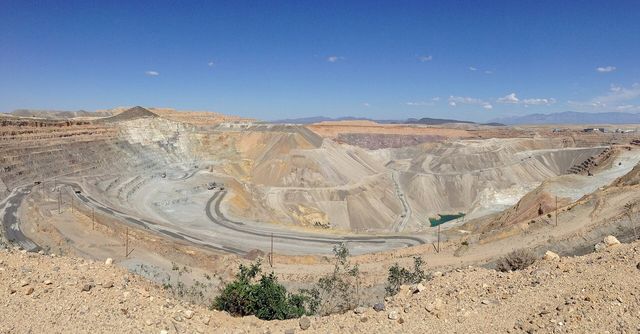
Carajás
The highest-grade large iron-ore operation in the world.
用途
全エンドマーケット →| 最終市場 | そこでの機能 | 重要度 |
|---|---|---|
| Construction & Steel | In every tonne of steel | 定義 |
| Electric Vehicles | Cathode component in NMC and LMFP | 重要 |
| Grid Storage | Manganese-based cathodes | 重要 |
技術が必要とする量
| 技術 | 数量 | 建値 | 基準 |
|---|---|---|---|
| NMC Lithium-Ion Battery | 5.00–9.00 kg | per 75 kWh pack | Contained manganese |
| Sodium-Ion Battery | 10.00–30.00 kg | per 75 kWh equivalent | Layered-oxide cathode variants |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. 素材計算機で任意の規模に換算して実行 →
輸出規制
| 国 | 支配 | 適用対象 |
|---|---|---|
| Namibia | Export ban | Ores and concentrates of cobalt, graphite, lithium, manganese, and rare earths (2023). ↗ |
| Vietnam | Export ban | Raw materials of iron, lead-zinc, chromite, manganese, apatite, and rare earths and deeply processed titanium (2012). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.
越境地点をたどる
すべての輸送経路 →この素材の特定の貨物が実際にたどる経路——すべての国、すべての管理者、各工程で残されるもの。
Pilbara iron ore to Chinese steel The largest material flow on Earth: dig it, crush it, screen it, and put it on a boat.