これは何か
Mostly methane, the lightest hydrocarbon, and the source of nearly all the hydrogen used by industry today.
なぜ重要なのか
Gas makes the ammonia that makes fertiliser, the hydrogen that refines fuel, and the helium that cools MRI magnets. Its role as chemical feedstock is as important as its role as fuel.
Where it is in the Earth
Natural gas is not a mineral in the conventional sense — it is not a solid crystalline compound found in a specific layer of rock. It is instead a mixture of hydrocarbons, overwhelmingly methane, that formed over geological timescales from organic matter buried under heat and pressure. When ancient marine organisms — algae, zooplankton, the fine organic rain of shallow seas — were buried quickly enough to be preserved rather than oxidised, they were cooked slowly by the Earth's internal heat. At relatively modest temperatures this organic material yields oil; at greater depth and higher temperatures, where oil itself begins to break down, it yields the shorter hydrocarbon chains we call gas. The depth at which this happens, known as the gas window, varies with local geology but is generally deeper than the oil window above it.
Gas, once generated, does not stay where it forms. Being buoyant relative to the surrounding brine-saturated rock, it migrates upward through permeable formations until something stops it. That something is a trap: a geometrical arrangement of rock layers that creates a sealed pocket. The most familiar kind is an anticline, a dome-shaped fold where permeable reservoir rock — typically sandstone or limestone — is capped by impermeable shale or evaporite. Gas accumulates at the top of the dome. Other traps are formed by faults, pinching-out sediment layers, or ancient salt domes that punch upward through the sedimentary column. The world's largest gas accumulations are in the great sedimentary basins that line passive continental margins and interior rift systems, wherever burial was deep and rapid and where intact cap rocks have survived hundreds of millions of years of tectonism.
Unconventional gas — the shale gas that transformed North American production in the twenty-first century — breaks this picture somewhat. In shale formations, gas never migrated at all; it remains locked inside the fine-grained source rock itself, held partly in tiny pores and partly adsorbed onto organic carbon. These reservoirs are geographically enormous precisely because they have not concentrated into discrete traps; they underlie whole basins rather than sitting in isolated pockets. The trade-off is that the rock's permeability is extremely low, which is why getting the gas out requires a different method entirely.
Getting it out
Natural gas does not require mining in the sense that coal or metal ores do. It is a fluid, and the method of recovery is drilling: a steel-cased borehole is driven down to the reservoir rock, and once a pressure pathway is opened, the gas flows upward under its own pressure or is lifted by compressors. In a conventional reservoir — the anticline or fault-trap type — a single vertical well can drain a large connected volume of porous rock. The well produces a mixture of gas, water, and often liquid hydrocarbons; these are separated at the surface before the gas enters a pipeline. The concept of grade, so central to solid minerals, translates here into reservoir quality: porosity (the fraction of the rock that is empty space) and permeability (how easily fluid moves through it). A high-quality conventional reservoir can deliver large volumes through relatively few wells.
Unconventional shale gas requires horizontal drilling and hydraulic fracturing, commonly called fracking. The well is drilled vertically to the target depth and then turned to run horizontally through the shale for a kilometre or more. To overcome the rock's near-zero natural permeability, operators pump a high-pressure mixture of water, sand and chemical additives down the well to crack the rock and prop those cracks open with sand grains. The gas then flows through the induced fracture network to the well. Because the drainage radius of any single fracture system is limited, many wells must be drilled across a shale play, often in closely spaced grids. The concept of waste rock that defines metal mining does not apply directly here, but the scale of surface infrastructure — well pads, water handling, pipeline gathering — is substantial relative to the gas produced from each well. Shale wells also decline steeply in their first year or two, requiring constant new drilling to maintain production.
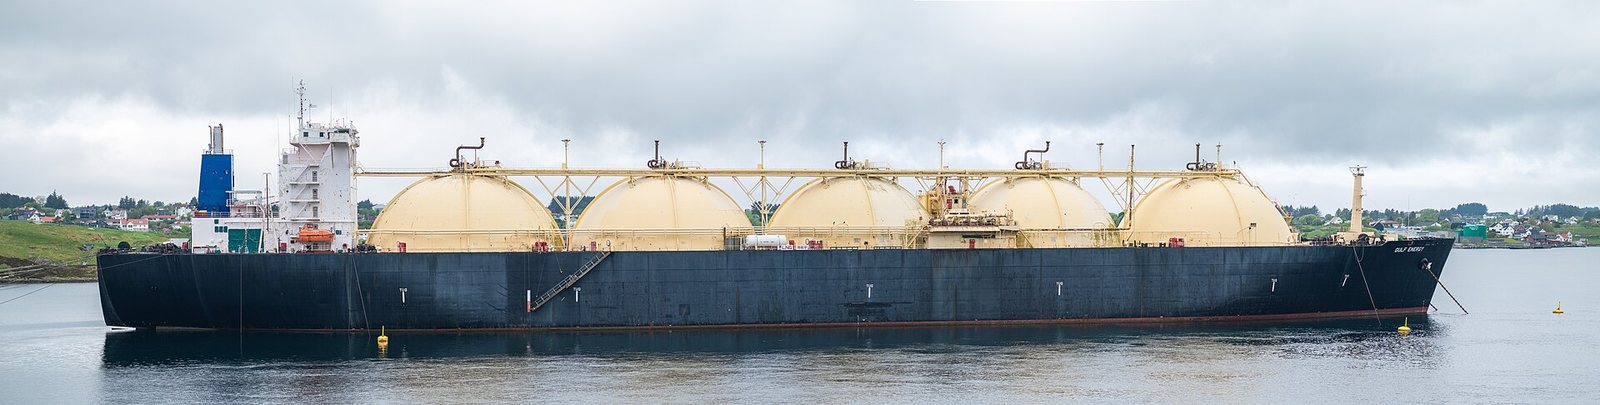
Liquefied natural gas, or LNG, is not a different geological product but a different way of transporting the same gas. When pipeline access is impractical — across oceans, for instance — gas is cooled to minus one hundred and sixty-two degrees Celsius, at which point it becomes a liquid occupying a fraction of its gaseous volume. It is then carried in insulated tankers and regasified at the destination. This step sits between production and end use, but it shapes the geography of supply profoundly: it allows gas fields far from consuming markets to reach them, breaking the constraint that once made gas essentially a regional commodity.
What pulls on it
Natural gas sits in two quite distinct roles that are worth separating clearly. As a fuel, it is burned in power stations, industrial furnaces and domestic boilers to produce heat and electricity. As a feedstock, it is chemically converted — most importantly through steam methane reforming, a process that reacts methane with steam to produce hydrogen — and that hydrogen is then used to make ammonia, to upgrade crude oil in refineries, and in a growing range of chemical processes. These two roles respond to different pressures and carry different risks. Fuel demand is sensitive to the price of competing energy sources and to efficiency improvements; feedstock demand is tied instead to the volume of fertiliser, refined fuel and chemicals that the world requires.
Ammonia production, the foundation of most synthetic fertiliser, accounts for a very large share of global gas consumption in its feedstock role. Agricultural output at current scales is built on the assumption that nitrogen fertiliser is abundantly available, which means it is built on the assumption that gas is abundantly available. This linkage runs through the global food supply in ways that are not always visible: a sharp, sustained increase in gas prices ripples through to fertiliser costs, then to farm economics, then to food prices, as the 2021 to 2022 price spike illustrated plainly. Gas is also the dominant source of industrial hydrogen today, and hydrogen demand is expected to grow if decarbonisation efforts proceed — though that same decarbonisation agenda also motivates producing hydrogen by electrolysis from renewable electricity rather than from gas.
Power generation demand for gas is the portion most exposed to substitution by renewables and nuclear. In markets where wind and solar capacity is expanding, the fraction of electricity generation met by gas tends to decline over time, though gas often retains a role as a dispatchable backup for periods when renewable output is low. Industrial heat at very high temperatures is harder to electrify economically, which tends to make gas demand in heavy industry more persistent. Residential heating demand is sensitive both to efficiency measures in building stocks and to electrification through heat pumps. Overall, the fuel and feedstock roles pull on gas in different directions, and any assessment of future demand has to treat them separately.
価格
Natural gas, European price
年間平均US$ per million BTU
基準: IMF global price of natural gas — Russian border price in Germany / TTF. 以下に公表された年間平均値: FRED (IMF primary commodity prices) · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
用途
全エンドマーケット →| 最終市場 | そこでの機能 | 重要度 |
|---|---|---|
| Agriculture & Food | Hydrogen feedstock for ammonia | 定義 |
輸出規制
| 国 | 支配 | 適用対象 |
|---|---|---|
| Thailand | Export ban | Natural sand (2023). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.
越境地点をたどる
すべての輸送経路 →この素材の特定の貨物が実際にたどる経路——すべての国、すべての管理者、各工程で残されるもの。
Saudi Arab Light to petrol, almost anywhere The same commodity, a fraction of the effort — because of what the molecule is.