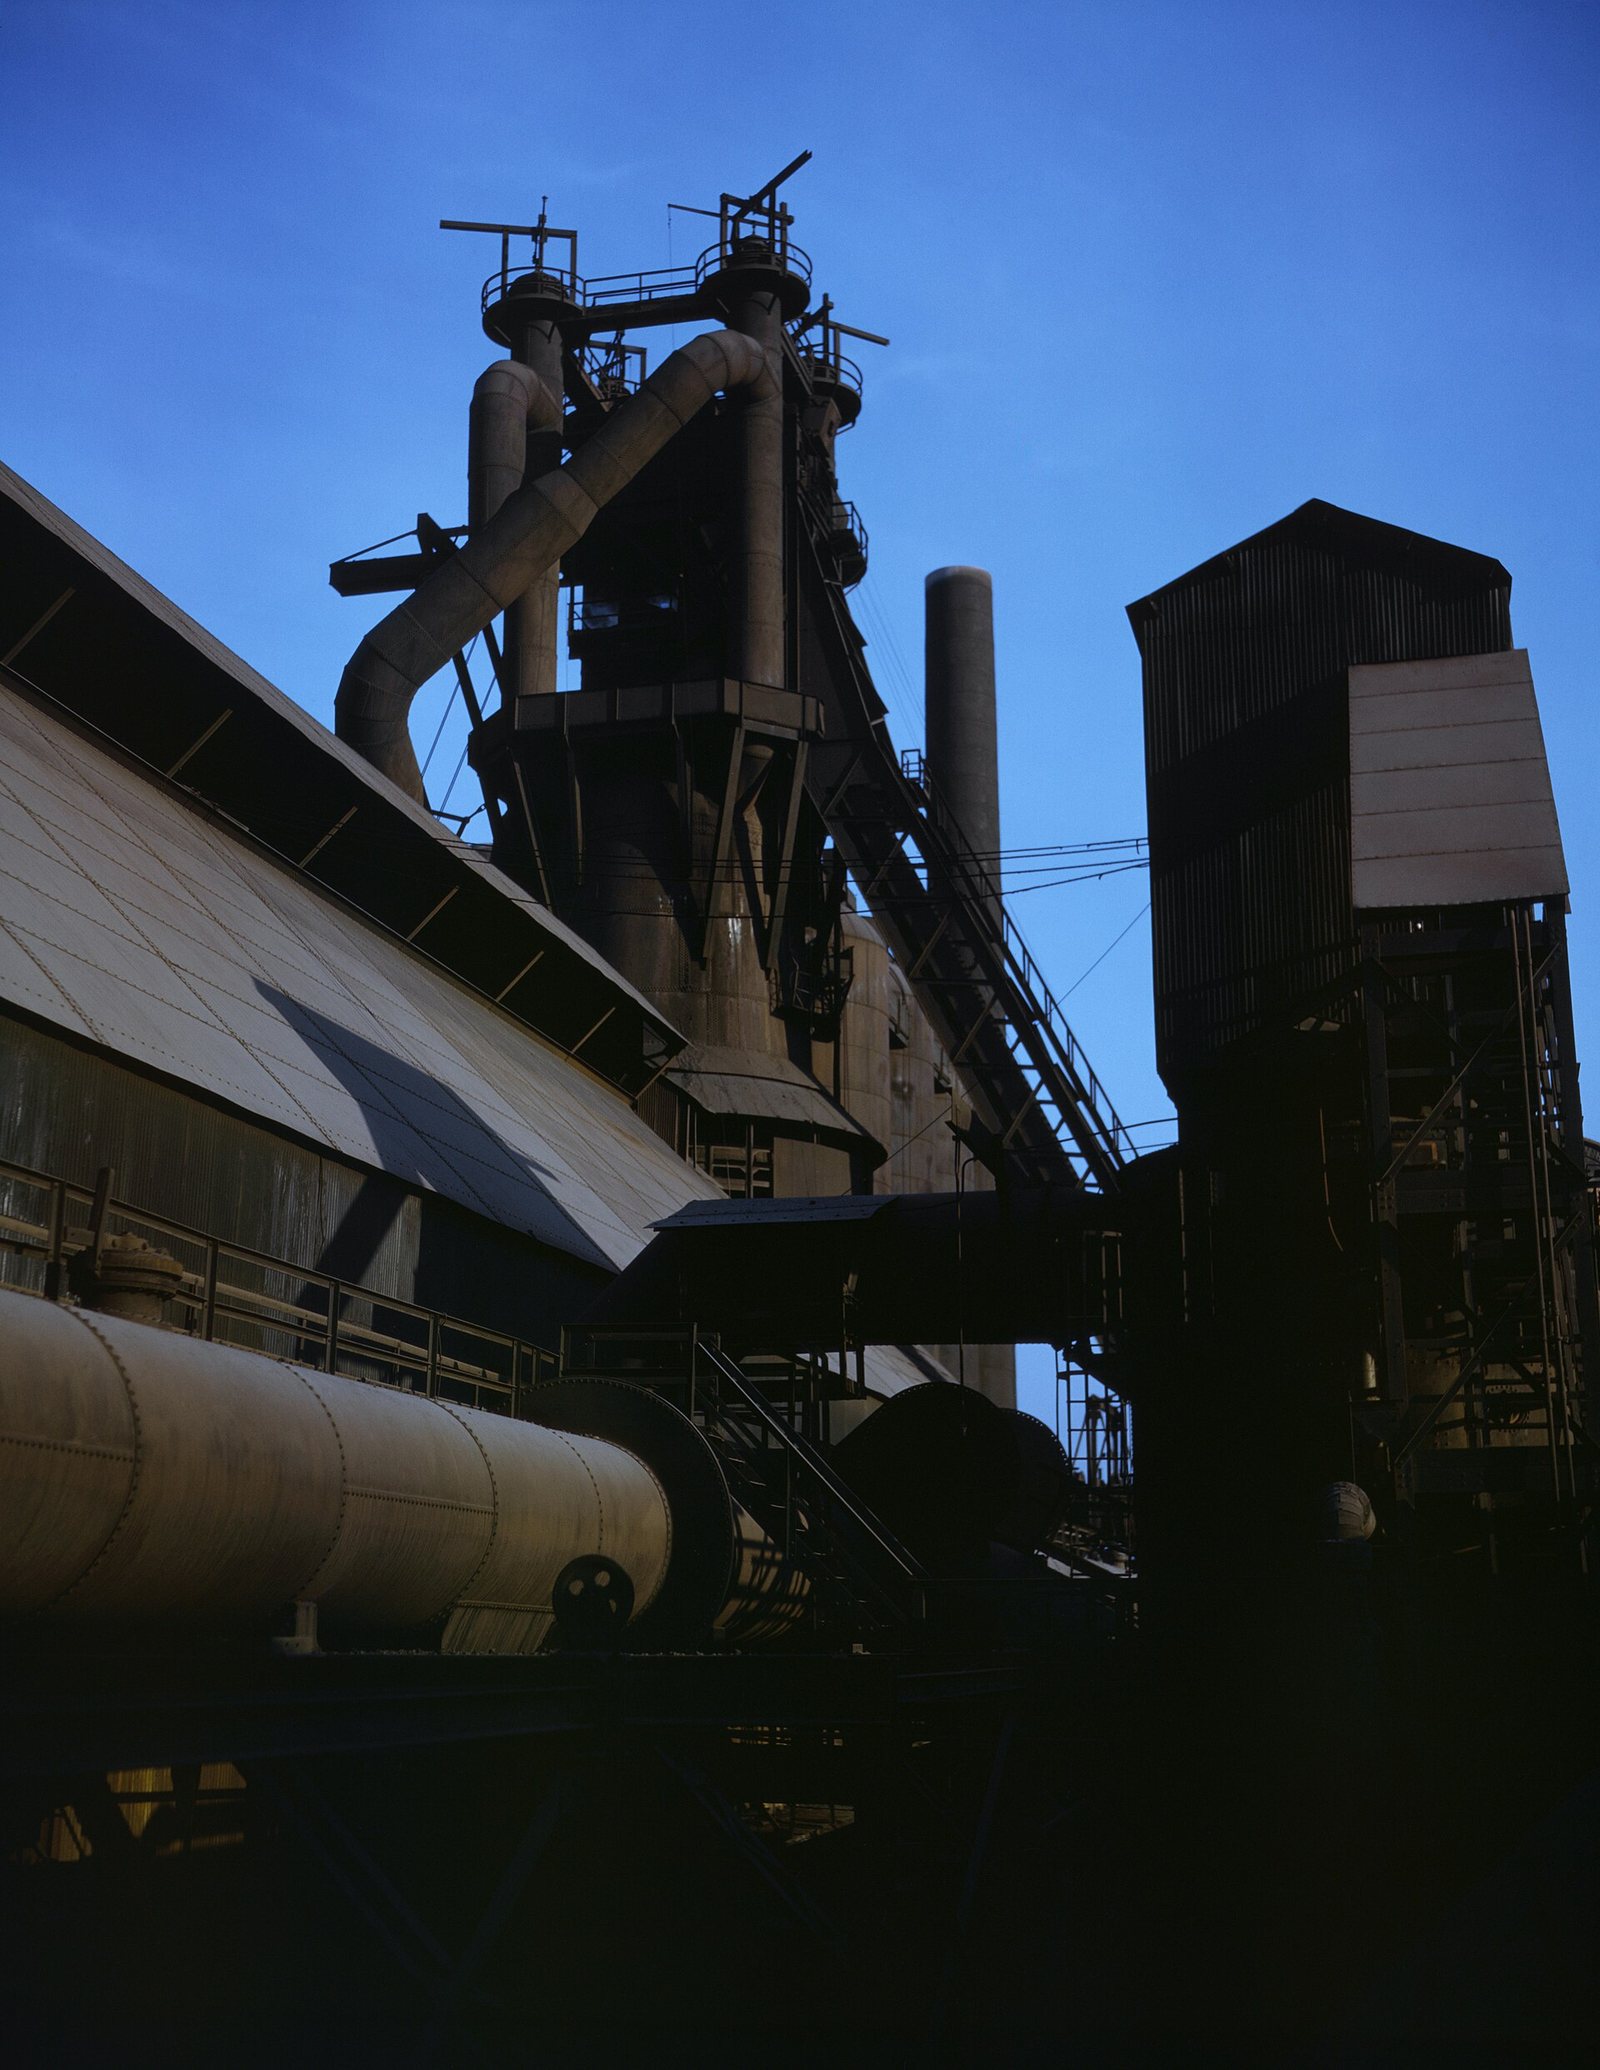
这是什么?
Iron with a little carbon in it, and the most-produced manufactured material on the planet.
为何重要?
Steelmaking is around seven to nine percent of global CO2 emissions, which is why hydrogen and electric-arc routes matter so much.
Where it is in the Earth
Iron is the fourth most abundant element in the Earth's crust, yet the ore bodies that feed steelmakers are not simply wherever iron happens to be. Concentration matters. The deposits that are actually mined formed under conditions that gathered iron into minerals rich enough to be worth extracting — conditions that were, in most cases, billions of years old before a single human set foot on the planet.
The dominant source of iron ore is a rock type called banded iron formation, or BIF. These are ancient sedimentary sequences, laid down mostly between about two and a half and one and a half billion years ago, in which thin alternating layers of iron-rich minerals and silica (essentially fine quartz) were deposited on the floors of shallow seas. The current explanation for why so much iron settled out at that particular moment in Earth's history is that the oceans were then nearly devoid of dissolved oxygen. Iron dissolved easily in those oxygen-poor waters, and when photosynthesising microbes began releasing oxygen, the iron was oxidised and precipitated in vast quantities. Later geological events — heat, pressure, the circulation of hot fluids through the rock — upgraded some of these formations by leaching out the silica and leaving behind concentrations of iron oxide minerals, chiefly haematite and magnetite. The richest deposits, sometimes called direct-shipping ore, carry enough iron that they can be sent to a steelmaker with minimal processing. The leaner BIF deposits require more work before they are useful.
The great ore provinces of Australia's Pilbara, Brazil's Iron Quadrangle and the Lake Superior region of North America are all ancient BIF sequences that have been preserved and, in places, naturally enriched. Younger iron deposits also exist — formed by magmatic processes, by sedimentary accumulation in more recent seas, or by weathering that concentrates iron near the surface — but BIF-hosted ore dominates global supply by a wide margin. The geography of production therefore reflects geology more than politics: the major exporters are those countries where these ancient formations happen to be large, near-surface and well-connected to ports.
Getting it out
Iron ore is mined almost entirely in open pits. The ore bodies are large, the rock is hard but not especially complex, and the economics of open-pit mining — moving enormous volumes of material with big trucks and shovels — suit the low value-per-tonne nature of the commodity. Underground mining does occur, notably in parts of Sweden where the ore body extends deep beneath the surface, but it is exceptional rather than typical.
The grade of an ore body — that is, the proportion of iron it contains by weight — matters enormously to the economics of mining. High-grade direct-shipping ore can be loaded, shipped and used at a steelmaker's blast furnace with little more than crushing and screening to remove fines. Lower-grade ore, including much of the magnetite ore found in parts of Australia and elsewhere, must be ground finely and concentrated before it is useful, which adds cost and energy. The ratio of waste rock removed to ore actually recovered, sometimes called the strip ratio, can be very large in open-pit operations: a great deal of rock that contains no useful iron must be moved to expose the ore beneath it, and managing that waste safely and at scale is one of the defining engineering and environmental challenges of large iron ore mines.
Pelletising is the process used to make concentrated lower-grade ore suitable for a blast furnace or direct-reduction plant. The fine concentrate is mixed with a binder, rolled into small balls and fired in a kiln to harden them. Pellets are more consistent in chemistry and physical form than lump ore, which matters to the efficiency of the furnace receiving them. The shift toward lower-grade deposits, as the richest direct-shipping ore is gradually depleted, means that pelletising capacity is becoming a more significant part of the overall supply chain.
What pulls on it
Steel is a material of structure and motion. The largest single pull on it comes from construction — buildings, bridges, roads, rail lines and the infrastructure beneath cities. This demand is closely tied to the rate at which the built environment is being created or renewed, which in turn reflects where in the world income growth is fastest and where populations are urbanising. The tables on this page show that China accounts for the largest share of both production and, by implication, consumption, reflecting several decades of intensive urbanisation and infrastructure building. India's figures point to a country that is considerably earlier in the same process.
Beyond construction, manufacturing of all kinds pulls on steel: vehicles, machinery, appliances, ships, pipelines and agricultural equipment all depend on it. The intensity figures on this page give a sense of how some newer demand categories translate into tonnes of steel. A single direct-drive offshore wind turbine requires a very large mass of steel in its tower, nacelle frame and foundation — the figures given run into the hundreds of thousands of kilograms per megawatt of capacity. Alkaline electrolysers for hydrogen production and HVDC cable armouring are further examples of demand categories linked to energy transition infrastructure, and these are growing from a low base as deployment of those technologies increases.
Demand for steel would change sharply in either direction only under fairly large structural shifts. A sustained slowdown in construction activity in the major consuming economies — or a material change in how buildings and infrastructure are built — would reduce the absolute volume required. On the growth side, the scale of energy transition infrastructure, if fully built out over the coming decades, represents a substantial additional call on steel output, though the timing and pace remain uncertain.
Turning ore into product 级别 3
Between the mine and the steelworks, iron ore passes through a chain of steps whose complexity depends heavily on ore grade and mineralogy. High-grade haematite ore may need only crushing and screening — breaking the rock into manageable sizes and separating coarse lump ore from fines — before it is saleable. Magnetite ore, which is magnetically distinct from the surrounding waste minerals, can be concentrated efficiently using magnetic separation after fine grinding (comminution), but the energy cost of grinding hard rock to the fineness required is substantial and represents a significant share of operating cost at magnetite operations.
At the steelworks, the dominant processing route remains the blast furnace — basic oxygen furnace, or BF-BOF, pathway. In the blast furnace, iron ore (in the form of sinter, pellets or lump), coke (a form of carbon made from coking coal) and limestone are charged from the top. Hot air, sometimes enriched with oxygen, is blasted in from the bottom. The coke burns and produces carbon monoxide, which reduces the iron oxides in the ore to metallic iron. Limestone reacts with silica and other impurities to form a liquid slag that floats on the iron and is tapped off separately. The iron that emerges — called hot metal or pig iron — contains several percent of dissolved carbon along with manganese, silicon, phosphorus and sulfur. It is then transferred to a basic oxygen furnace, where a lance blows high-purity oxygen through the melt. This burns off most of the carbon and other impurities very rapidly, producing crude steel. The slag generated in the BOF carries the oxidised impurities away. Alloying elements — manganese, silicon, chromium, nickel and others depending on the steel specification — are added at this stage or in subsequent ladle metallurgy.
The electric arc furnace, or EAF, route melts scrap steel (or, increasingly, directly reduced iron) using electrical energy rather than coke. It operates at smaller scale and with greater flexibility in charge materials than a blast furnace, and it is the dominant route in countries where scrap is plentiful and electricity is relatively cheap. The EAF produces lower residual levels of some alloying elements than scrap-based charge materials can introduce, which limits its use for some high-specification flat-rolled products unless the charge is diluted with virgin iron units. The data tables on this page show world crude steel production as a single headline figure; the split between BF-BOF and EAF output is not distinguished in that number, though the two routes have substantially different cost structures, emissions profiles and input requirements.
Substitution and recycling 级别 3
For most of its structural applications, steel faces competition from a relatively limited set of materials. Aluminium alloys are lighter per unit volume and resist corrosion without protective coatings, making them attractive in transport applications where weight reduction justifies higher material cost. Concrete handles compressive loads effectively but requires steel reinforcement (rebar) to manage tension, so the two are more often complements than substitutes. Engineered timber has re-entered commercial consideration for mid-rise building frames in some markets, but its fire performance and the consistency of large structural sections remain constraints. In highly loaded or precision-engineered applications, the combination of strength, stiffness, formability, weldability and cost that steel offers is not easily matched by any single alternative across the full range of uses simultaneously.
Substitution at the product level — replacing steel with another material in a specific application — is technically possible in many cases and already occurs where economics or regulation favour it. What substitution does not do is displace steel wholesale. The sheer breadth of its uses, from the structural frame of a building to the laminations in an electric motor, means that no other material is positioned to replace it across the board.
Recycling is where steel's supply picture differs most from that of many other metals. Steel is highly recyclable and is recycled at scale through the electric arc furnace route. The magnetic properties of steel make it straightforward to recover from mixed waste streams using magnetic separation, which is why steel is among the most-recovered materials in municipal and industrial waste processing. The constraint on higher recycling rates is not primarily technical but material-balance: steel has a long service life in buildings and infrastructure, so the scrap available in any given period reflects what was produced and installed decades earlier, not what is being consumed now. Periods of rapid demand growth tend to run ahead of scrap availability, creating continued demand for virgin iron units from ore.
Where the chain is fragile 级别 4
The published headline figures for crude steel production aggregate output from two routes — blast furnace and electric arc furnace — that have different vulnerability profiles and should not be treated as interchangeable. The data unit basis note on this page makes this explicit. A reader drawing conclusions about, say, coking coal dependence or scrap availability from the headline production figure alone will be working with an incomplete picture, because those two inputs feed entirely separate parts of the industry. World production figures also rely on national reporting that varies in methodology and timeliness; the figures for some countries are estimates, and revisions can be significant.
Concentration is the most obvious structural feature of the iron and steel supply chain. The production figures on this page show that one country accounts for a share of global output that is very large relative to any other single producer. That concentration exists at multiple points: in iron ore mining, in coking coal supply, in pelletising capacity and in crude steel output. It means that policy shifts, energy constraints, environmental regulation or economic slowdown in that country propagate through global steel markets in ways that are difficult to hedge. At the same time, steel is not a commodity that moves freely as a uniform global product in the way that, say, copper cathode does; finished steel products face tariffs, anti-dumping measures and technical standards that segment the market geographically and create regional pricing divergences.
The deeper fragility in the chain concerns the transition away from the blast furnace route. Green steel — made via direct reduction of iron ore with hydrogen, or via the EAF route — requires either very large quantities of low-emissions electricity or access to low-cost green hydrogen, neither of which is currently available at the scale the industry would need. The lead time for building new steelmaking capacity is long, and existing blast furnaces represent large sunk capital investments with operating lives that extend for decades. The result is a technology transition in which the direction is broadly agreed but the pace and financing are not, and in which stranded-asset risk and permitting timelines create genuine uncertainty about how quickly the emissions profile of the industry can change.
生产主体
在地图上查看 →Pig iron
Pig ironmillion metric tons 2025 (估计值) 全球合计 1,300 million metric tons
USGS Mineral Commodity Summaries 2026 · Crude steel production in million tonnes; blast-furnace and electric-arc routes are not distinguished in the headline figure. · 来源 ↗
横向滚动表格以查看其余列。
| 国家/地区 | 产量 | 占全球份额 |
|---|---|---|
| China | 830.0 | 63.8% |
| India | 98.00 | 7.5% |
| Other countries | 61.00 | 4.7% |
| Japan | 59.00 | 4.5% |
| Russia | 47.00 | 3.6% |
| Korea, Republic of | 41.00 | 3.2% |
| Brazil | 28.00 | 2.2% |
| Germany | 25.00 | 1.9% |
| United States | 21.00 | 1.6% |
| Vietnam | 14.00 | 1.1% |
| Turkey | 10.00 | 0.8% |
| Iran | 4.00 | 0.3% |
| 全球合计 | 1,300 | 100% |
Raw steel
Raw steelmillion metric tons 2025 (估计值) 全球合计 1,900 million metric tons
USGS Mineral Commodity Summaries 2026 · Crude steel production in million tonnes; blast-furnace and electric-arc routes are not distinguished in the headline figure. · 来源 ↗
横向滚动表格以查看其余列。
| 国家/地区 | 产量 | 占全球份额 |
|---|---|---|
| China | 980.0 | 51.6% |
| Other countries | 230.0 | 12.1% |
| India | 160.0 | 8.4% |
| United States | 82.00 | 4.3% |
| Japan | 81.00 | 4.3% |
| Russia | 65.00 | 3.4% |
| Korea, Republic of | 60.00 | 3.2% |
| Germany | 38.00 | 2.0% |
| Turkey | 37.00 | 1.9% |
| Brazil | 35.00 | 1.8% |
| Iran | 32.00 | 1.7% |
| Vietnam | 23.00 | 1.2% |
| 全球合计 | 1,900 | 100% |
steel slag production was estimated to be between 190 million and 290 million tons
steel slag production was estimated to be between 190 million and 290 million tonsmillion metric tons 2025 (估计值) 全球合计 240.0 million metric tons
USGS Mineral Commodity Summaries 2026 · Crude steel production in million tonnes; blast-furnace and electric-arc routes are not distinguished in the headline figure. · 来源 ↗
横向滚动表格以查看其余列。
| 国家/地区 | 产量 | 占全球份额 |
|---|---|---|
| 全球合计 | 240.0 | 100% |
world iron slag production was estimated to be between 330 million and 390 million tons,
world iron slag production was estimated to be between 330 million and 390 million tons,million metric tons 2025 (估计值) 全球合计 360.0 million metric tons
USGS Mineral Commodity Summaries 2026 · Crude steel production in million tonnes; blast-furnace and electric-arc routes are not distinguished in the headline figure. · 来源 ↗
横向滚动表格以查看其余列。
| 国家/地区 | 产量 | 占全球份额 |
|---|---|---|
| 全球合计 | 360.0 | 100% |
"未披露"表示美国地质调查局(USGS)为避免泄露单个企业数据而对该数字进行了保密处理——并不意味着数值为零。各国行数之和不一定等于世界合计,原因在于来源对每个数字单独进行四舍五入处理,且并不总是单独列出"其他国家/地区"一行。
价格
average unit value, free on board plant, dollars per metric ton
年度平均值dollars per metric ton
基准: average unit value, free on board plant, dollars per metric ton. 年度平均值,来源: USGS Mineral Commodity Summaries 2026 · 来源 ↗. 以下为参考年度均价,非实时市场报价。
Producer price index, steel mill products (1982=100)
年度平均值index
基准: Producer price index, steel mill products (1982=100). 年度平均值,来源: USGS Mineral Commodity Summaries 2026 · 来源 ↗. 以下为参考年度均价,非实时市场报价。
其加工与精炼地点
| 工厂 | 类型 | 阶段 | 国家/地区 | 角色 |
|---|---|---|---|---|
| Wind Turbine Nacelle & Blade Plants, Jutland | 制造厂 | 产品 | Denmark | 输入 |
其用途
所有终端市场 →| 终端市场 | 其在彼处的用途 | 重要性 |
|---|---|---|
| Power Grids | Towers, transformer cores and enclosures | 定义 |
| Wind Power | Tower, nacelle frame and foundation | 定义 |
| Construction & Steel | Structure, rebar and rail | 定义 |
| Electric Vehicles | Structure and motor laminations | 重要 |
| Data Centres & AI | Structure and enclosures | 重要 |
| Hydrogen & Electrolysis | Stacks, vessels and piping | 重要 |
某项技术的需求用量
| 技术 | 数量 | 报价 | 基准 |
|---|---|---|---|
| Alkaline Electrolyser | 2,000–5,000 kg | per MW of capacity | Stack, frames and vessels |
| Direct-Drive Offshore Wind Turbine Dominates the mass by far. | 100,000–180,000 kg | per MW of capacity | Tower, nacelle and foundation |
| EV Traction Motor | 20.00–40.00 kg | per motor | Electrical steel laminations |
| HVDC Transmission Cable | 20.00–80.00 t | per km of circuit | Armouring |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. 在物料计算器中按任意规模运行这些数据 →
出口管制
| 国家/地区 | 管控 | 适用于 |
|---|---|---|
| Laos | Export ban | Raw minerals, including copper, gold, iron, nickel, potassium, silver, and zinc (2024). ↗ |
| Vietnam | Export ban | Raw materials of iron, lead-zinc, chromite, manganese, apatite, and rare earths and deeply processed titanium (2012). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.
跟踪其跨境全程
全部溯源记录 →这批材料实际经过的路线——每个国家、每位托管方,以及每个环节留下的内容。
New Caledonian laterite to stainless steel An island that smelts its own ore, and pays for it with the most expensive electricity in the industry.