これは何か
A silvery metal that resists rust, which is why it goes into stainless steel — and, more recently, into the cathodes that give an EV its range.
なぜ重要なのか
Two-thirds of nickel still goes into stainless steel, but the battery share is what moved the market: raising nickel in a cathode raises the energy the cell can hold.
Where it is in the Earth
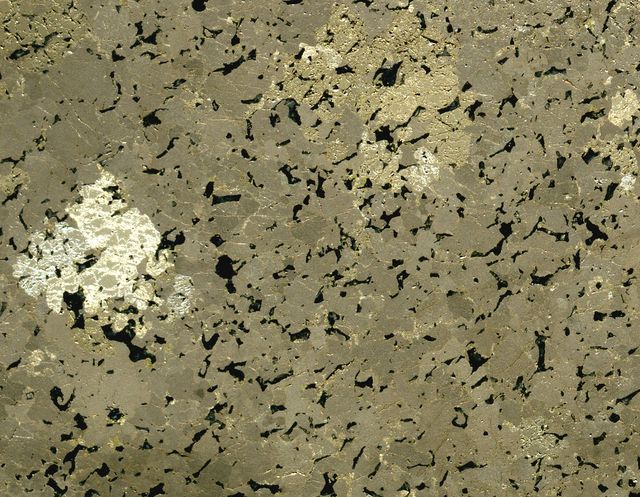
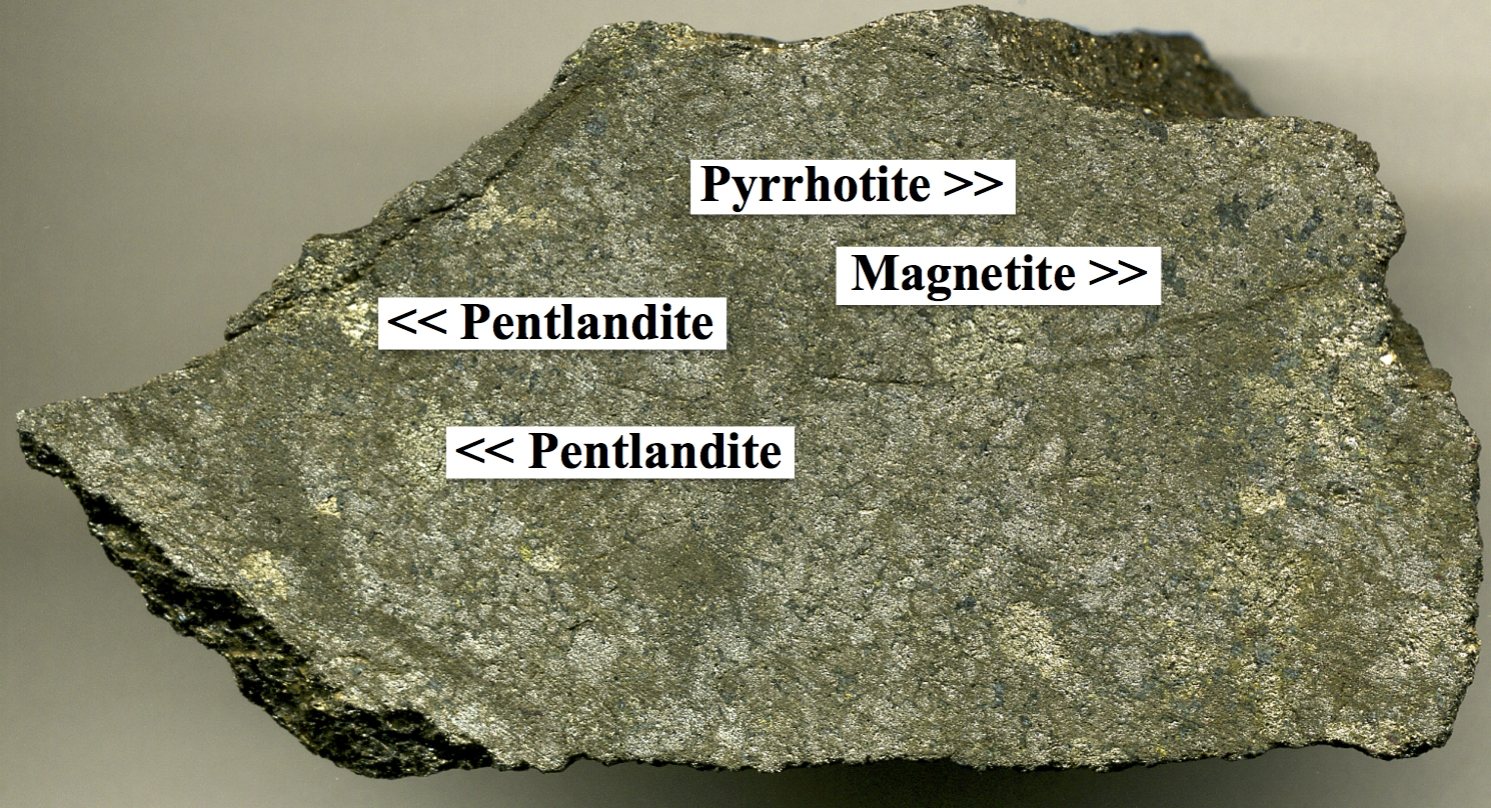
Nickel reaches minable concentrations through two quite different geological processes, which is why the deposits look nothing like each other and require very different methods to extract. The first process is magmatic: when molten rock rich in iron, magnesium and sulfur cools slowly deep in the crust, nickel tends to follow sulfur and iron into droplets of liquid sulfide that sink through the magma and pool at the base of the intrusion. When that melt eventually solidifies, the result is a sulfide ore body — rock threaded with the mineral pentlandite — carrying nickel grades that the data here put at roughly one to three percent by weight. The great sulfide camps of Sudbury in Canada and Norilsk-Talnakh in Russia formed this way, though Sudbury has the additional distinction of having been shaped or at least reprocessed by a meteorite impact, which concentrated the sulfides further.
The second process is entirely at the surface. When ancient ultramafic rocks — the same iron- and magnesium-rich rock types that host sulfide deposits — are exposed to prolonged tropical weathering over millions of years, water slowly dissolves and carries away much of the magnesium and silica. Nickel, being less mobile, is left behind and gradually enriches in the remaining clay and oxide minerals near the surface. The result is a laterite deposit: a broad, shallow blanket of reddish or greenish saprolite and limonite that can extend over a large area but carries nickel in a fundamentally different mineralogical form, mainly in the silicate garnierite or locked into iron oxide minerals. Indonesia sits on one of the world's largest accumulations of these laterised ultramafic rocks, which is why it now accounts for so large a share of world output.
The distinction between sulfide and laterite is not merely geological curiosity. Sulfide ores tend to occur at depth and in discrete bodies, making them amenable to selective underground mining and relatively straightforward concentration by flotation. Laterite ores are widespread, near-surface and fine-grained, which makes them harder to concentrate by physical means and generally requires either smelting or hydrometallurgical leaching — processes that consume considerably more energy per tonne of nickel produced. Where a deposit sits on the geological spectrum between these two end-members shapes almost every subsequent decision in the supply chain.
Getting it out
Sulfide nickel deposits are typically mined underground, because the ore bodies are narrow, steeply dipping and located at considerable depth. Miners drive tunnels to reach the ore zone and use methods such as cut-and-fill or blasthole stoping — essentially carving out large underground chambers — to extract the rock. The ore grades associated with sulfide deposits, running around one to two percent nickel, sound low, but because so much of the unwanted rock (called gangue) can be left underground or managed as tailings after milling, the economics can work well. The Norilsk-Talnakh complex in Russia and the Sudbury Basin in Canada are the canonical examples of this type.
Laterite deposits are a different matter. Because the enriched material forms a near-surface blanket, it is usually stripped by open-pit methods: overburden is removed, and the ore is excavated in horizontal benches. The Sorowako operation in Indonesia follows this pattern. The trade-off is that laterite ore is bulky and low-grade relative to the energy needed to process it, so very large volumes of material move through the system for each tonne of nickel recovered. There is no clean separation step equivalent to flotation: the nickel is dispersed through the clay and oxide minerals in a way that only heat or acid can release.
Grade matters in practice because it determines the ratio of waste to product at every stage. A mine processing ore at one percent nickel must handle a hundred tonnes of rock to obtain one tonne of contained metal, and most of those hundred tonnes must be moved, crushed, processed and disposed of. For laterite operations, the processing waste — whether slag from a smelter or tailings from a pressure-acid-leach plant — is substantial in volume and must be managed carefully to prevent environmental contamination, particularly because laterite processing often involves strong acids or high-pressure steam.
What pulls on it
Nickel's demand story has two quite separate chapters that are sometimes conflated. The older and larger chapter is stainless steel. Stainless steel is an alloy of iron, chromium and nickel in which the nickel stabilises a particular crystalline structure (the austenite phase) that gives the steel its combination of formability and corrosion resistance. Around two-thirds of all nickel consumed goes into this application, and that fraction has remained broadly stable for decades. Stainless steel production tends to follow construction activity, industrial output and consumer goods manufacturing, so nickel demand from this sector tracks general economic conditions rather than any specific technology transition.
The newer chapter is batteries. Nickel-manganese-cobalt (NMC) cathode chemistries, which dominate much of the electric vehicle market, use nickel as the primary active material. Raising the nickel share of the cathode increases the energy density — the amount of electricity the cell can store per kilogram — which in turn extends the range a vehicle can travel on a single charge. This is why battery manufacturers have progressively moved towards higher-nickel formulations. The intensity figures in the table on this page quantify what that means in practice: an NMC pack of the size typical for a mid-range electric vehicle contains between 40 and 60 kilograms of contained nickel. Multiply that by the number of vehicles being produced and the arithmetic makes clear why battery demand has become the part of the nickel market that attracts the most attention.
Beyond steel and batteries, nickel appears in superalloys used in the hot sections of aircraft engines, in alloys for nuclear steam generators, and in the electrodes of alkaline electrolysers used to produce hydrogen. These are smaller in volume than stainless steel but often require high-purity material and are less price-sensitive, so they carry disproportionate weight in discussions of supply adequacy. What would have to change for demand to shift sharply? On the battery side, a sustained move toward lithium iron phosphate (LFP) cathode chemistry — which contains no nickel at all — would reduce growth in battery demand. On the stainless side, a prolonged slowdown in global industrial output would reduce the base load. Neither of these is a certainty; they are simply the main variables that would alter the trajectory.
岩石中の産出箇所
全鉱石鉱物 →実際に以下を担う鉱物 nickel. 鉱床が鉱体となるのは、採掘コストを回収できるほど十分な濃度で鉱石が濃集している場合に限られる。
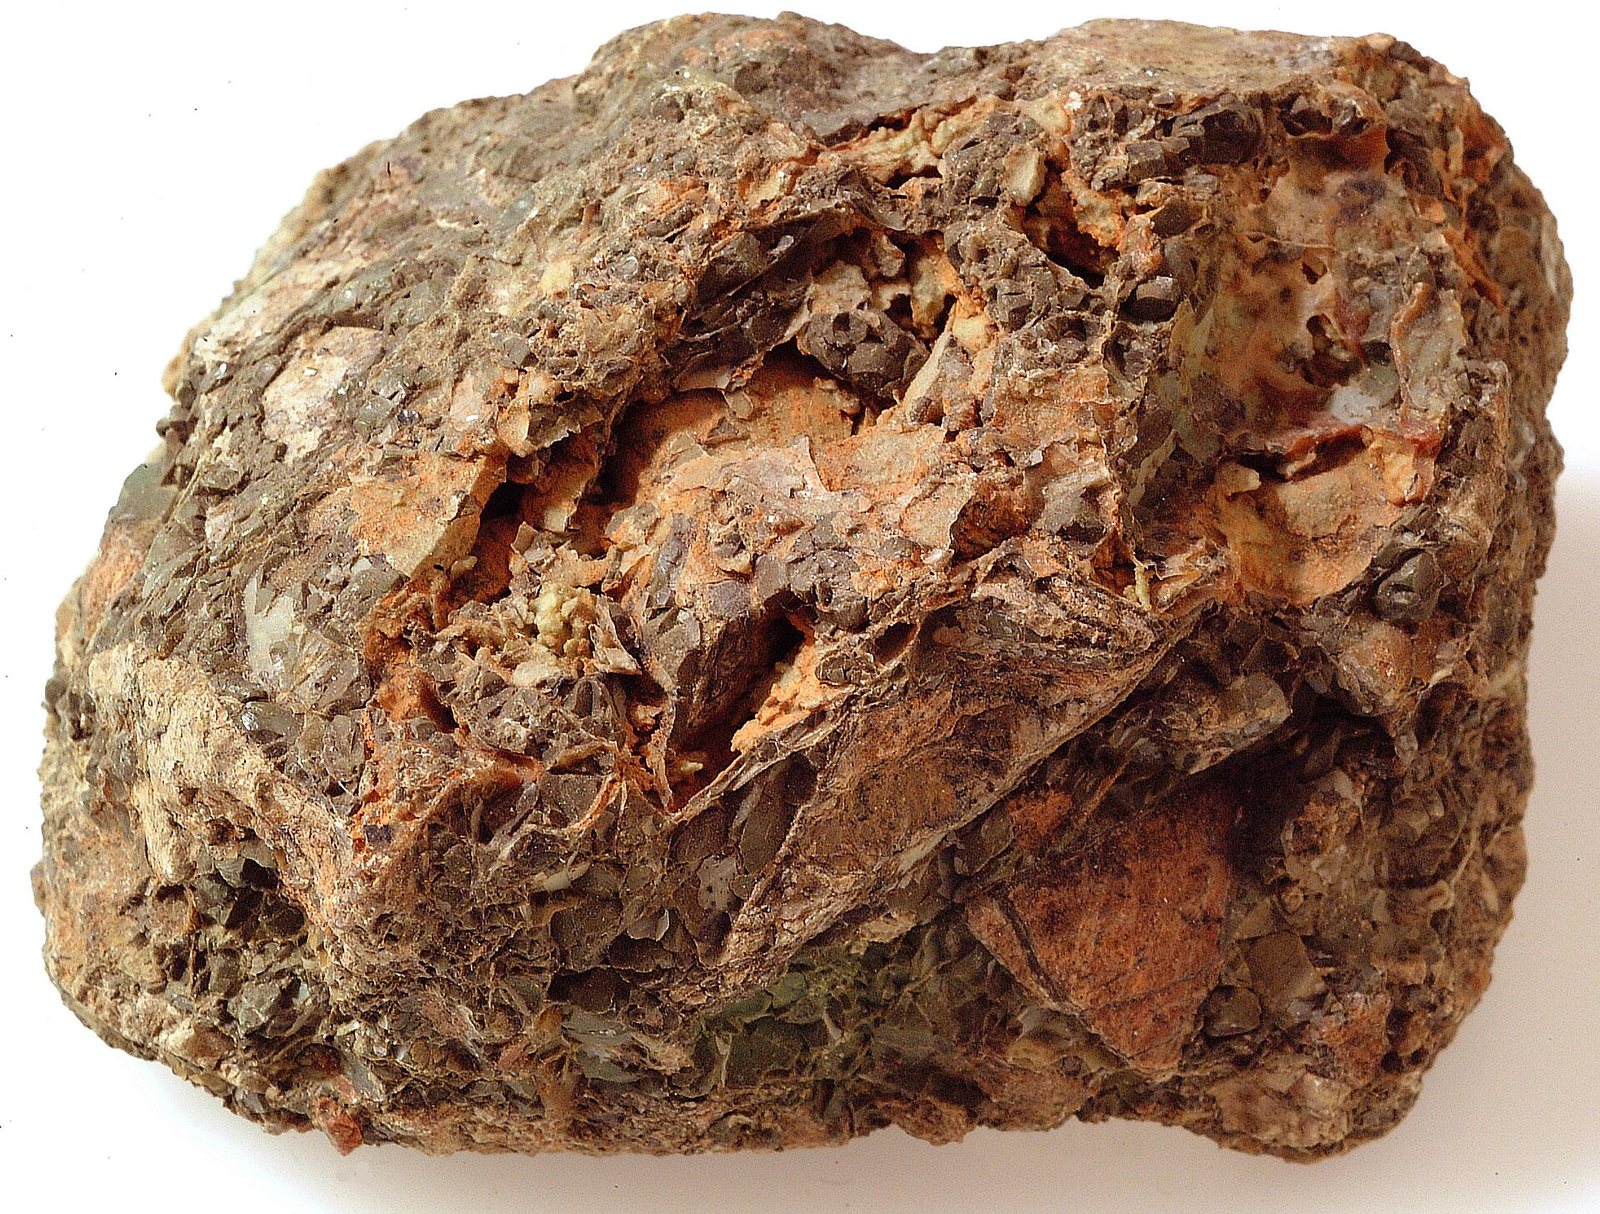
Garnierite (nickel laterite)
A green nickel silicate from tropically weathered rock. Laterite ore is soft and shallow but needs high-pressure acid…
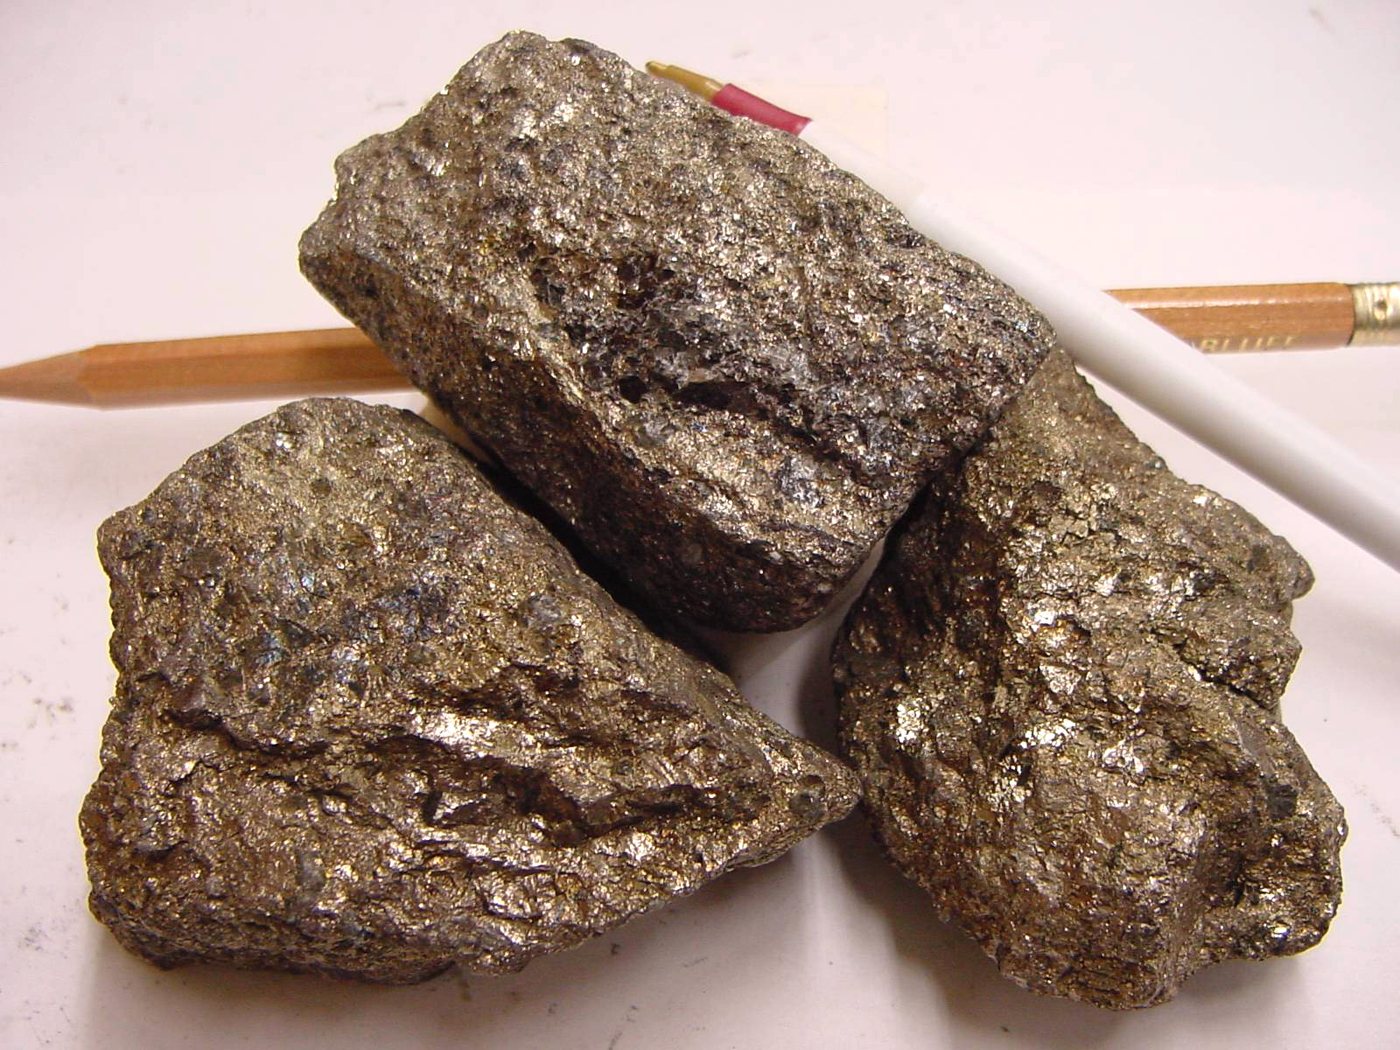
Pentlandite
The main nickel sulfide ore mineral, and the host that also carries most by-product platinum-group metals.
生産者
地図で見る →Mine production
Mine productionmetric tons 2025 (推定値) 世界合計 3,900,000 metric tons
USGS Mineral Commodity Summaries 2026 · Tonnages are contained nickel. Grades differ enormously: sulfide ore may run 1-2% Ni, laterite ore under 1.5%. · 出典 ↗
テーブルを横にスクロールすると残りの列が表示されます。
| 国 | 生産 | 世界に占める割合 |
|---|---|---|
| Indonesia | 2,600,000 | 66.7% |
| Other countries | 290,000 | 7.4% |
| Philippines | 270,000 | 6.9% |
| Russia | 200,000 | 5.1% |
| Canada | 140,000 | 3.6% |
| New Caledonia | 140,000 | 3.6% |
| China | 120,000 | 3.1% |
| Brazil | 70,000 | 1.8% |
| Australia | 45,000 | 1.2% |
| United States | 10,000 | 0.3% |
| 世界合計 | 3,900,000 | 100% |
「非開示」とは、個別企業のデータが特定されないようUSGSが数値を公表しなかったことを意味し、ゼロを意味するものではありません。出典が各数値を独立して丸め処理しており、「その他の国」の内訳を常に示しているわけではないため、各国の数値の合計が世界合計と一致しないことがあります。
埋蔵量の保有者
Reserves
Reservesmetric tons 2025
USGS Mineral Commodity Summaries 2026 · 出典 ↗
| 国 | 埋蔵量 | 世界に占める割合 |
|---|---|---|
| Indonesia | 62,000,000 | 44.3% |
| Australia | 25,000,000 | 17.9% |
| Brazil | 16,000,000 | 11.4% |
| Other countries | >9,100,000 | 6.5% |
| Russia | 8,300,000 | 5.9% |
| New Caledonia | 7,100,000 | 5.1% |
| Philippines | 4,800,000 | 3.4% |
| China | 4,400,000 | 3.1% |
| Canada | 2,200,000 | 1.6% |
| United States | 340,000 | 0.2% |
| 世界合計 | >140,000,000 | 100% |
情報源はこの世界合計値を点推定値ではなく範囲推定値として公表しているため、最終列のシェアもそれ自体が範囲推定値となる。
価格
Nickel, global price
年間平均US$ per tonne
基準: IMF global price of nickel — melting grade, LME spot. 以下に公表された年間平均値: FRED (IMF primary commodity prices) · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
average annual, London Metal Exchange (LME), cash: Dollars per metric ton
年間平均dollars per metric ton
基準: average annual, London Metal Exchange (LME), cash: Dollars per metric ton. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
average annual, London Metal Exchange (LME), cash: Dollars per pound
年間平均dollars per pound
基準: average annual, London Metal Exchange (LME), cash: Dollars per pound. 以下に公表された年間平均値: USGS Mineral Commodity Summaries 2026 · 出典 ↗. これらは参照用の年間平均値であり、リアルタイムの市況相場ではない。
産出鉱山
全鉱山 →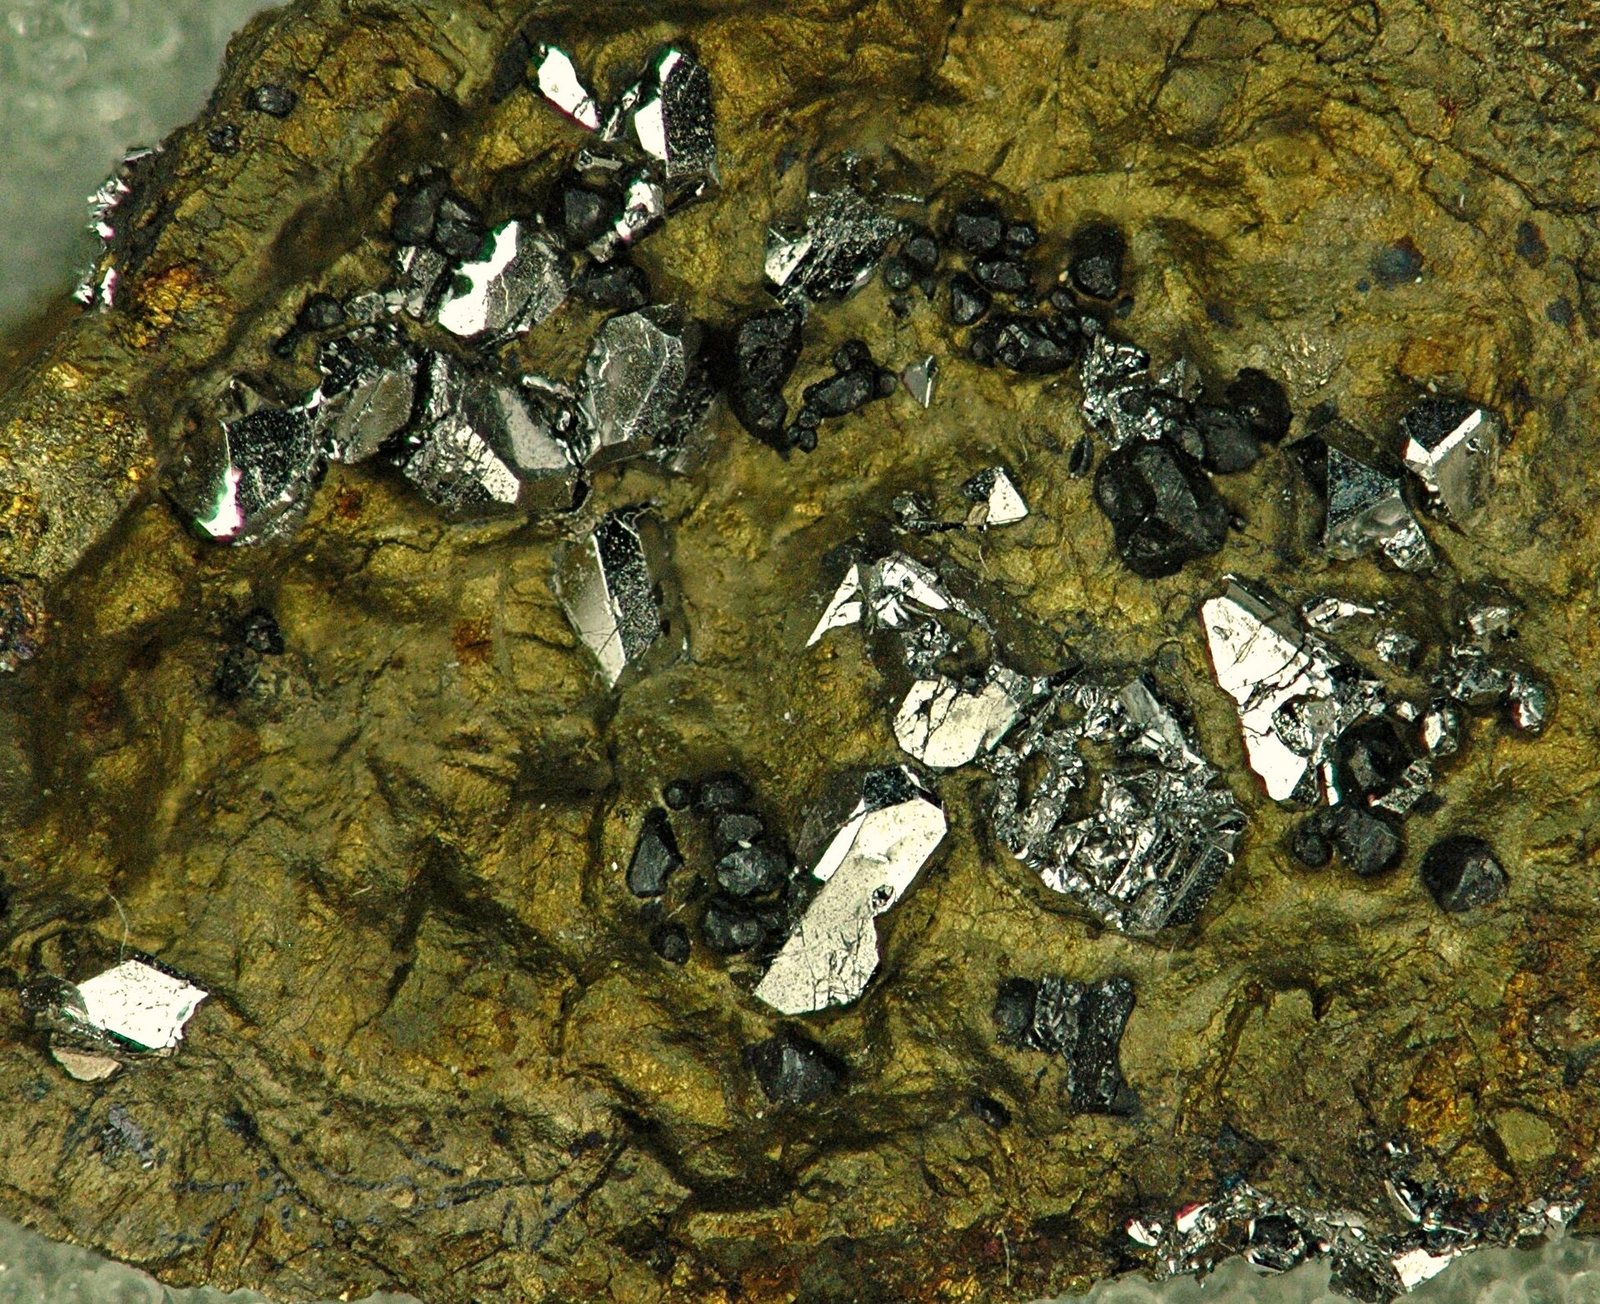
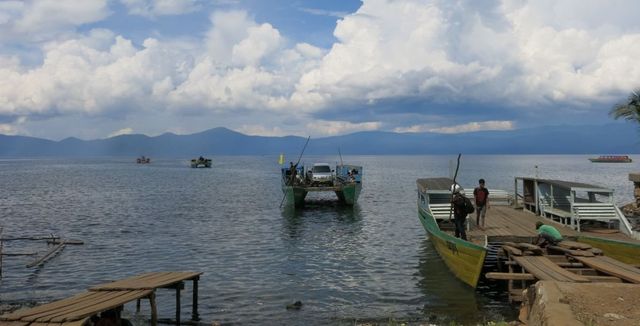
Sorowako
One of Indonesia's long-established integrated nickel operations.
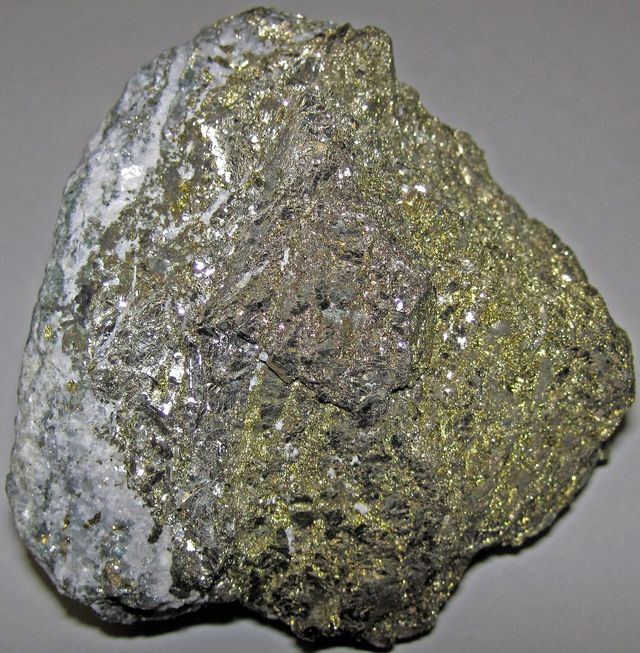
Sudbury Basin
One of the longest-producing nickel districts on Earth.
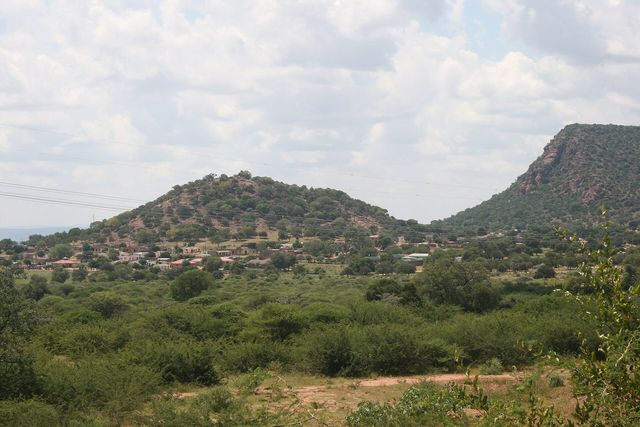
Mogalakwena
The largest open-pit platinum-group metals mine in the world.
処理・精製が行われる場所
| プラント | 種別 | ステージ | 国 | 役割 |
|---|---|---|---|---|
| Gigafactory Nevada | ギガファクトリー | コンポーネント | United States | 投入 |
| Indonesia Morowali Industrial Park | 製錬所 | 処理 | Indonesia | 産出物 |
| Nadezhda Metallurgical Plant | 製錬所 | 処理 | Russia | 産出物 |
| Aero-Engine Turbine Plant, Derby | 製造プラント | 製品 | United Kingdom | 投入 |
| Huayou Cobalt Refineries | 化学プラント | 精製 | China | 投入 |
| Jinchuan Group Smelter-Refinery | 精製所 | 精製 | China | 産出物 |
| Rustenburg Base & Precious Metals Refineries | 精製所 | 精製 | South Africa | 投入 |
用途
全エンドマーケット →| 最終市場 | そこでの機能 | 重要度 |
|---|---|---|
| Electric Vehicles | Raises the energy the cathode can hold | 定義 |
| Aerospace & Defence | Superalloy for hot sections | 定義 |
| Hydrogen & Electrolysis | Alkaline electrolyser electrodes | 定義 |
| Nuclear Power | Alloys for steam generators | 重要 |
技術が必要とする量
| 技術 | 数量 | 建値 | 基準 |
|---|---|---|---|
| Alkaline Electrolyser | 300.0–800.0 kg | per MW of capacity | Electrodes and catalyst coatings |
| NMC Lithium-Ion Battery NMC811 cathode is roughly 0.7 kg Ni per kWh. | 40.00–60.00 kg | per 75 kWh pack | Contained nickel |
| Pressurised Water Reactor | 500.0–1,500 t | per GW of capacity | Steam generators and alloy components |
| Single-Crystal Turbine Blade Typically 60% or more of the alloy. | 微量 | per blade set | Superalloy base |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. 素材計算機で任意の規模に換算して実行 →
輸出規制
| 国 | 支配 | 適用対象 |
|---|---|---|
| Indonesia | Export ban | Bauxite (2023), copper concentrates (2023), and nickel ore (2020). ↗ |
| Laos | Export ban | Raw minerals, including copper, gold, iron, nickel, potassium, silver, and zinc (2024). ↗ |
| Tanzania | Export ban | Ore concentrates of copper, gold, nickel, and silver (2017). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.
越境地点をたどる
すべての輸送経路 →この素材の特定の貨物が実際にたどる経路——すべての国、すべての管理者、各工程で残されるもの。
Indonesian laterite to a battery cathode A country that banned raw ore exports and built the processing industry instead. New Caledonian laterite to stainless steel An island that smelts its own ore, and pays for it with the most expensive electricity in the industry.