Wat is het?
A soft, silvery metal so light it floats on water, and the element that lets a rechargeable battery store a lot of energy for very little weight.
Waarom is het van belang?
Almost every phone, laptop and electric car on Earth runs on a lithium-ion battery. There is no drop-in replacement that matches it on energy per kilogram today.
Getting it out
Hard-rock lithium deposits, principally the spodumene pegmatites of Australia and southern Africa, are mined by open-pit methods. Miners remove the overlying rock — called overburden — expose the orebody, and extract it in benches cut down through the deposit. The proportion of waste rock moved for every tonne of ore recovered varies with the geometry of the deposit and how deeply it runs, but in any open-pit operation this stripping ratio is a significant part of the cost. The ore is then crushed and processed on site to produce a spodumene concentrate, a product containing around 6 percent lithium oxide (Li₂O) by weight. This concentrate is the form in which most Australian lithium leaves the country, travelling to chemical plants — predominantly in China — for further conversion.
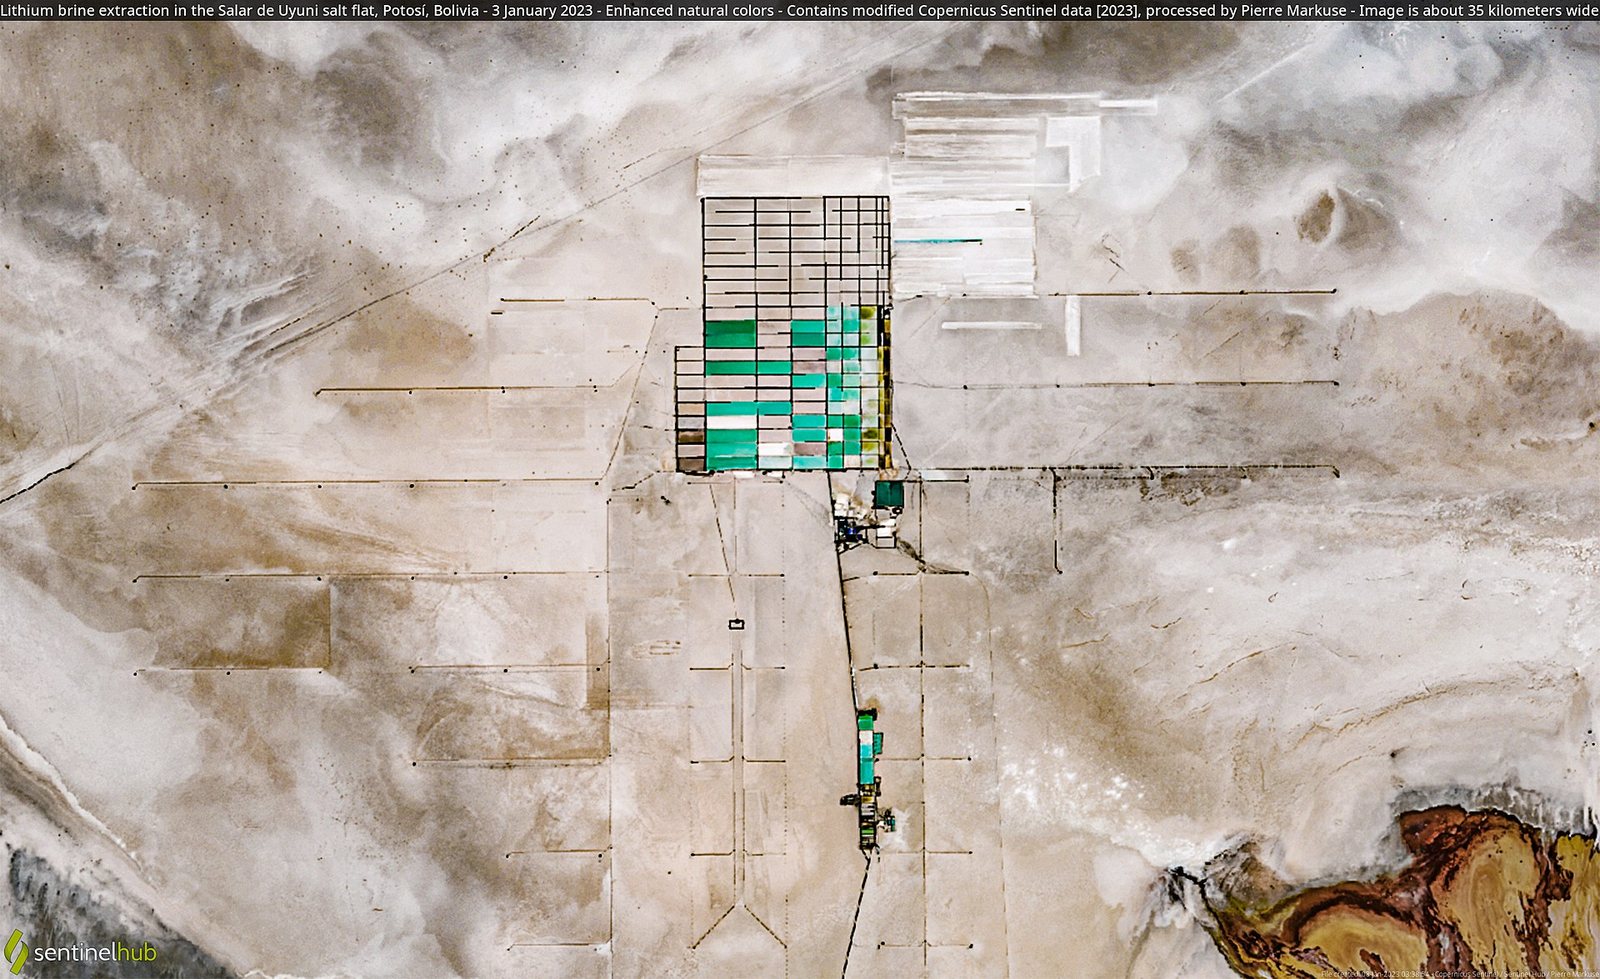
Brine deposits work entirely differently. Operators drill wells into the salt flat and pump the lithium-bearing brine to the surface, where it is directed into a sequence of large, shallow evaporation ponds. Solar energy does most of the work: over many months, water evaporates and unwanted salts crystallise out, progressively concentrating the lithium. When the brine has been sufficiently enriched, it moves to a chemical plant for further purification and conversion into lithium carbonate or lithium hydroxide. The process is slow — a full evaporation cycle can take well over a year — and the large pond footprint means it uses considerable land area in ecosystems that are ecologically and hydrologically sensitive. More recently, direct lithium extraction (DLE) technologies, which use selective adsorbent or membrane materials to pull lithium from brine without lengthy evaporation, are being piloted at several sites, including at Salar del Hombre Muerto in Argentina. DLE promises faster processing and a smaller footprint, but most projects using it are not yet operating at full commercial scale.
The clay-hosted deposit at Thacker Pass in the United States involves open-pit mining followed by acid leaching of the crushed claystone — a process closer to hydrometallurgy than to conventional mineral processing. Because this deposit type is still at an early stage of commercial development, the practical performance of the full process at scale remains to be demonstrated under operating conditions.
What pulls on it
The dominant use of lithium today is in rechargeable batteries, and within that category the largest single application is the electric vehicle. Both of the main cathode chemistries in wide use — lithium iron phosphate (LFP) and nickel manganese cobalt oxide (NMC) — incorporate lithium as a functional element that shuttles between electrodes during each charge and discharge cycle. The material-intensity data on this page shows that a single 75 kWh battery pack requires several kilograms of contained lithium, meaning that each vehicle placed on the road represents a discrete, sizeable demand event. Consumer electronics — phones, laptops, tablets — also rely on lithium-ion cells, and grid-scale battery storage for electricity networks is a growing application as more intermittent renewable generation is added to grids.
Before the battery era, lithium's main markets were quite different: glass and ceramics (where it improves thermal properties), lubricating greases, air treatment, and pharmaceutical compounds. Those uses have not disappeared, but they have shrunk as a share of total demand as battery growth has outrun everything else. The practical consequence is that the lithium market's fortunes are now tightly coupled to the rate at which battery-powered vehicles and storage systems are adopted. If that adoption accelerated, demand would rise accordingly; if policy support for electric vehicles were withdrawn in major markets, or if a competing battery chemistry emerged that did not require lithium, the demand picture would change substantially. Neither the pace of adoption nor the development of alternative chemistries is fixed, which is what makes demand forecasting in this market genuinely uncertain.
It is worth noting that demand does not translate directly into lithium consumption without accounting for the efficiency of the manufacturing chain. Cathode production involves its own yield losses, and scrap generated within battery factories does not all return to the supply chain cleanly. The intensity figures are for finished packs, and the quantity of lithium that must actually be mined to deliver one finished pack is somewhat higher than those figures alone suggest.
Where it is in the Earth
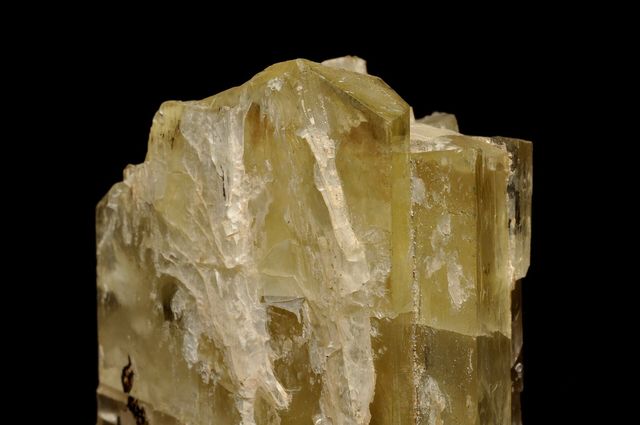
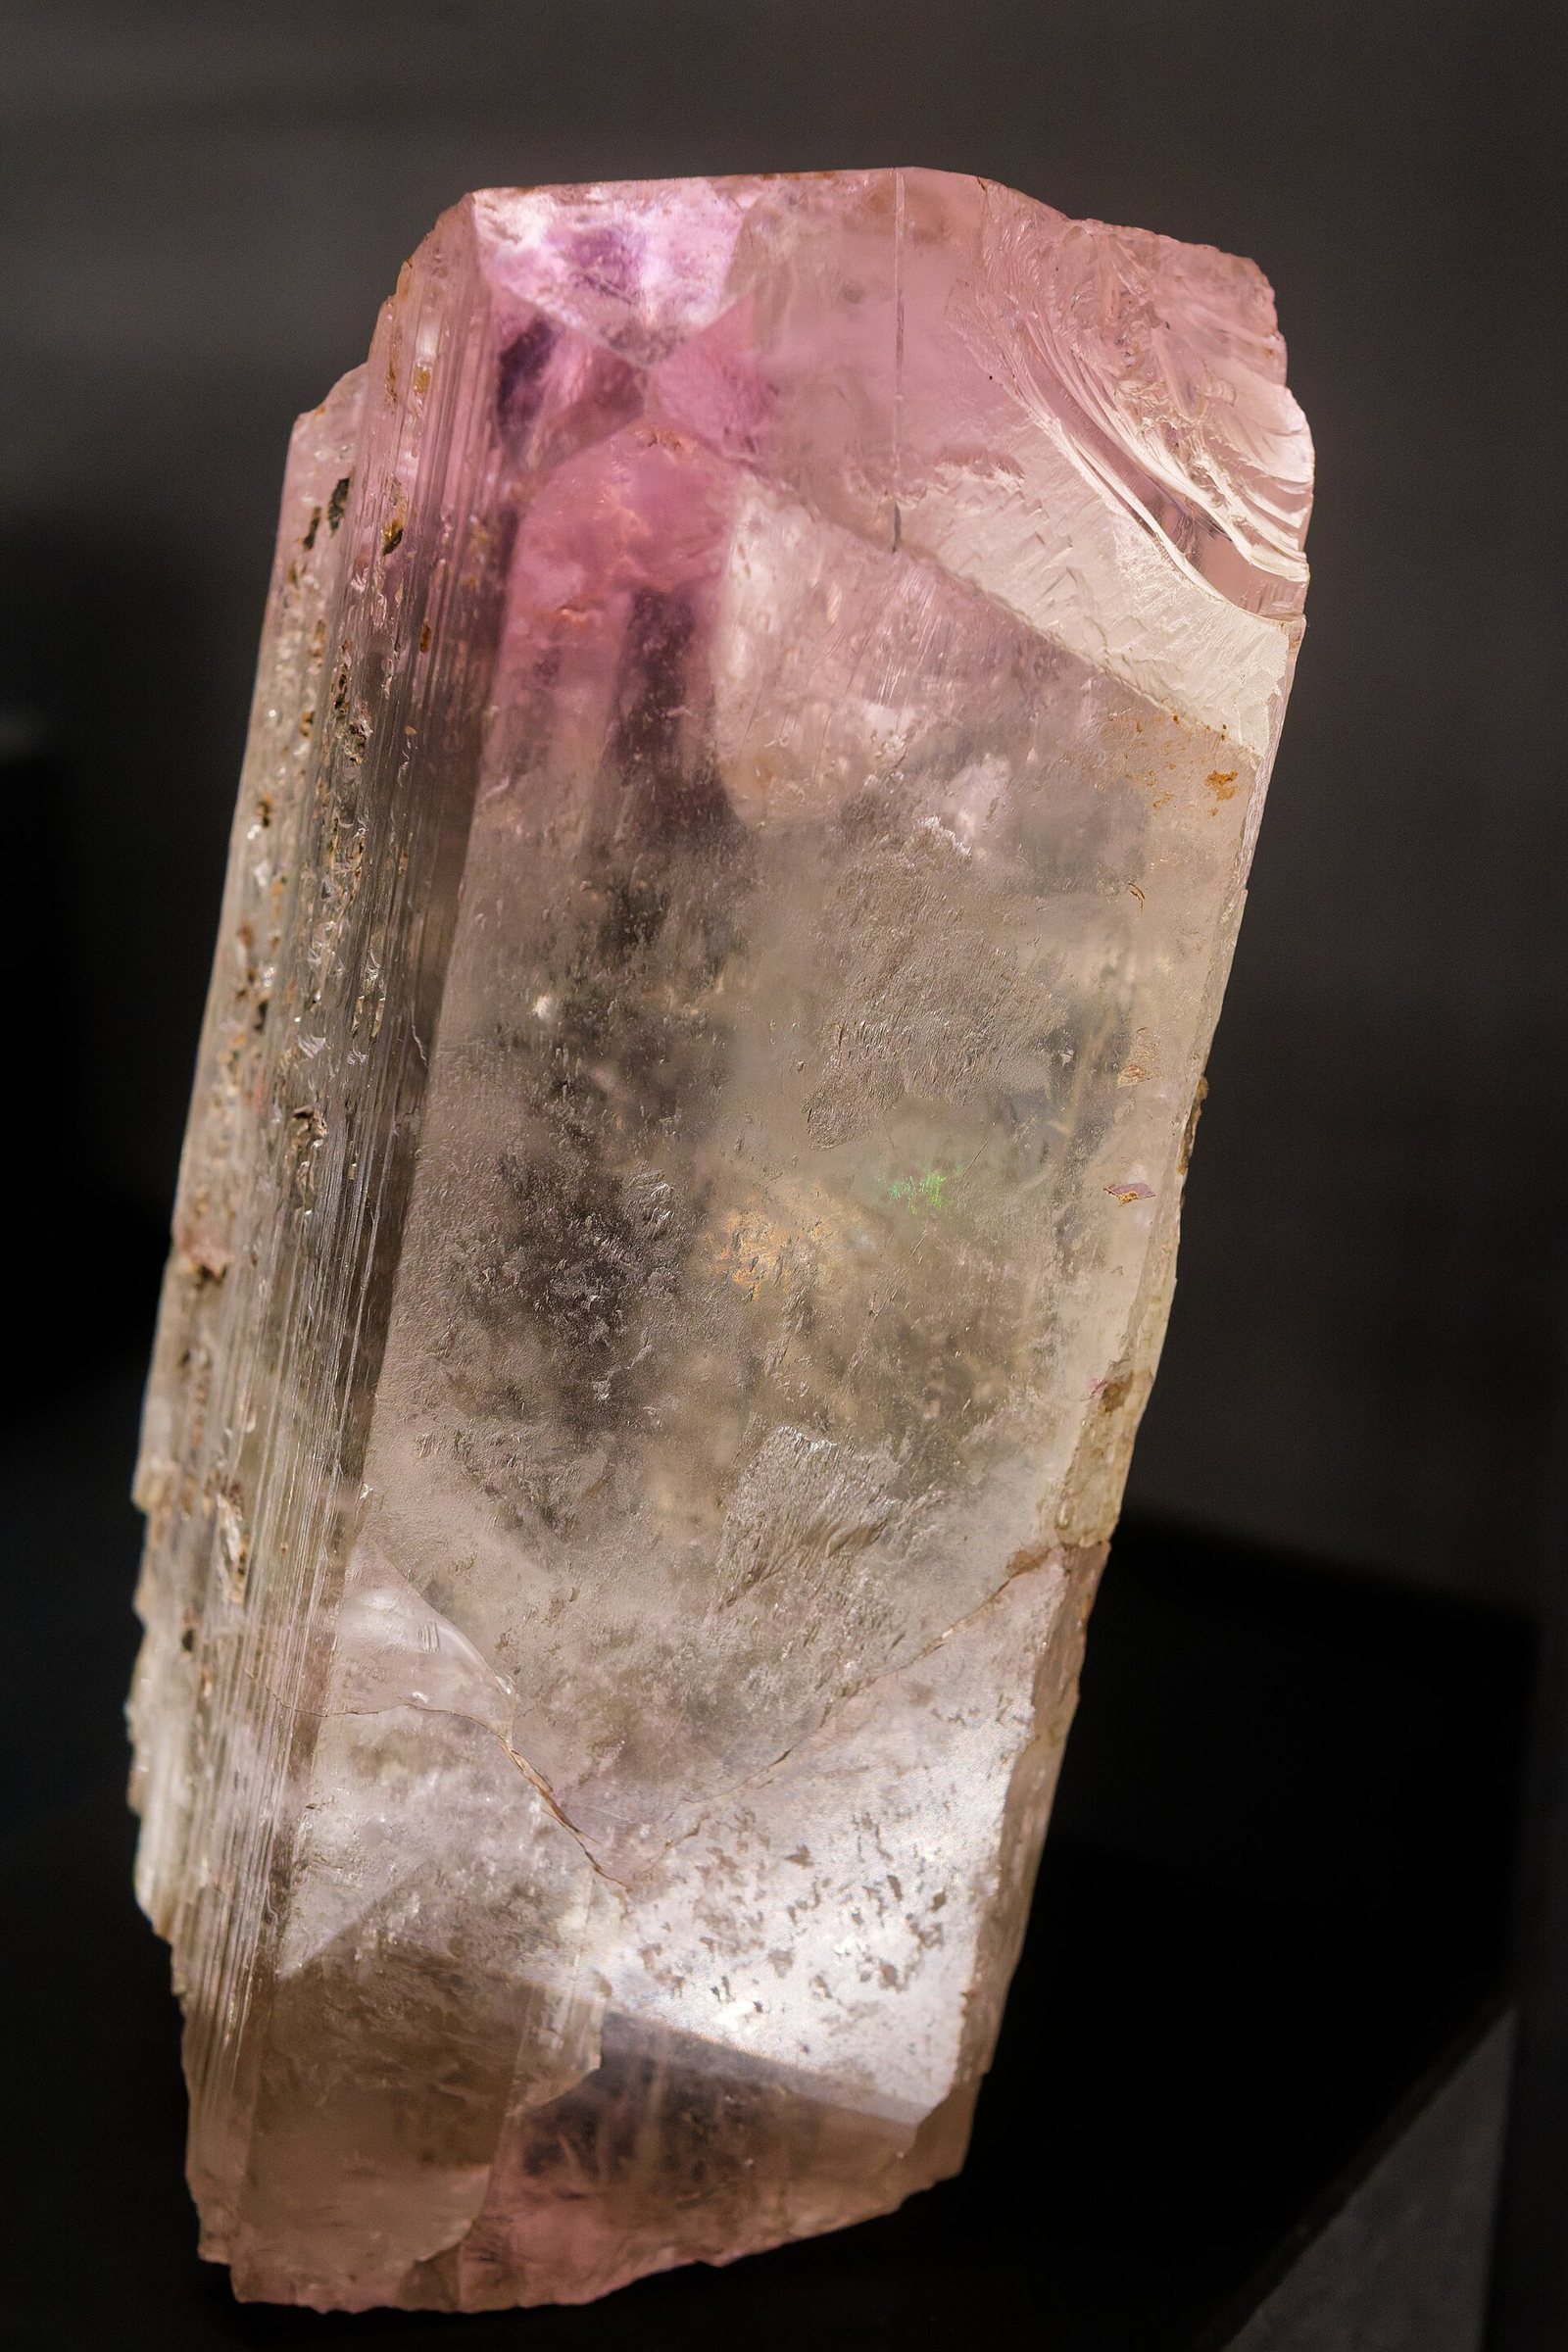
Lithium is one of the lightest elements, and its very lightness is part of why it does not appear in concentrated form everywhere: it does not fit comfortably into the crystal structures of most common rock-forming minerals, so it tends to be left behind as magmas cool and solidify. Over geological time, that rejection causes it to accumulate in the last fractions of a cooling granite body, where water-rich fluids carry it into cracks and cavities. The resulting rock type is called a pegmatite — a coarse-grained igneous rock whose outsized crystals reflect the slow, fluid-assisted growth conditions. When the right combination of lithium, aluminium, and silicon is present, the mineral spodumene crystallises, and a mineable deposit can form. Geologists label the most lithium-rich class of these bodies LCT pegmatites, shorthand for the lithium, caesium, and tantalum that tend to travel together through these late-stage fluids. The Greenbushes and Pilgangoora deposits in Western Australia are among the best-known examples.
The other principal source is entirely different in character. In high, arid plateaux — most famously the Andean altiplano spanning Chile, Argentina, and Bolivia — ancient lake basins have been concentrated by millions of years of evaporation into vast salt flats called salares. Rainwater that falls on the surrounding volcanic highlands dissolves lithium from the rocks and carries it into these closed basins, from which there is no outlet to the sea. Evaporation removes the water but leaves the dissolved salts behind, including lithium at concentrations that can reach into the thousands of milligrams per litre in the subsurface brines beneath the salt crust. This is not ore in the conventional sense — it is a mineral-rich solution sitting in the pores of sediments below ground. The concentration of lithium in that brine, measured in milligrams per litre, is the brine-deposit equivalent of ore grade.
A third deposit type is drawing attention as exploration expands: lithium-bearing claystones formed from the alteration of volcanic ash in ancient lake beds. The Thacker Pass deposit in the United States belongs to this category. Clay-hosted lithium presents different metallurgical challenges from either pegmatite or brine, and the technology to process it at scale is still being proved commercially. Each deposit type therefore represents not just a different geological setting but a different set of engineering and environmental problems to solve.
Turning ore into product Niveau 3
Spodumene concentrate leaving an Australian mine at roughly 6 percent Li₂O cannot go directly into a battery factory. It must first be converted into either lithium carbonate (Li₂CO₃) or lithium hydroxide monohydrate (LiOH·H₂O), the two traded chemicals that cathode manufacturers actually use. The conversion begins with a thermal step called calcination, in which spodumene is roasted at high temperature to transform the crystal structure from its natural alpha phase to a more reactive beta phase — without this step, the mineral resists acid attack. The roasted material is then leached with sulfuric acid, and the resulting lithium sulfate solution is purified through a series of precipitation and filtration stages to remove iron, calcium, magnesium, and other impurities. Final precipitation with soda ash yields lithium carbonate; reacting that carbonate with lime and then concentrating and crystallising the product yields lithium hydroxide. Each stage introduces recovery losses, and the cumulative yield from concentrate to battery-grade chemical is meaningfully less than one hundred percent, with the exact figure depending on feed quality and plant design.
Brine-derived lithium follows a different chemical route. After evaporation ponds have raised the lithium concentration, the enriched brine is treated to remove boron and other contaminants, then converted to lithium carbonate by precipitation. Producing hydroxide from brine is less straightforward than from spodumene and typically involves an intermediate carbonate step or electrolytic conversion. The dominant processing geography matters because it shapes where in the chain value is added. The cluster of chemical plants in Qinghai and Sichuan provinces in China refines both imported spodumene concentrate and domestic brine into battery-grade products. Australia's Kwinana plant represents an effort to capture more of that conversion step closer to the mine, but the economics of doing so outside of China's established cluster are not straightforward. Battery-grade purity specifications are stringent: trace levels of certain metallic impurities can degrade cell performance or safety, which means that the final refining and qualification steps are as technically demanding as any earlier stage in the chain.
The unit basis used in trade and statistics adds a layer of complexity. As noted in the data for this page, USGS production and reserve figures count contained lithium metal, not the carbonate or hydroxide that is actually shipped. One tonne of contained lithium corresponds to approximately 5.32 tonnes of lithium carbonate — so a figure quoted in lithium metal tonnes looks much smaller than the same quantity expressed in carbonate equivalent. Published data from different agencies and companies do not always use the same basis, and comparing them without adjusting for this conversion is a common source of apparent discrepancy.
Substitution and recycling Niveau 3
Within lithium-ion battery chemistry, lithium is not substitutable at the level of the cell. The electrochemical role it plays — as a small, light ion that moves rapidly between electrodes — is not replicated by sodium, magnesium, or any other element in a cell that also meets the energy density requirements of electric vehicles and portable electronics. Sodium-ion batteries are a genuine alternative technology: they are being produced commercially and are well suited to applications where energy density is less critical, such as stationary grid storage or short-range urban vehicles. However, they deliver less energy per unit of weight and volume than mature lithium-ion designs, and they use different cathode materials, meaning that a shift toward sodium-ion would reduce lithium demand in some segments rather than eliminate it. The long-run balance between these chemistries will depend on cost trajectories and on which applications each proves best suited to.
Recycling represents the most structurally significant potential source of secondary lithium. At the end of a battery's life, the lithium in the cells can in principle be recovered and returned to the supply chain. Hydrometallurgical recycling routes — which dissolve the cell materials in acid and selectively recover metals from solution — can achieve reasonably high lithium recovery rates, though lithium is consistently harder to recover economically than cobalt or nickel, which command higher prices and therefore justify more processing effort. Pyrometallurgical routes, which smelt the battery material at high temperature, tend to lose most of the lithium into slag. The practical constraint on recycling volumes today is straightforward: batteries installed in vehicles over the past several years have not yet reached the end of their useful life at scale, so the available end-of-life feedstock is still relatively small. As the installed base of electric vehicles ages, secondary supply from recycling will grow, but the lag between installation and end-of-life means that recycled material is unlikely to meet a large share of demand within this decade. Collection infrastructure, cell design for disassembly, and the economics of sorting mixed battery chemistries are all factors that determine how much of the available material is actually recovered rather than landfilled.
Where the chain is fragile Niveau 4
The geographic concentration of both production and reserves is the most frequently cited structural risk in the lithium supply chain, and it is real, though its character differs by stage of the chain. Mining is concentrated in Australia, Chile, and Argentina — a distribution that reflects geology rather than policy, since that is where the deposits happen to be — but these are politically stable jurisdictions with established mining codes. The more pronounced concentration sits in chemical processing. The refining of spodumene concentrate and brine into battery-grade lithium carbonate and hydroxide occurs overwhelmingly within China, and that concentration is not a function of resource endowment but of accumulated industrial capacity, infrastructure, and the economics of operating within an established cluster. A disruption at this processing stage would propagate through the chain regardless of whether the mining end remained intact. The Kwinana plant in Australia and various announced projects elsewhere represent efforts to build processing capacity outside China, but these projects take years from decision to operation.
Lead times are a genuine constraint. A new hard-rock lithium mine typically requires many years between initial resource definition and first production, with permitting, feasibility studies, financing, and construction each adding time. Brine projects are similarly slow because the evaporation-based process cannot be meaningfully accelerated, and DLE projects face an additional layer of uncertainty in that the technology must be demonstrated at commercial scale before it can underpin project financing at the required confidence level. The consequence is that supply cannot respond quickly to a sustained demand signal — a mismatch that was visible in the extreme price volatility between 2021 and 2025, when battery-grade lithium carbonate moved from $11,700 per metric tonne to $63,700 and then fell back to around $9,000 over the space of four years, as the data on this page shows. Those swings reflect the structural inelasticity of supply in the short run rather than any fundamental change in the resource base.
A further source of uncertainty in published supply figures is the reporting convention problem noted in the unit basis entry above. When USGS and industry sources, national geological surveys, and company disclosures each present figures on a different basis — contained metal versus lithium carbonate equivalent versus lithium oxide — apparent disagreements in reserve or production figures often dissolve under unit conversion rather than reflecting genuine data conflicts. Researchers comparing sources should verify the unit basis before drawing conclusions. Additionally, brine reserve estimates carry hydrogeological uncertainty that hard-rock reserve estimates do not: the volume, porosity, and connectivity of the brine-bearing formation, and the rate at which brine naturally recharges, are all parameters estimated from subsurface data that is inherently sparse, and different modelling assumptions can produce materially different reserve figures for the same salar. This uncertainty is not always clearly flagged in headline reserve numbers.
Waar het in het gesteente vandaan komt
Alle ertsmineralen →Dit zijn de mineralen die daadwerkelijk lithium. Een afzetting is alleen een ertslichaam als een van beide voldoende geconcentreerd is om de winning ervan te bekostigen.
Lithium Brine
Not a mineral but a saturated salt solution beneath a salar. Concentrated by solar evaporation over 12-24 months, or…
Spodumene
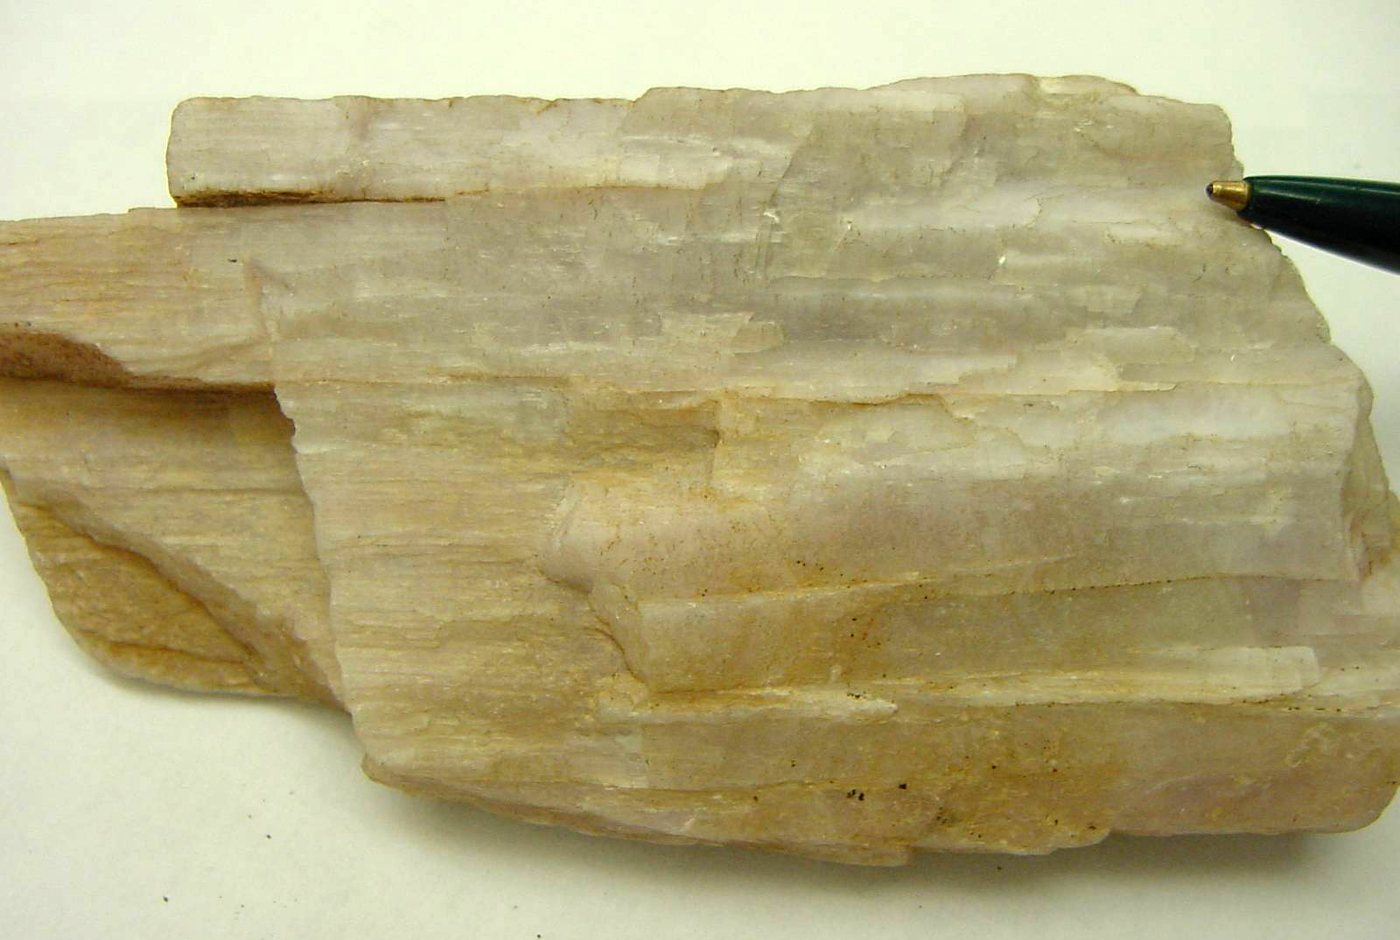
The main hard-rock lithium mineral. Fresh spodumene contains up to 8% Li2O; concentrate is sold at about 6%.
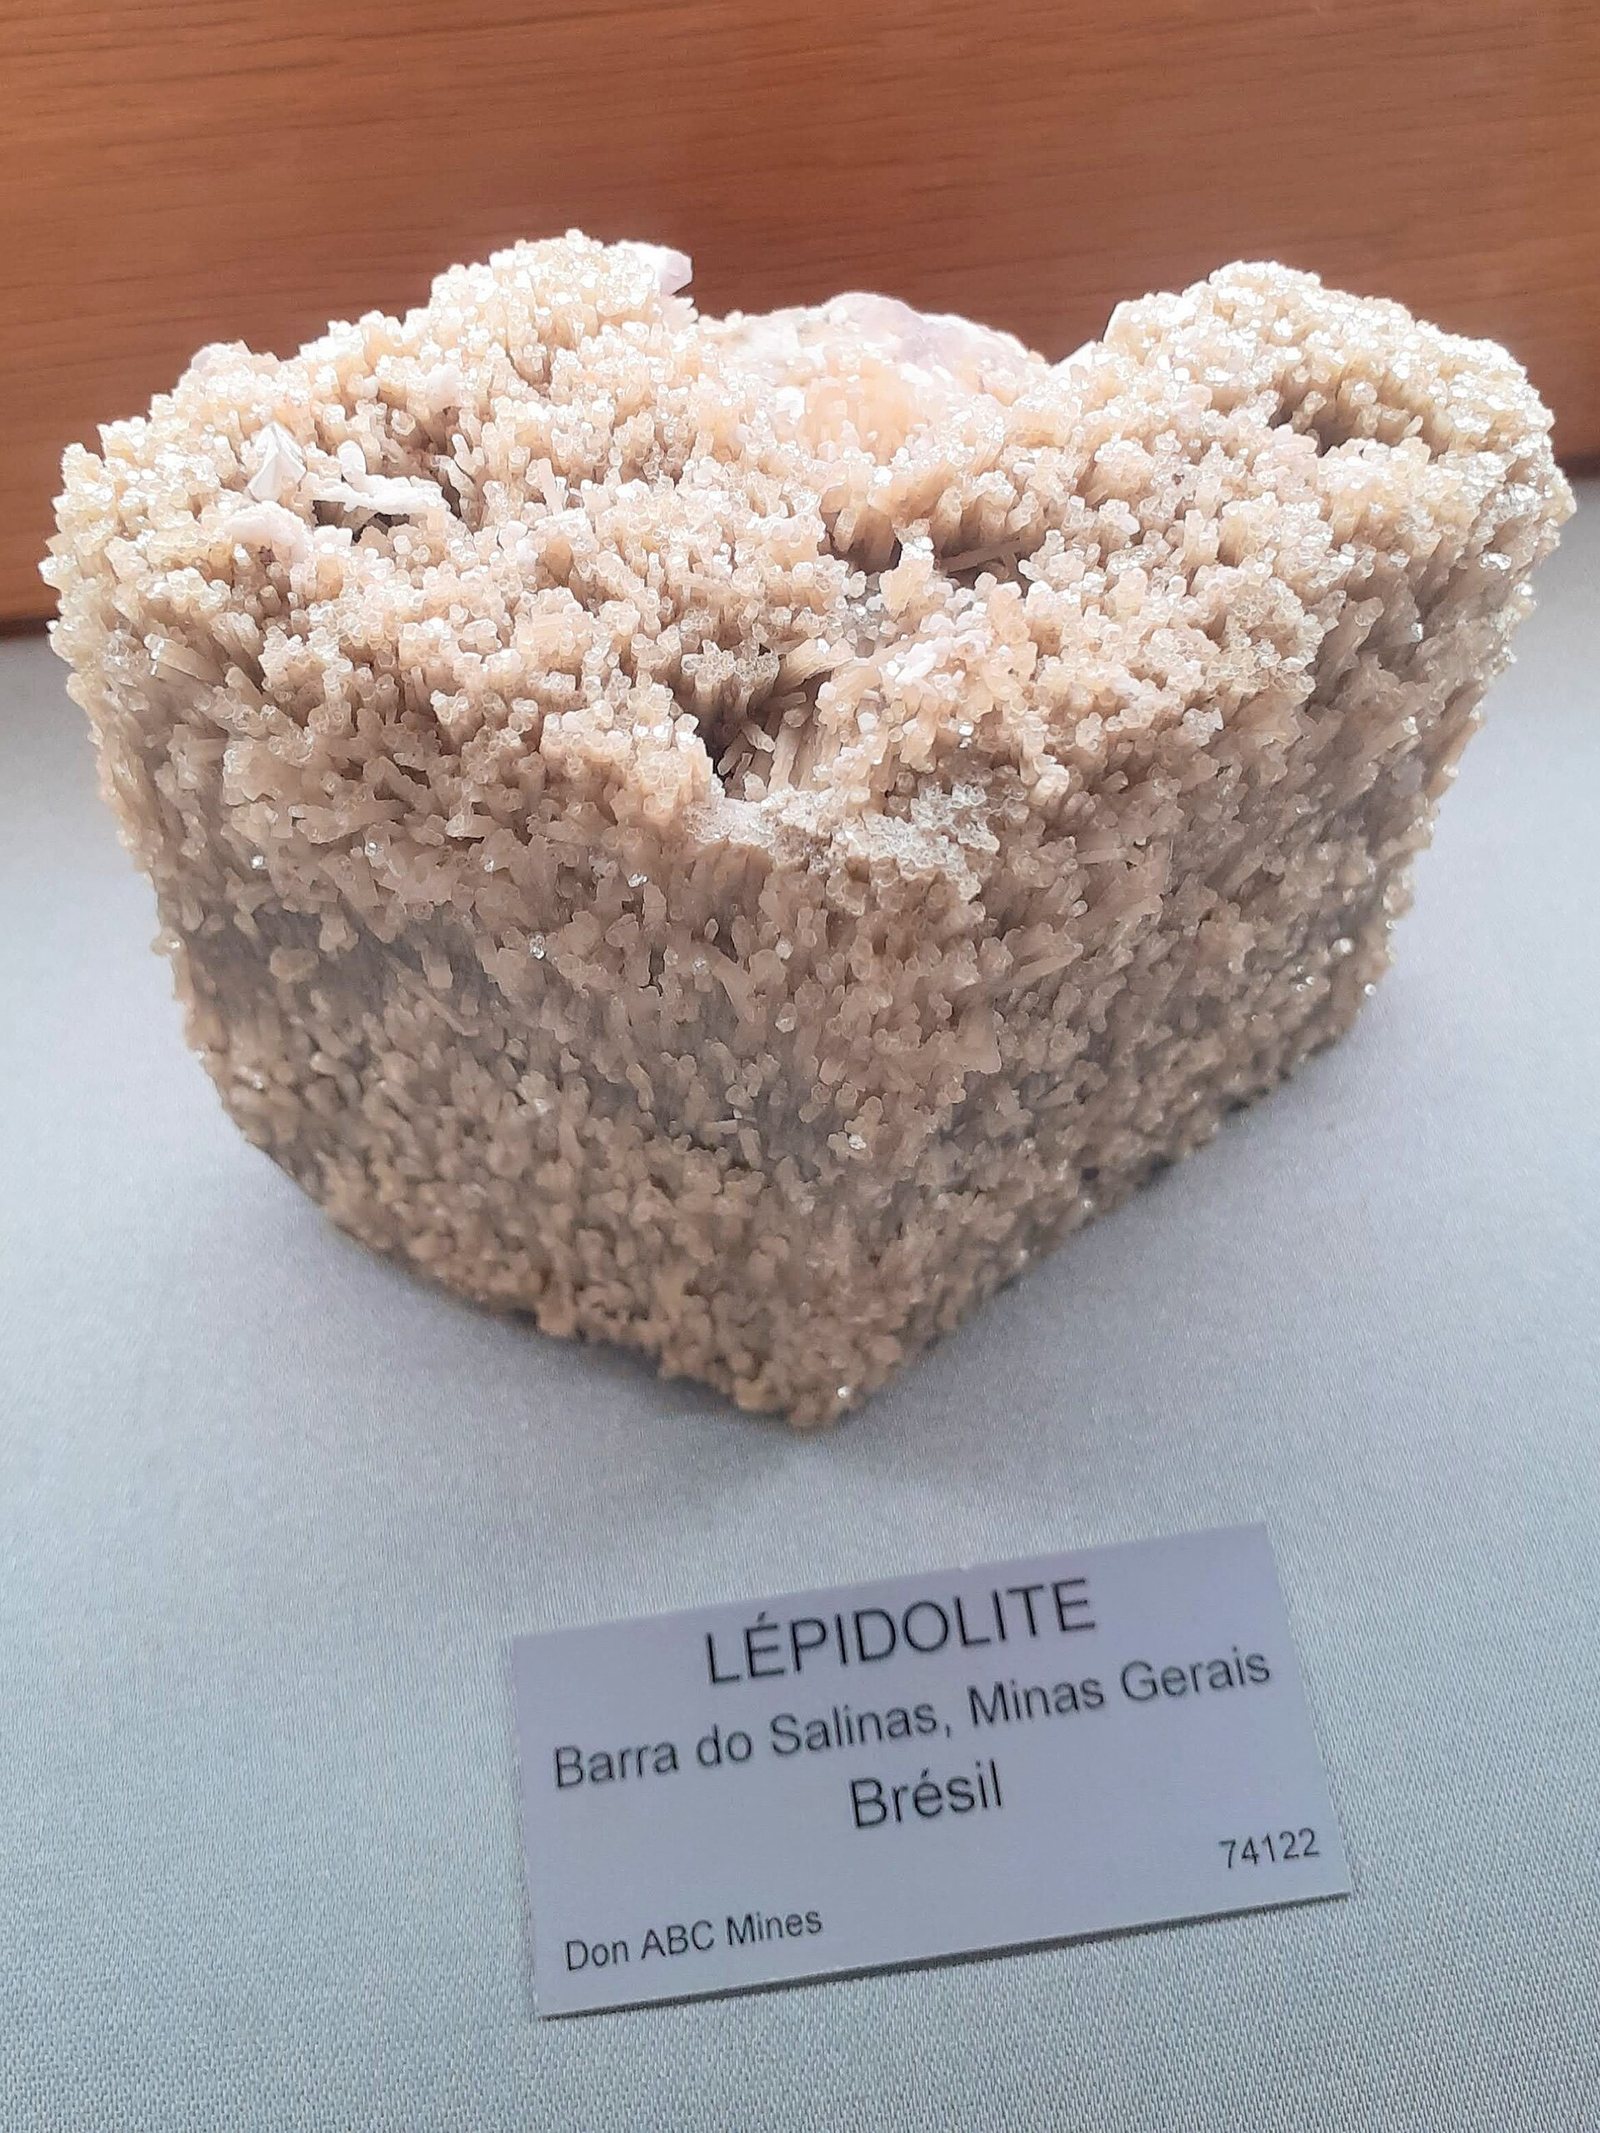
Lepidolite
A lithium mica. Rich in fluorine, which complicates processing, but also carries rubidium and caesium.
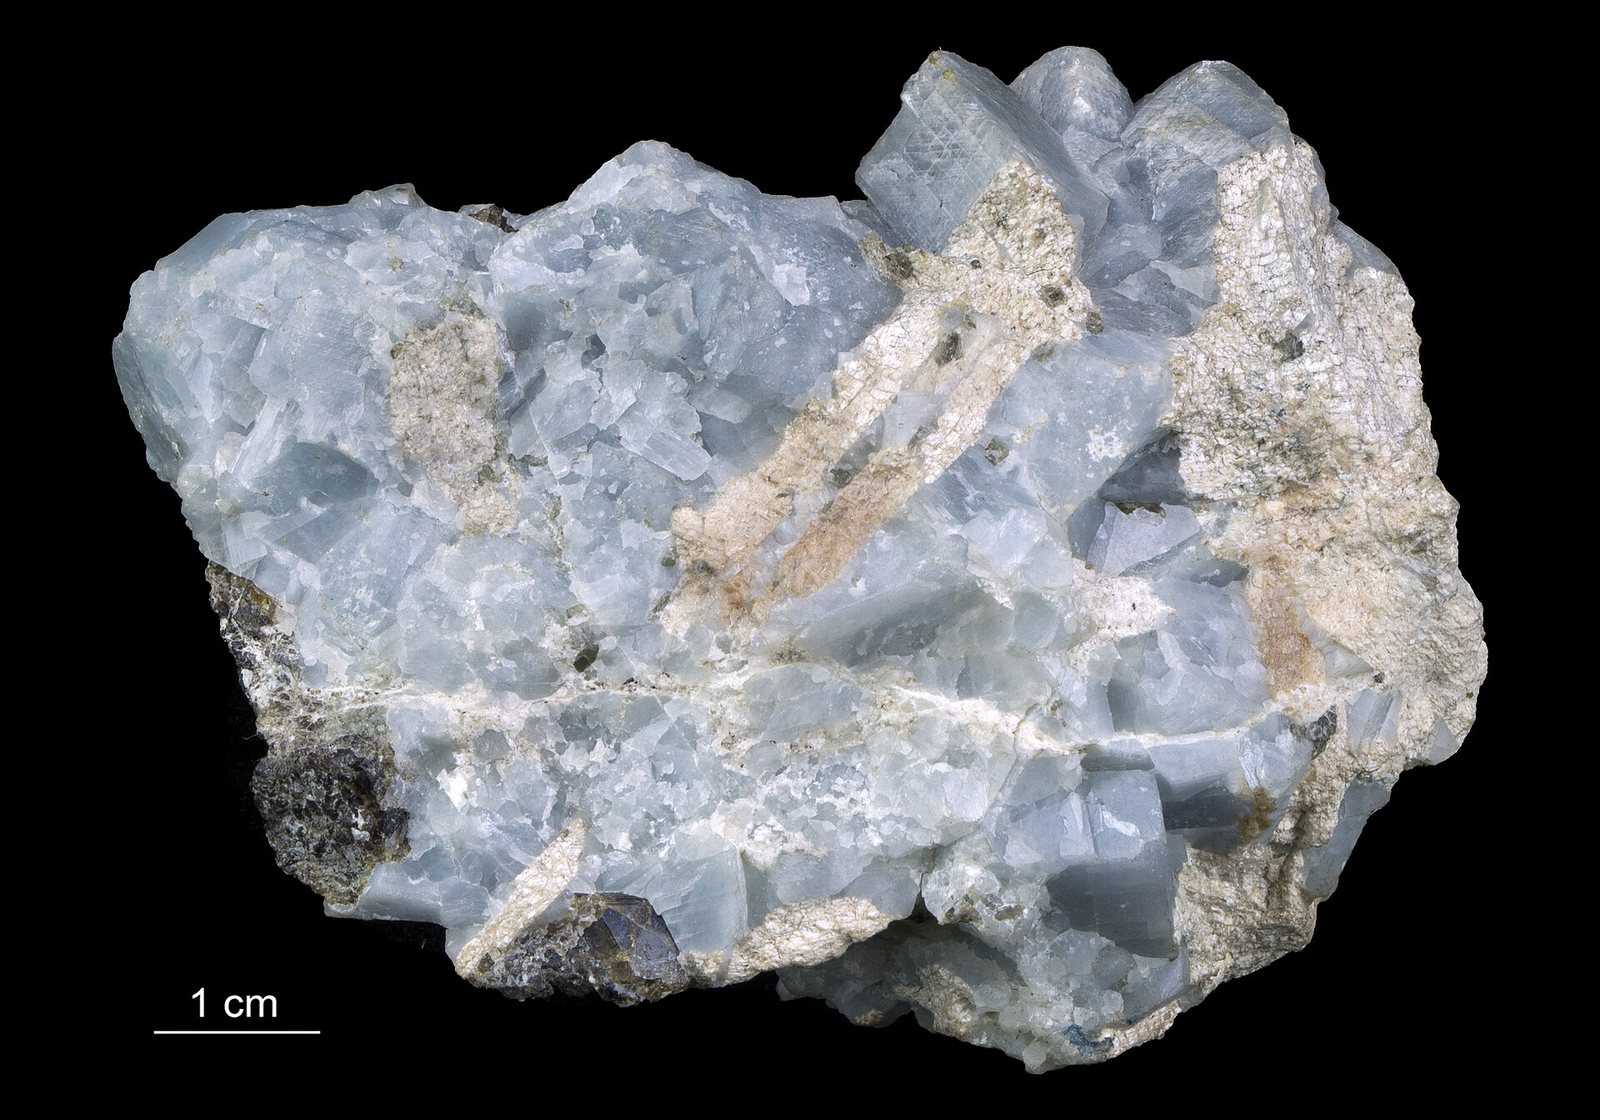
Petalite
A lower-grade lithium silicate, historically important in glass and ceramics.
Wie het produceert
Bekijk het op een kaart →Mine production
Mine productionmetric tons 2025 (geschat) Wereldtotaal 290,000 metric tons
USGS Mineral Commodity Summaries 2026 · USGS tonnages count CONTAINED LITHIUM METAL, not lithium carbonate. One tonne of lithium metal is about 5.32 tonnes of lithium carbonate (Li2CO3). · bron ↗
Schuif de tabel zijwaarts voor de overige kolommen.
| Land | Productie | Aandeel van de wereld |
|---|---|---|
| Australia | 92,000 | 31.7% |
| China | 62,000 | 21.4% |
| Chile | 56,000 | 19.3% |
| Zimbabwe | 28,000 | 9.7% |
| Argentina | 23,000 | 7.9% |
| Brazil | 12,000 | 4.1% |
| Mali | 9,400 | 3.2% |
| Canada | 5,600 | 1.9% |
| Portugal | 380.0 | 0.1% |
| Other countries | Zero | — |
| United States | Withheld | — |
| Wereldtotaal | 290,000 | 100% |
"Ingehouden" betekent dat de USGS het cijfer heeft onderdrukt om gegevens van een individueel bedrijf niet prijs te geven — het betekent niet nul. Landrijen tellen niet altijd op tot het wereldtotaal, omdat de bron elk cijfer afzonderlijk afrondt en niet altijd een regel "overige landen" uitsplitst.
Wie de reserves bezit
Reserves
Reservesmetric tons 2025
USGS Mineral Commodity Summaries 2026 · bron ↗
| Land | Reserves | Aandeel van de wereld |
|---|---|---|
| Chile | 9,200,000 | 24.9% |
| Australia | 8,400,000 | 22.7% |
| China | 4,600,000 | 12.4% |
| United States | 4,400,000 | 11.9% |
| Argentina | 4,400,000 | 11.9% |
| Other countries | 2,400,000 | 6.5% |
| Canada | 1,600,000 | 4.3% |
| Brazil | 540,000 | 1.5% |
| Zimbabwe | 500,000 | 1.4% |
| Mali | 370,000 | 1.0% |
| Portugal | 60,000 | 0.2% |
| Wereldtotaal | 37,000,000 | 100% |
Prijs
annual average-real, battery-grade lithium carbonate, dollars per metric ton
Jaargemiddeldedollars per metric ton
Grondslag: annual average-real, battery-grade lithium carbonate, dollars per metric ton. Jaargemiddelden zoals gepubliceerd in USGS Mineral Commodity Summaries 2026 · bron ↗. Dit zijn referentiejaargemiddelden, geen live marktkoers.
Mijnen die het produceren
Alle mijnen →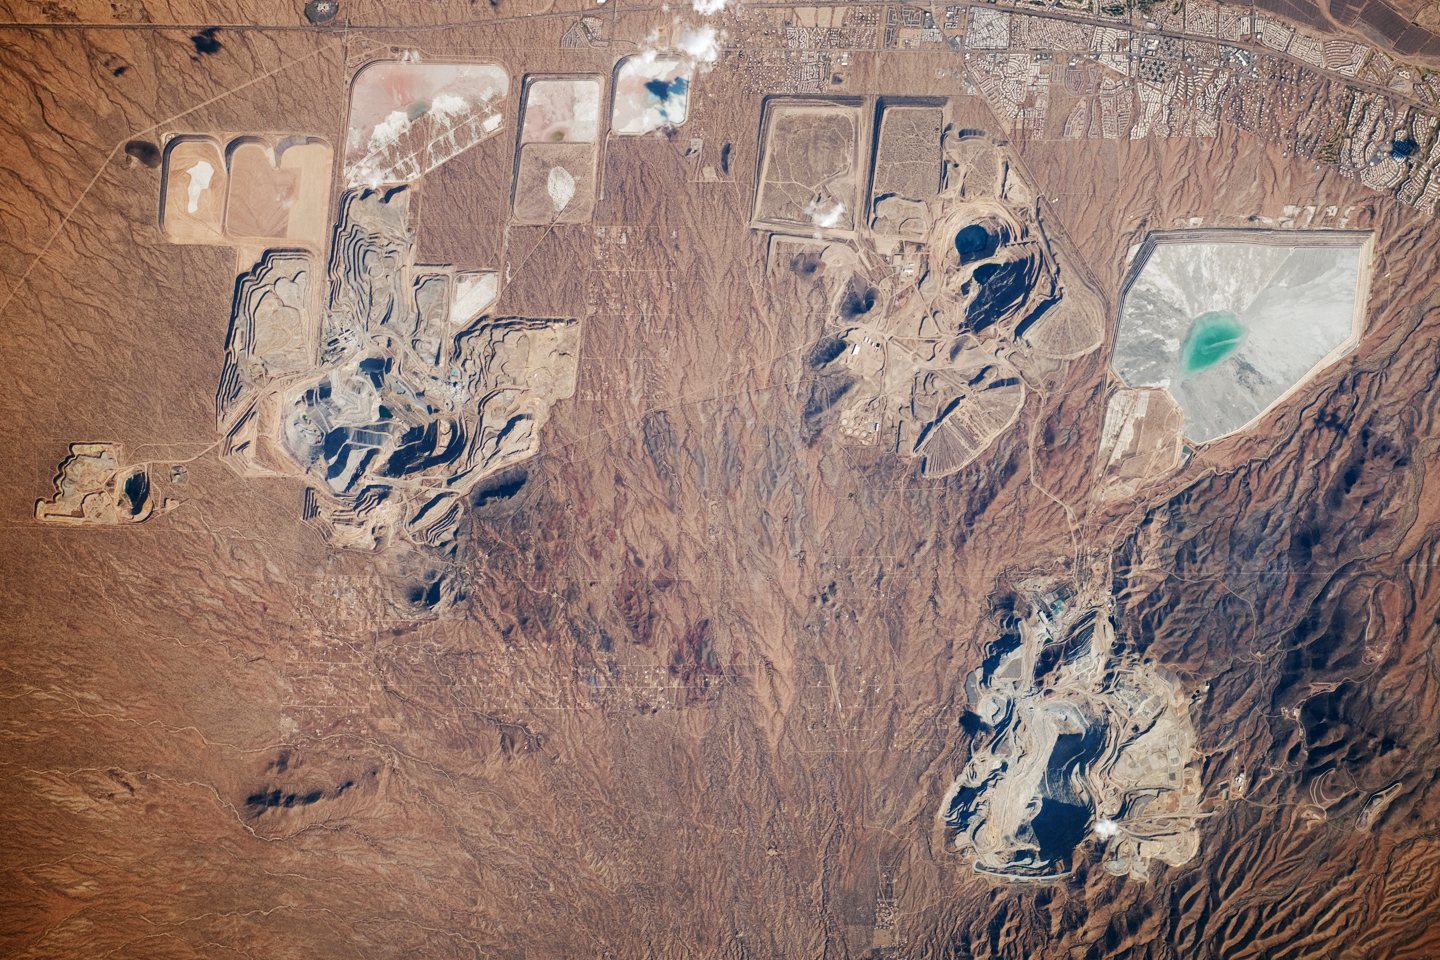
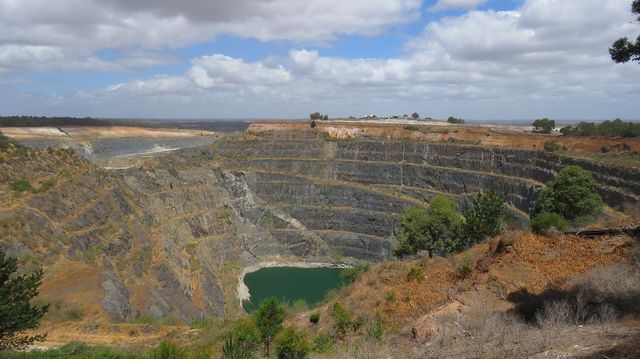
Greenbushes
The largest hard-rock lithium mine in the world.
Pilgangoora
One of the largest independent hard-rock lithium operations.
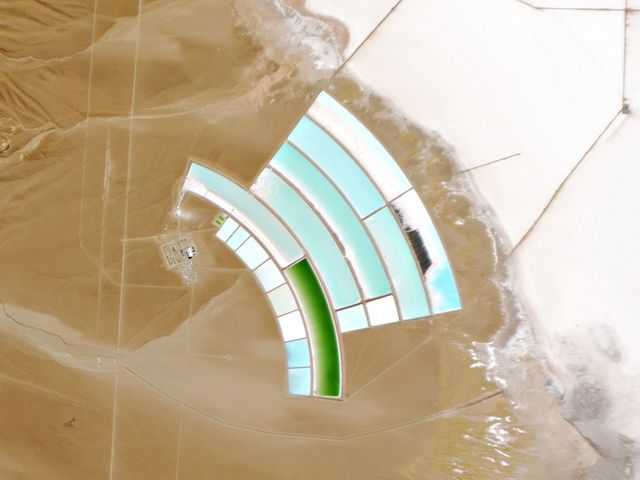
Salar de Atacama
The highest-grade and most productive lithium brine operation in the world.
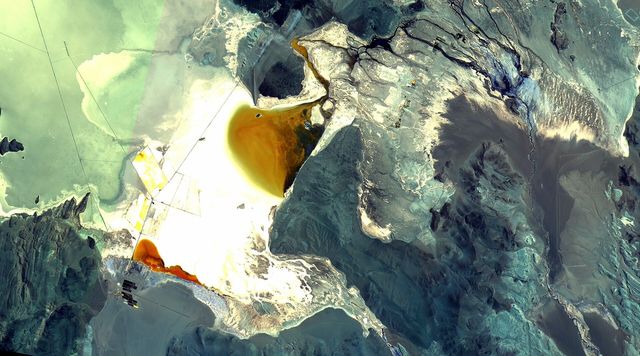
Salar del Hombre Muerto
The longest-running direct lithium extraction operation in the world.
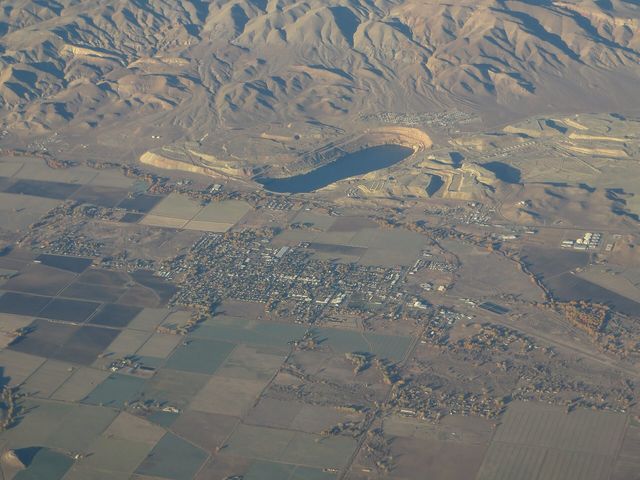
Thacker Pass
The largest known lithium resource in the United States.
Waar het wordt verwerkt en geraffineerd
| Installatie | Soort | Fase | Land | Rol |
|---|---|---|---|---|
| CATL Ningde Plants | Gigafabriek | Component | China | Invoer |
| Gigafactory Nevada | Gigafabriek | Component | United States | Invoer |
| Kwinana Lithium Hydroxide Plant | Chemische fabriek | Raffinage | Australia | Invoer |
| Qinghai & Sichuan Lithium Chemical Cluster | Chemische fabriek | Raffinage | China | Invoer |
Waarvoor het wordt gebruikt
Alle eindmarkten →| Eindmarkt | Wat het daar doet | Belang |
|---|---|---|
| Electric Vehicles | The cathode and electrolyte salt | Definiëren |
| Consumer Electronics | Battery | Definiëren |
| Grid Storage | Lithium-ion systems | Definiëren |
| Power Grids | Battery storage on the network | Belangrijk |
| Robotics & Automation | On-board battery | Belangrijk |
Hoeveel een technologie ervan nodig heeft
| Technologie | Hoeveelheid | Genoteerd | Grondslag |
|---|---|---|---|
| LFP Lithium-Ion Battery About 0.09 kg Li per kWh. | 5.50–8.00 kg contained lithium | per 75 kWh pack | Contained metal |
| NMC Lithium-Ion Battery About 0.10 kg Li per kWh of cell capacity. | 6.00–9.00 kg contained lithium | per 75 kWh pack | Contained metal, not carbonate |
Indicative range compiled from published technology studies and chemistry; verify against a manufacturer specification before use. Voer deze getallen op elke schaal uit in de materiaalcalculator →
Exportbeperkingen
| Land | Controle | Van toepassing op |
|---|---|---|
| China | Export licensing requirement for materials and technologies | Antimony (2024), bismuth (2025), synthesized diamond (2025), gallium (2023), germanium (2023), graphite (2023), indium (2025), magnesium materials (2024), molybdenum (2025), rare earths (2025), silver (2026), tellurium (2025), tungsten (2025), and items related to lithium batteries and artificial graphite anode materials (2025). ↗ |
| Namibia | Export ban | Ores and concentrates of cobalt, graphite, lithium, manganese, and rare earths (2023). ↗ |
| Zimbabwe | Export ban | Lithium ore (2022). ↗ |
USGS Mineral Commodity Summaries 2026, table 4 — controls in effect as of January 2026, excluding controls since lifted.
Volg het over de grenzen
Alle trajecten →Waar een zending van dit materiaal werkelijk naartoe gaat — elk land, elke bewaarder, en wat er bij elke stap achterblijft.
Australian spodumene to a battery, the fast way Eight weeks instead of eighteen months, at the cost of a great deal more energy. Chilean brine to a battery in a car The ore is water. The first year and a half of processing is done by the sun, for free.